Knee Osteoarthritis Market Size, Share, Trend Report 2026 to 2035
What is Knee Osteoarthritis Market Size?
Global Knee Osteoarthritis Market Size is valued at USD 7.88 Bn in 2025 and is predicted to reach USD 24.48 Bn by the year 2035 at a 12.2% CAGR during the forecast period for 2026 to 2035.
Knee Osteoarthritis Market Size, Share & Trends Analysis Distribution by Drug Type (Hyaluronic Acid, Non-steroidal Anti-inflammatory Drugs (NSAIDs), Analgesics, Corticosteroid, Others), by Route of Administration (Oral, Parenteral, Others), by Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies) and Segment Forecasts, 2026 to 2035.
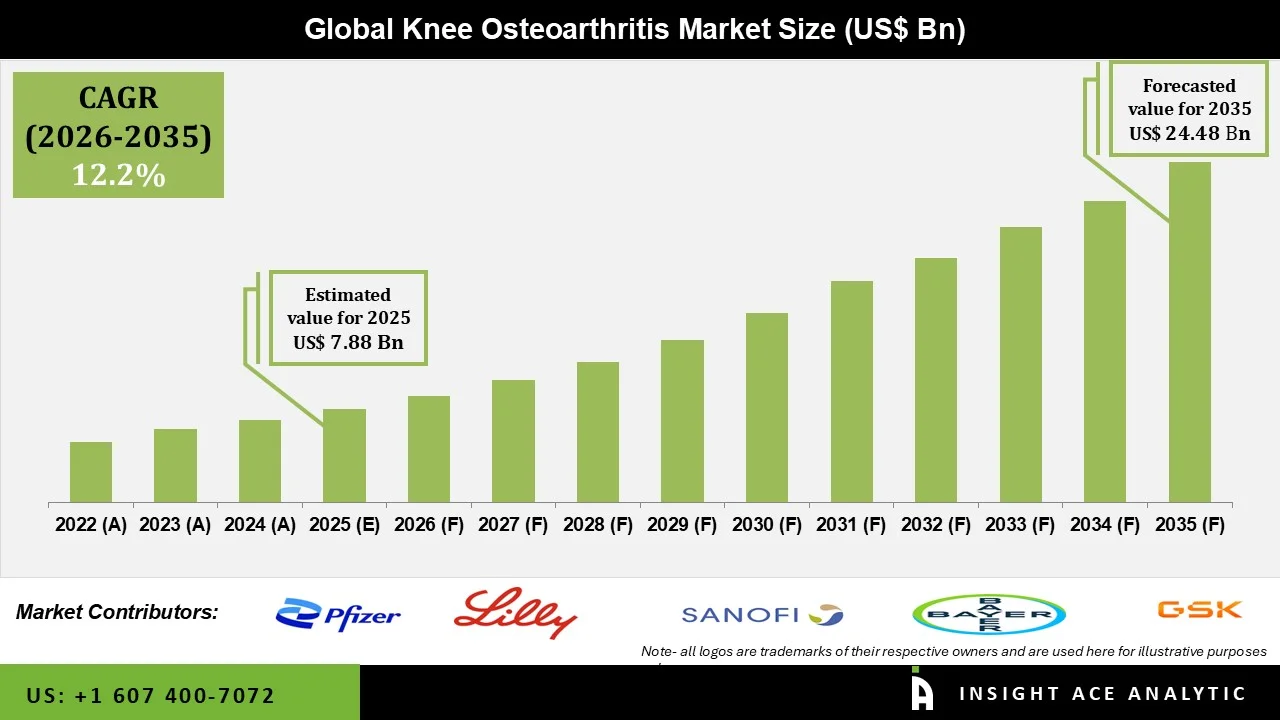
The Knee Osteoarthritis Market is growing steadily as more people develop knee osteoarthritis, especially among older adults, those with obesity, and people with past knee injuries or physically demanding jobs. This condition causes the cartilage and other parts of the knee to wear down over time, leading to pain, stiffness, swelling, less mobility, and trouble with daily tasks. As more people learn about knee osteoarthritis and look for better treatments, there is rising demand for diagnostic tests, medications, injections, physical therapy, and surgeries. There are many treatment options available, including NSAIDs, pain relievers, corticosteroids, hyaluronic acid injections, physical therapy, and surgeries like knee replacement. More people are interested in treatments that are less invasive or do not require surgery, which is pushing healthcare providers and drug companies to create therapies that offer longer-lasting pain relief and better joint function. Intra-articular injections, especially those with hyaluronic acid or corticosteroids, are still used for patients who do not get enough relief from standard treatments.
Advancements in healthcare technology are also influencing the knee osteoarthritis market. Improved imaging techniques, digital diagnostic tools, wearable devices, and data-driven healthcare solutions are helping physicians assess disease progression and develop more personalised treatment plans. Artificial intelligence and machine learning are increasingly being explored for early detection, medical imaging analysis, patient monitoring, and treatment decision support. These developments may improve diagnosis and enable healthcare professionals to better understand individual patient needs. Rising obesity rates are also helping the market grow. Carrying extra weight puts more strain on the knees and raises the risk of getting or worsening osteoarthritis. At the same time, more people are living longer, which means more patients need long-term care for joint problems. People are also becoming more aware of the benefits of early diagnosis, healthy habits, weight control, exercise, and physical therapy, so they are seeking treatment sooner
Even with these opportunities, the market still faces challenges. Advanced treatments and surgeries can be expensive, and people in developing areas may not have access to specialized care. There are also risks with some treatments, and insurance coverage can vary. Non-surgical treatments do not work the same for everyone, so doctors need to carefully choose the best option for each patient. Overall, the long-term outlook for the Knee Osteoarthritis Market is positive. More people are developing the disease, the population is aging, obesity rates are rising, and there is more awareness about joint health. Ongoing improvements in diagnosis and treatment are also helping the market grow. As healthcare providers focus more on early care, personalized treatment, less invasive procedures, and better long-term results, the need for new therapies and management solutions is likely to keep rising.
Competitive Landscape
Which are the Leading Players in the Knee Osteoarthritis Market?
- Pfizer Inc.
- Eli Lilly and Company
- Sanofi
- Bayer AG
- GSK plc
- Novartis AG
- AbbVie Inc.
- Merck & Co., Inc.
- Johnson & Johnson
- Anika Therapeutics, Inc.
Market Dynamics
Driver
Rising Prevalence of Knee Osteoarthritis and Growing Geriatric Population
The increasing prevalence of knee osteoarthritis is a key factor supporting market growth. The risk of developing osteoarthritis rises with age, and the growing geriatric population is creating a larger pool of patients requiring long-term pain management and mobility support. Obesity, previous knee injuries, physically demanding activities, and sedentary lifestyles can further increase the risk of knee osteoarthritis. As more patients seek treatment to manage pain, stiffness, and reduced mobility, demand for medications, intra-articular injections, rehabilitation, and other treatment options is expected to increase.
Restraint / Challenge
High Treatment Costs and Limited Access to Advanced Care
Despite the growing need for treatment, the Knee Osteoarthritis Market faces challenges related to the cost of long-term care and advanced treatment options. Surgical procedures such as total knee replacement can be expensive, while newer therapies and specialised interventions may not be affordable or readily available to all patients. Limited access to orthopaedic specialists and advanced healthcare facilities, particularly in developing and rural areas, can also delay diagnosis and treatment. In addition, differences in reimbursement policies and patient responses to non-surgical therapies can affect treatment decisions and market adoption.
Hyaluronic Acid Segment is Expected to Drive the Knee Osteoarthritis Market
The hyaluronic acid segment is expected to remain an important part of the Knee Osteoarthritis Market, as these injections provide symptomatic relief and support joint function in certain patients. Hyaluronic acid is administered directly into the knee joint and is commonly considered when conventional pain-management approaches do not provide sufficient relief. Continued interest in minimally invasive treatment options, longer-lasting symptom management, and improving patient mobility is expected to support demand for hyaluronic acid-based therapies.
Parenteral Segment is Expected to Drive the Knee Osteoarthritis Market
The parenteral segment is expected to hold an important position in the market because several commonly used knee osteoarthritis therapies, including intra-articular injections, are administered through this route. Injections can deliver treatment directly to the affected joint and are used for patients who require alternatives to oral medications. Growing preference for minimally invasive procedures and increasing use of injectable therapies for symptom management are expected to support the segment during the forecast period.
Why North America Leads the Knee Osteoarthritis Market?
North America is expected to maintain a leading position in the Knee Osteoarthritis Market due to its ageing population, high prevalence of obesity, advanced healthcare infrastructure, and strong access to orthopaedic and pain-management services. The U.S. has a well-established healthcare system with widespread use of prescription medicines, injectable therapies, physical rehabilitation, and knee replacement procedures.
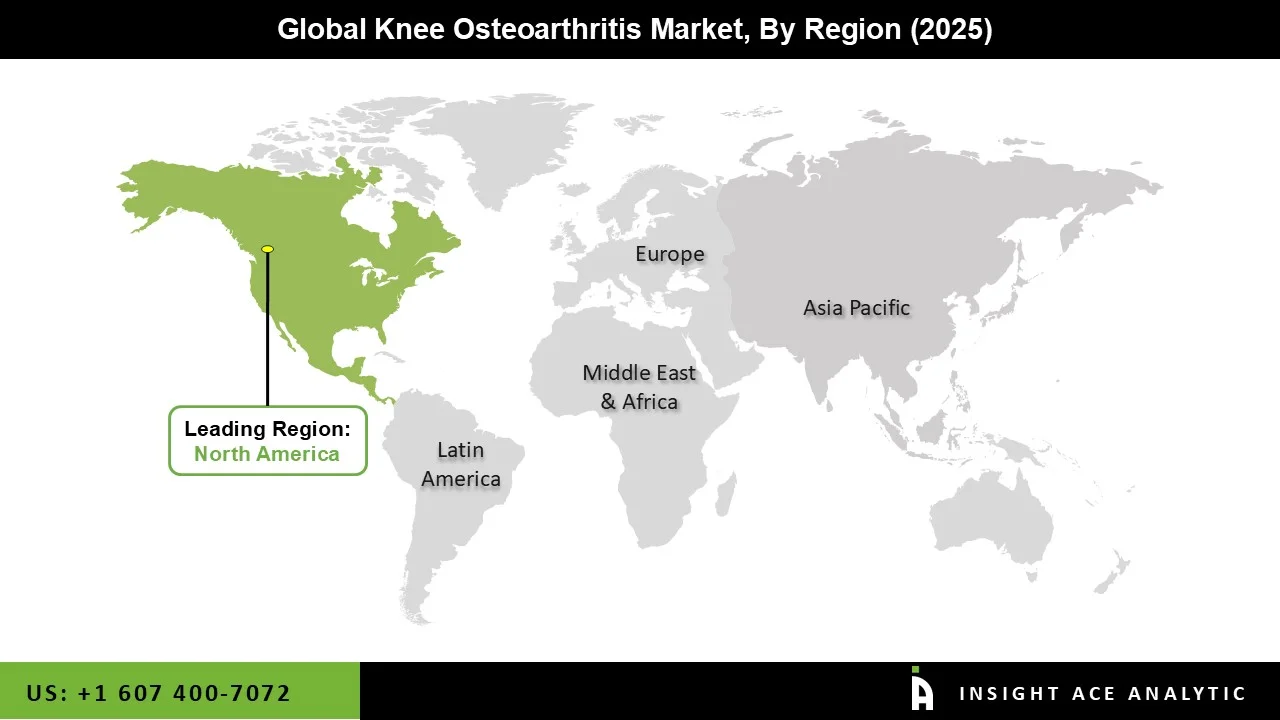
Growing awareness of osteoarthritis management and the availability of specialised orthopaedic care are also supporting market development. In addition, pharmaceutical and medical device companies in the region continue to invest in improved treatment options and minimally invasive approaches. These factors, together with relatively strong healthcare spending and access to advanced therapies, are expected to support the region’s continued market position. Asia Pacific is expected to see strong growth in the coming years.
Key Developments-
• In December 2025, Eli Lilly and Company announced positive Phase 3 TRIUMPH-4 results for retatrutide in adults with obesity or overweight and knee osteoarthritis. The investigational therapy delivered significant weight loss along with substantial improvements in knee osteoarthritis pain and physical function.
• In July 2025, Johnson & Johnson announced a strategic co-promotion agreement with Pacira BioSciences to expand its early-intervention offering for knee osteoarthritis. The agreement included ZILRETTA, an extended-release intra-articular corticosteroid injection for osteoarthritis-related knee pain, as well as professional education initiatives focused on non-surgical treatment options.
Knee Osteoarthritis Market Report Scope :
| Report Attribute | Specifications |
| Market size value in 2025 | USD 7.88 Bn |
| Revenue forecast in 2035 | USD 24.48 Bn |
| Growth Rate CAGR | CAGR of 12.2% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2021 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | Drug Type, Route of Administration, Distribution Channel and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; France; Italy; Spain; South Korea; Southeast Asia |
| Competitive Landscape | Pfizer Inc., Eli Lilly and Company, Sanofi, Bayer AG, GSK plc, Novartis AG, AbbVie Inc., Merck & Co., Inc., Johnson & Johnson, Anika Therapeutics, Inc. |
| Customization Scope | Free customisation report with the procurement of the report; modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customized to your particular study requirements. |
Segmentation of Knee Osteoarthritis Market:
Knee Osteoarthritis Market by Drug Type-
- Hyaluronic Acid
- Non-steroidal Anti-inflammatory Drugs (NSAIDs)
- Analgesics
- Corticosteroid
- Others
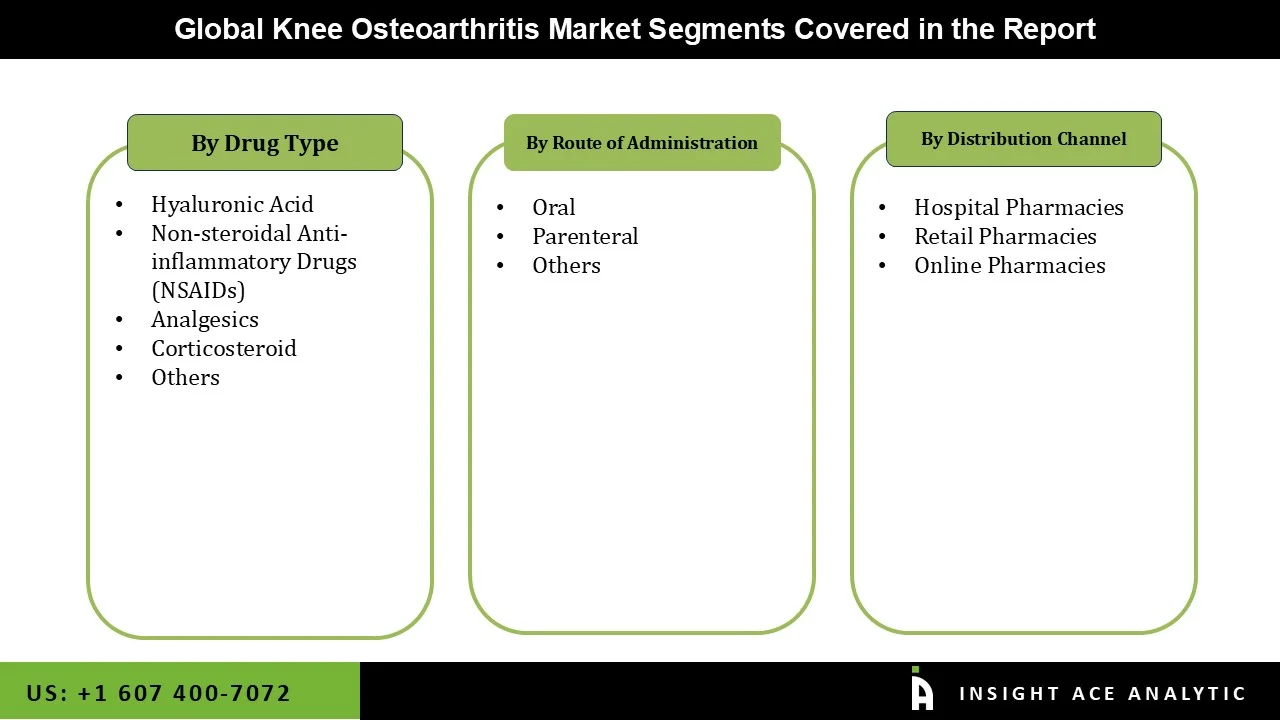
Knee Osteoarthritis Market by Route of Administration-
- Oral
- Parenteral
- Others
Knee Osteoarthritis Market by Distribution Channel-
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Knee Osteoarthritis Market by Region-
- North America-
- The US
- Canada
- Europe-
- Germany
- The UK
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific-
- China
- Japan
- India
- South Korea
- South East Asia
- Rest of Asia Pacific
- Latin America-
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Middle East and Africa-
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
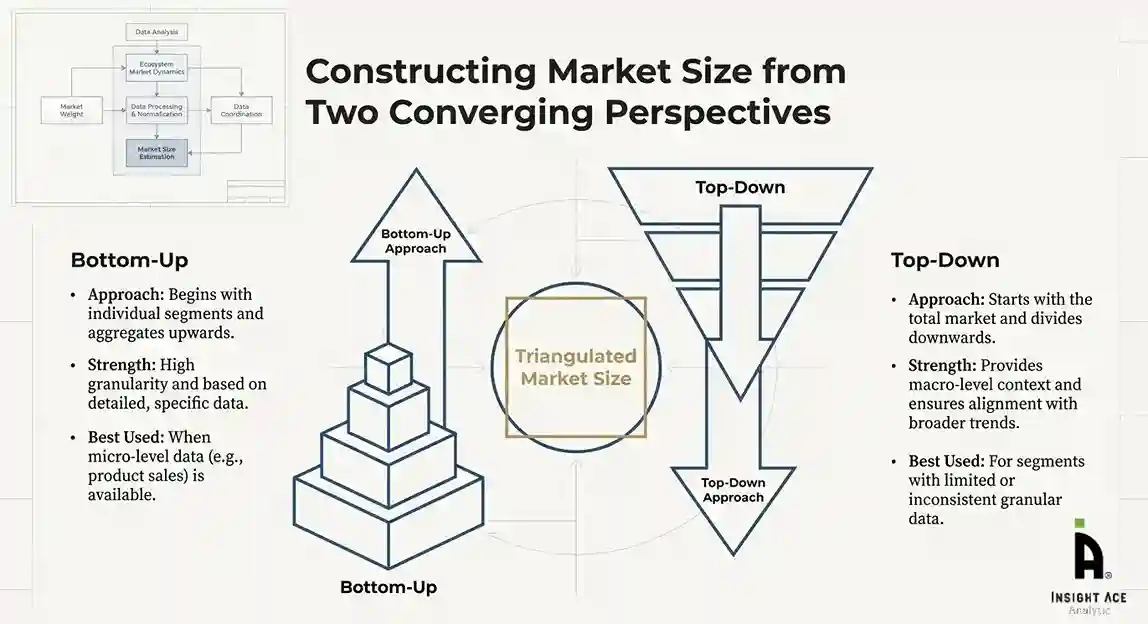
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
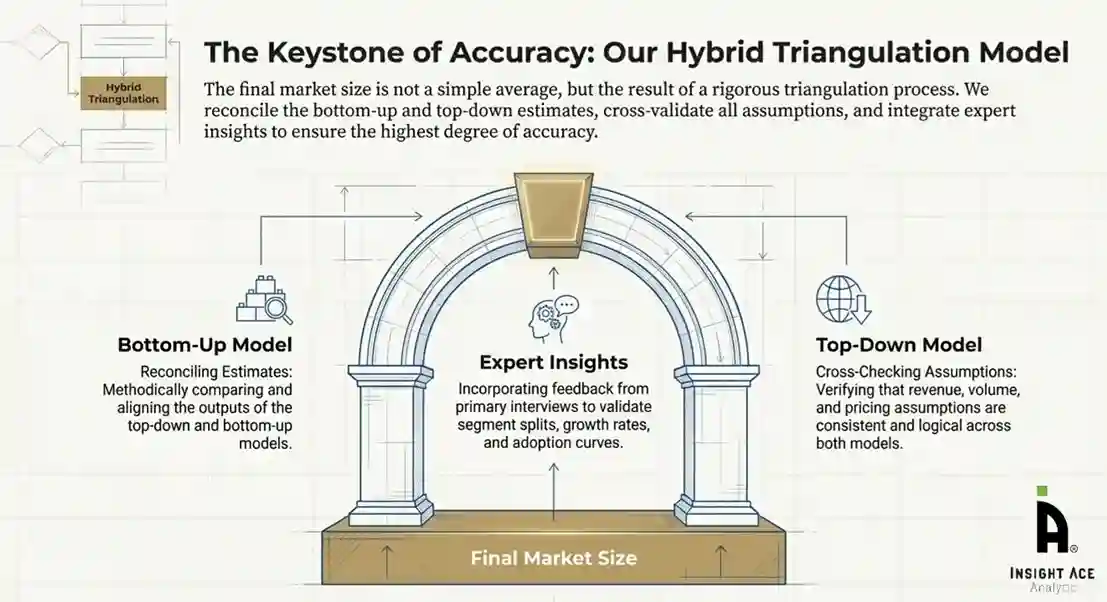
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
Knee Osteoarthritis Market Size is valued at USD 7.88 Bn in 2025 and is predicted to reach USD 24.48 Bn by the year 2035
The Knee Osteoarthritis Market is expected to grow at a 12.2% CAGR during the forecast period for 2026 to 2035
Pfizer Inc., Eli Lilly and Company, Sanofi, Bayer AG, GSK plc, Novartis AG, AbbVie Inc., Merck & Co., Inc., Johnson & Johnson, Anika Therapeutics, Inc.
Knee Osteoarthritis Market is segmented into Drug Type, Route of Administration, Distribution Channel and Other.
North America region is leading the Knee Osteoarthritis Market.