Non-GLP-1 Self-Injection Devices Market Size, Trend, Revenue Report 2026 to 2035
Market Segmentation:
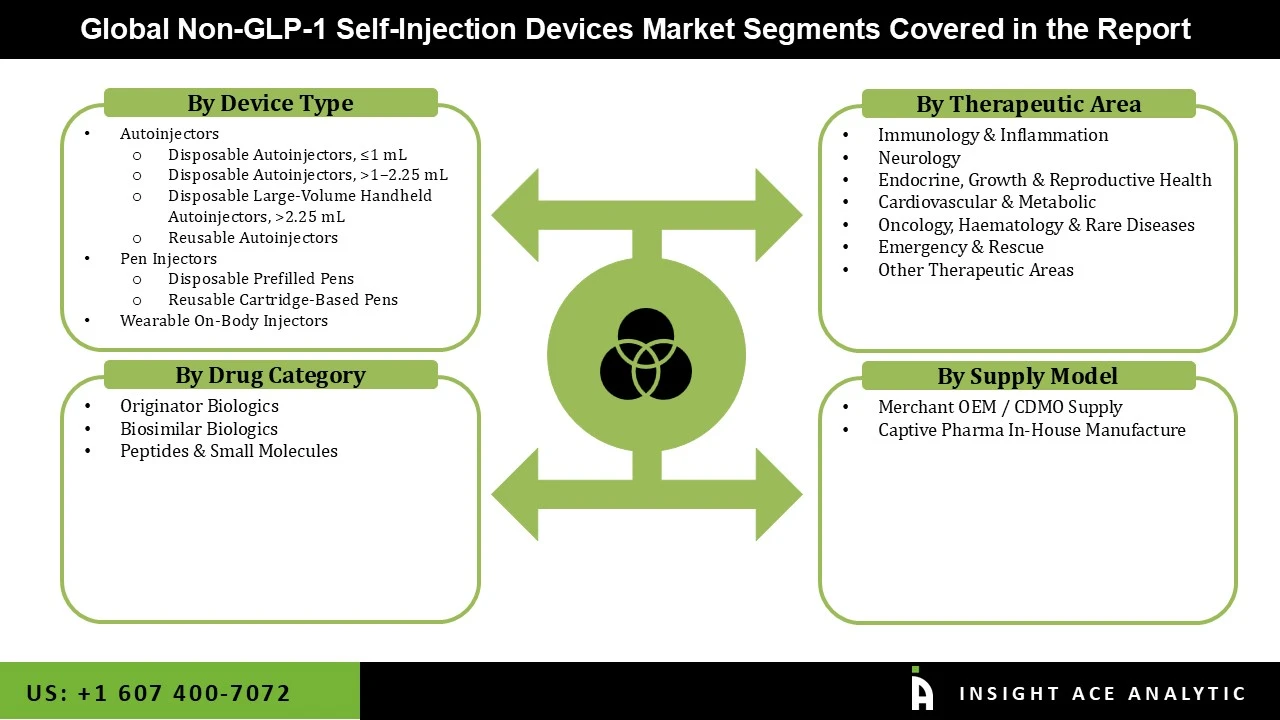
Non-GLP-1 Self-Injection Devices Market by Device Type -
• Autoinjectors
o Disposable Autoinjectors (≤1 mL)
o Disposable Autoinjectors (>1–2.25 mL)
o Disposable Large-Volume Handheld Autoinjectors (>2.25 mL)
o Reusable Autoinjectors
• Pen Injectors
o Disposable Prefilled Pens
o Reusable Cartridge-Based Pens
• Wearable On-Body Injectors
Non-GLP-1 Self-Injection Devices Market by Therapeutic Areas -
• Immunology & Inflammation
• Neurology
• Endocrine, Growth & Reproductive Health
• Cardiovascular & Metabolic
• Oncology, Haematology & Rare Diseases
• Emergency & Rescue
• Other Therapeutic Areas
Non-GLP-1 Self-Injection Devices Market by Drug Category -
• Originator Biologics
• Biosimilar Biologics
• Peptides & Small Molecules
Non-GLP-1 Self-Injection Devices Market by Supply Model -
• Merchant OEM / CDMO Supply
• Captive Pharma In-House Manufacturing
Non-GLP-1 Self-Injection Devices Market by Region-
North America-
• The US
• Canada
• Mexico
Europe-
• Germany
• The UK
• France
• Italy
• Spain
• Rest of Europe
Asia-Pacific-
• China
• Japan
• India
• South Korea
• South East Asia
• Rest of Asia Pacific
Latin America-
• Brazil
• Argentina
• Rest of Latin America
Middle East & Africa-
• GCC Countries
• South Africa
• Rest of Middle East and Africa
Chapter 1. Methodology and Scope
1.1. Research Methodology
1.2. Research Scope & Assumptions
Chapter 2. Executive Summary
Chapter 3. Global Non-GLP-1 Self-Injection Devices Market Snapshot
Chapter 4. Global Non-GLP-1 Self-Injection Devices Market Variables, Trends & Scope
4.1. Market Segmentation & Scope
4.2. Market Drivers
4.3. Market Challenges
4.4. Market Trends
4.5. Regulatory and Product Safety Landscape
4.6. Porter’s Five Forces Analysis
4.7. Incremental Opportunity Analysis (US$ Mn), 2025–2035
4.8. Market Penetration & Growth Prospect Mapping (US$ Mn), 2026–2035
4.9. Competitive Landscape & Market Share Analysis, 2026
4.10. Impact of Biologic Drug Pipeline Expansion, Self-Administration Adoption, Device Innovation, and Pharmaceutical Outsourcing on the Non-GLP-1 Self-Injection Devices Market
Chapter 5. Non-GLP-1 Self-Injection Devices Market Segmentation: By Device Type
5.1. Market Share, 2025 & 2035
5.2. Market Size (US$ Mn), 2022–2035
5.2.1. Autoinjectors
5.2.1.1. Disposable Autoinjectors, ≤1 mL
5.2.1.2. Disposable Autoinjectors, >1–2.25 mL
5.2.1.3. Disposable Large-Volume Handheld Autoinjectors, >2.25 mL
5.2.1.4. Reusable Autoinjectors
5.2.2. Pen Injectors
5.2.2.1. Disposable Prefilled Pens
5.2.2.2. Reusable Cartridge-Based Pens
5.2.3. Wearable On-Body Injectors
Chapter 6. Non-GLP-1 Self-Injection Devices Market Segmentation: By Therapeutic Area
6.1. Market Share, 2025 & 2035
6.2. Market Size (US$ Mn), 2022–2035
6.2.1. Immunology & Inflammation
6.2.2. Neurology
6.2.3. Endocrine, Growth & Reproductive Health
6.2.4. Cardiovascular & Metabolic
6.2.5. Oncology, Haematology & Rare Diseases
6.2.6. Emergency & Rescue
6.2.7. Other Therapeutic Areas
Chapter 7. Non-GLP-1 Self-Injection Devices Market Segmentation: By Drug Category
7.1. Market Share, 2025 & 2035
7.2. Market Size (US$ Mn), 2022–2035
7.2.1. Originator Biologics
7.2.2. Biosimilar Biologics
7.2.3. Peptides & Small Molecules
Chapter 8. Non-GLP-1 Self-Injection Devices Market Segmentation: By Supply Model
8.1. Market Share, 2025 & 2035
8.2. Market Size (US$ Mn), 2022–2035
8.2.1. Merchant OEM / CDMO Supply
8.2.2. Captive Pharma In-House Manufacture
Chapter 9. Regional Non-GLP-1 Self-Injection Devices Market Estimates & Trend Analysis
9.1. Global Market Regional Snapshot, 2025 & 2035
9.2. North America
9.2.1. Market Revenue by Country (U.S., Canada, Mexico), 2022–2035
9.2.2. North America Non-GLP-1 Self-Injection Devices Market Revenue by Device Type, 2022–2035
9.2.3. North America Non-GLP-1 Self-Injection Devices Market Revenue by Therapeutic Area, 2022–2035
9.2.4. North America Non-GLP-1 Self-Injection Devices Market Revenue by Drug Category, 2022–2035
9.2.5. North America Non-GLP-1 Self-Injection Devices Market Revenue by Supply Model, 2022–2035
9.3. Europe
9.3.1. Market Revenue by Country, 2022–2035
9.3.2. Europe Non-GLP-1 Self-Injection Devices Market Revenue by Device Type, 2022–2035
9.3.3. Europe Non-GLP-1 Self-Injection Devices Market Revenue by Therapeutic Area, 2022–2035
9.3.4. Europe Non-GLP-1 Self-Injection Devices Market Revenue by Drug Category, 2022–2035
9.3.5. Europe Non-GLP-1 Self-Injection Devices Market Revenue by Supply Model, 2022–2035
9.4. Asia Pacific
9.4.1. Market Revenue by Country, 2022–2035
9.4.2. Asia Pacific Non-GLP-1 Self-Injection Devices Market Revenue by Device Type, 2022–2035
9.4.3. Asia Pacific Non-GLP-1 Self-Injection Devices Market Revenue by Therapeutic Area, 2022–2035
9.4.4. Asia Pacific Non-GLP-1 Self-Injection Devices Market Revenue by Drug Category, 2022–2035
9.4.5. Asia Pacific Non-GLP-1 Self-Injection Devices Market Revenue by Supply Model, 2022–2035
9.5. Latin America
9.5.1. Market Revenue by Country, 2022–2035
9.5.2. Latin America Non-GLP-1 Self-Injection Devices Market Revenue by Device Type, 2022–2035
9.5.3. Latin America Non-GLP-1 Self-Injection Devices Market Revenue by Therapeutic Area, 2022–2035
9.5.4. Latin America Non-GLP-1 Self-Injection Devices Market Revenue by Drug Category, 2022–2035
9.5.5. Latin America Non-GLP-1 Self-Injection Devices Market Revenue by Supply Model, 2022–2035
9.6. Middle East & Africa
9.6.1. Market Revenue by Country, 2022–2035
9.6.2. Middle East & Africa Non-GLP-1 Self-Injection Devices Market Revenue by Device Type, 2022–2035
9.6.3. Middle East & Africa Non-GLP-1 Self-Injection Devices Market Revenue by Therapeutic Area, 2022–2035
9.6.4. Middle East & Africa Non-GLP-1 Self-Injection Devices Market Revenue by Drug Category, 2022–2035
9.6.5. Middle East & Africa Non-GLP-1 Self-Injection Devices Market Revenue by Supply Model, 2022–2035
Chapter 10. Competitive Landscape
10.1. Key Strategic Developments (Partnerships, Acquisitions, Product Launches, Capacity Expansions, and Technology Investments)
10.2. Market Share Analysis, 2026
10.3. Company Profiles
10.3.1. Self-Injection Device Developers & Manufacturers
10.3.1.1. SHL Medical AG
10.3.1.2. Ypsomed AG
10.3.1.3. Becton, Dickinson and Company
10.3.1.4. West Pharmaceutical Services, Inc.
10.3.1.5. Owen Mumford Ltd (embecta Corp)
10.3.1.6. Gerresheimer AG
10.3.1.7. Nemera
10.3.1.8. Haselmeier GmbH (medmix AG)
10.3.1.9. Kindeva Drug Delivery
10.3.1.10. Enable Injections, Inc.
10.3.1.11. Stevanato Group S.p.A.
10.3.1.12. Phillips-Medisize (Molex LLC)
10.3.1.13. Jabil Inc.
10.3.1.14. LTS Lohmann Therapie-Systeme AG
10.3.1.15. Elcam Medical (E3D)
10.3.1.16. Terumo Corporation
10.3.1.17. Crossject SA
10.3.1.18. Portal Instruments, Inc.
10.3.1.19. Sonceboz SA
10.3.1.20. Subcuject ApS
10.3.1.21. Congruence Medical Solutions, LLC
10.3.1.22. Oval Medical Technologies Ltd (SMC Ltd)
10.3.1.23. Shaily Engineering Plastics Ltd
10.3.1.24. SQ Innovation AG
10.3.1.25. TxSphere LLC
10.3.1.26. Synolus Medical
10.3.1.27. PharmaJet, Inc.
10.3.1.28. Credence MedSystems, Inc.
10.3.1.29. Duoject Medical Systems Inc.
10.3.1.30. Nipro Corporation
10.3.1.31. Weigao Group
10.3.1.32. Eitan Medical Ltd
10.3.2. Pharmaceutical Companies & Captive Device Manufacturers
10.3.2.1. Halozyme Therapeutics, Inc.
10.3.2.2. Insulet Corporation
10.3.2.3. Eli Lilly and Company
10.3.2.4. Novo Nordisk A/S
10.3.2.5. Kaleo, Inc.
10.3.2.6. AbbVie Inc.
10.3.2.7. Merck KGaA
10.3.2.8. Viatris Inc.
10.3.2.9. ALK-Abelló A/S
10.3.2.10. Amneal Pharmaceuticals, Inc.
10.3.2.11. Teva Pharmaceutical Industries Ltd
10.3.2.12. ARS Pharmaceuticals, Inc.
10.3.3. Component Suppliers & Manufacturing Partners
10.3.3.1. AptarGroup, Inc.
10.3.3.2. Recipharm AB
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
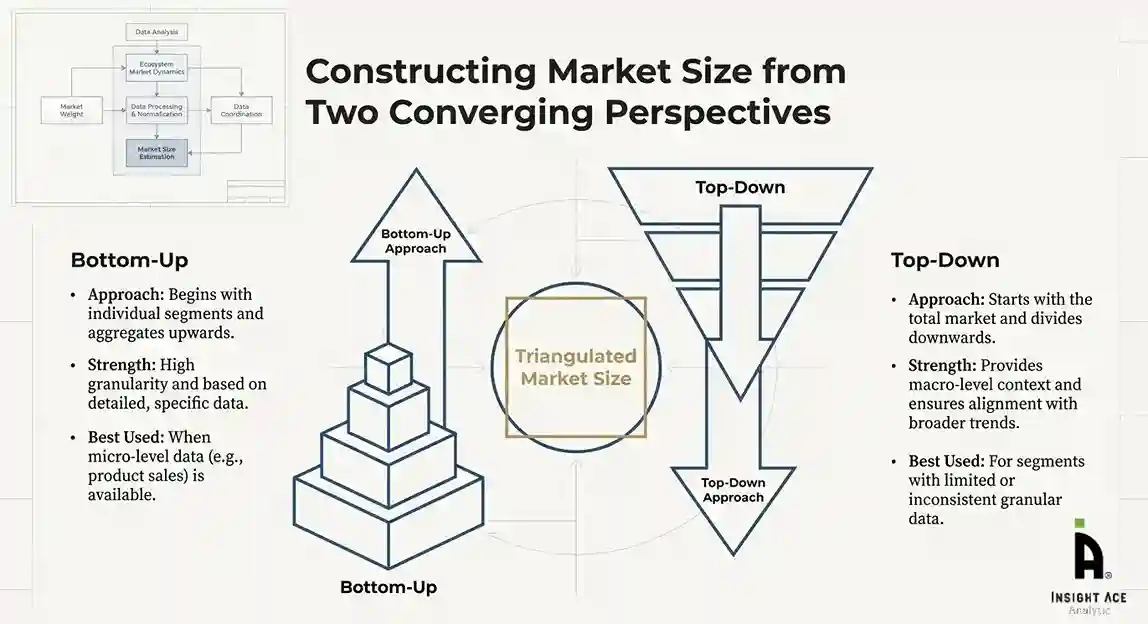
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
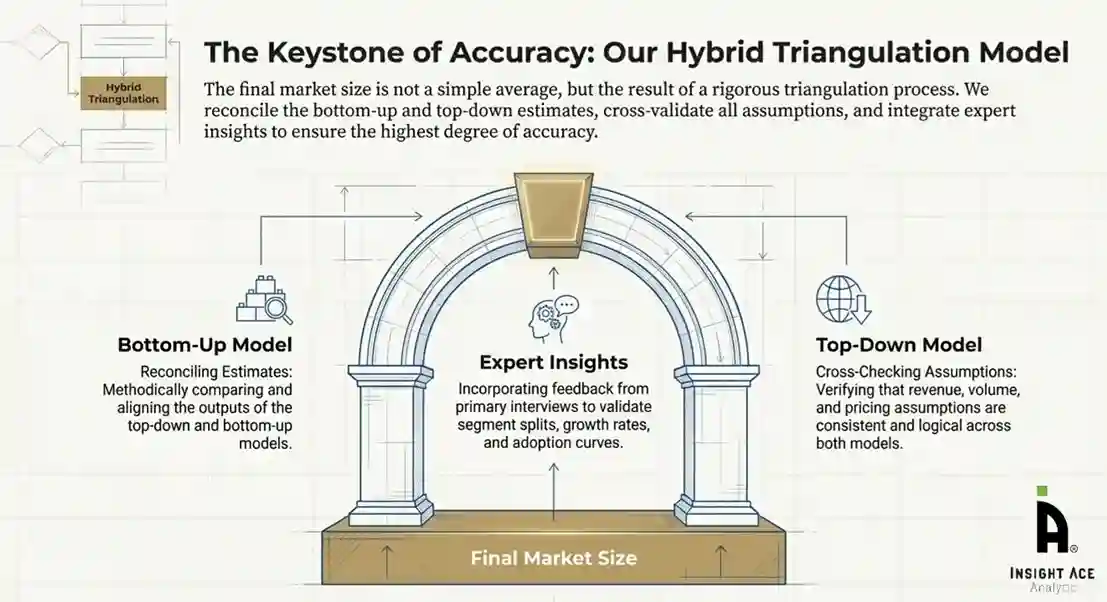
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
Non-GLP-1 Self-Injection Devices Market is predicted to grow at an 8.8% CAGR during the forecast period for 2026 to 2035.
SHL Medical AG, Ypsomed AG, Becton, Dickinson and Company, West Pharmaceutical Services, Inc., Owen Mumford Ltd (embecta Corp), Gerresheimer AG, Nemera, Haselmeier GmbH (medmix AG), Kindeva Drug Delivery, Enable Injections, Inc., Stevanato Group S.p.A., Phillips-Medisize (Molex LLC), Jabil Inc., LTS Lohmann Therapie-Systeme AG, Elcam Medical (E3D), Terumo Corporation, Crossject SA, Portal Instruments, Inc., Sonceboz SA, Subcuject ApS, Congruence Medical Solutions, LLC, Oval Medical Technologies Ltd (SMC Ltd), Shaily Engineering Plastics Ltd, SQ Innovation AG, TxSphere LLC, Synolus Medical, PharmaJet, Inc., Credence MedSystems, Inc., Duoject Medical Systems Inc., Nipro Corporation, Weigao Group, Eitan Medical Ltd., Halozyme Therapeutics, Inc., Insulet Corporation, Eli Lilly and Company, Novo Nordisk A/S, Kaleo, Inc., AbbVie Inc., Merck KGaA, Viatris Inc., ALK-Abelló A/S, Amneal Pharmaceuticals, Inc., Teva Pharmaceutical Industries Ltd, ARS Pharmaceuticals, Inc.
Non-GLP-1 Self-Injection Devices Market is segmented into Device Type, Therapeutic Area, Drug Category, Supply Model and By Region
North America region is leading the Non-GLP-1 Self-Injection Devices Market.