Non-GLP-1 Self-Injection Devices Market Size, Trend, Revenue Report 2026 to 2035
What is Non-GLP-1 Self-Injection Devices Market Size?
Non-GLP-1 Self-Injection Devices Market is predicted to grow at an 8.8% CAGR during the forecast period for 2026 to 2035.
Non-GLP-1 Self-Injection Devices Market Size, Share & Trends Analysis Distribution by Device Type (Autoinjectors, Disposable Autoinjectors (≤1 mL), Disposable Autoinjectors (>1–2.25 mL), Disposable Large-Volume Handheld Autoinjectors (>2.25 mL), Reusable Autoinjectors, Pen Injectors, Disposable Prefilled Pens, Reusable Cartridge-Based Pens, Wearable On-Body Injectors), by Therapeutic Area (Immunology & Inflammation, Neurology, Endocrine, Growth & Reproductive Health, Cardiovascular & Metabolic, Oncology, Haematology & Rare Diseases, Emergency & Rescue, Other Therapeutic Areas), by Drug Category (Originator Biologics, Biosimilar Biologics, Peptides & Small Molecules), by Supply Model (Merchant OEM / CDMO Supply, Captive Pharma In-House Manufacturing) and Segment Forecasts, 2026 to 2035
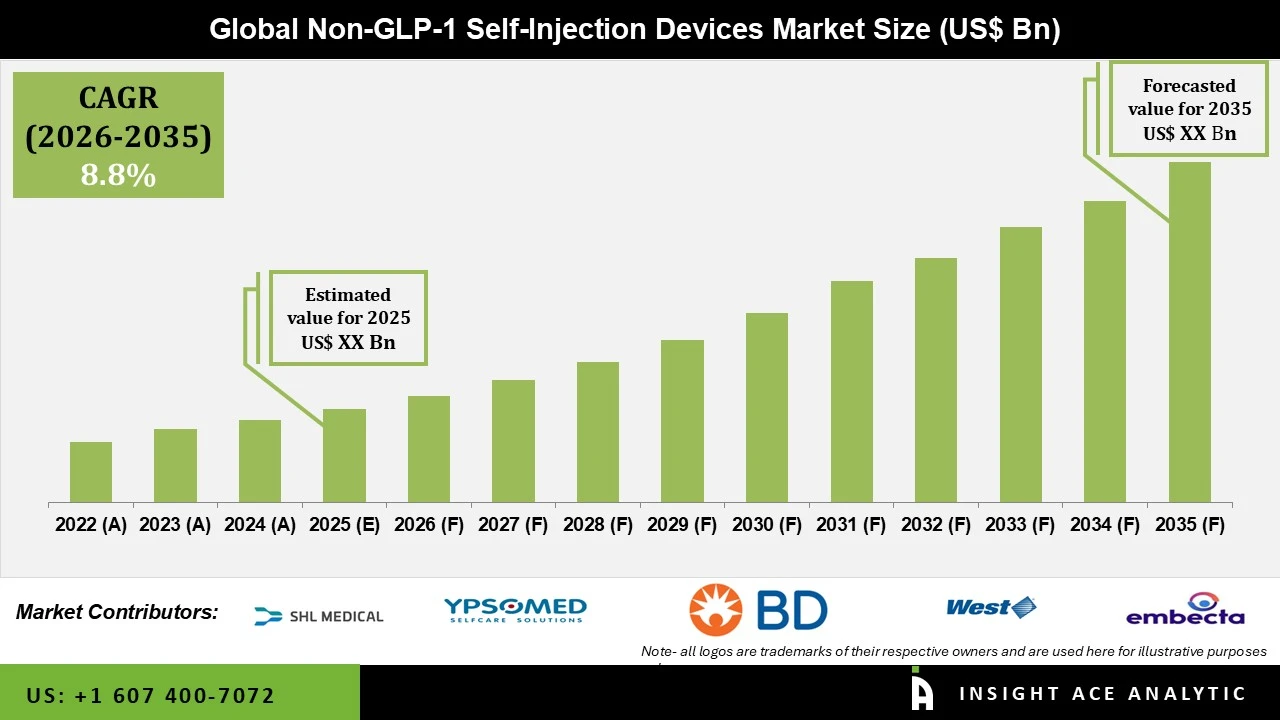
Non-GLP-1 self-injection devices are drug-delivery systems designed to enable patients to administer injectable medications independently, without requiring routine assistance from healthcare professionals. These devices support the administration of a broad range of therapies outside the GLP-1 drug class, including biologics, biosimilars, peptides, and small-molecule medicines used across multiple therapeutic areas. By combining controlled drug delivery with simplified handling and dosing mechanisms, self-injection systems are designed to improve administration convenience and support the growing use of injectable therapies in home and outpatient care settings.
The technology landscape includes autoinjectors, pen injectors, and wearable on-body injectors, available in disposable and reusable configurations. Depending on the drug formulation, dose volume, administration frequency, and treatment requirements, devices may incorporate prefilled syringes or cartridges, dose-setting mechanisms, automatic needle insertion, needle shielding, controlled injection speeds, and other user-assistance features. Conventional systems are generally designed for lower-volume administration, while advanced large-volume and wearable systems are increasingly being developed to accommodate therapies that require higher doses or longer delivery times.
The non-GLP-1 self-injection devices market encompasses the development, design, manufacturing, commercialization, and supply of injection systems intended for self-administration across a broad range of therapeutic applications. These include immunology and inflammation, neurology, endocrine and reproductive health, cardiovascular and metabolic diseases, oncology, hematology, and rare diseases, among other areas. Device selection and configuration depend on factors such as drug viscosity, dose volume, formulation characteristics, injection duration, frequency of administration, and patient usability requirements.
The market ecosystem includes drug-delivery device manufacturers, pharmaceutical and biotechnology companies, component suppliers, contract development and manufacturing organizations (CDMOs), and specialized technology providers involved in developing and integrating drug-device combinations. Commercial models encompass both merchant device supply to pharmaceutical companies and captive or internally developed injection platforms. Collaboration between drug developers and device manufacturers is particularly important for ensuring compatibility between injectable formulations and delivery systems while meeting functional, usability, and regulatory requirements.
The market ranges from established pen injectors and autoinjectors to advanced large-volume handheld systems and wearable on-body injectors designed for more complex injectable therapies. Advances in device miniaturization, automation, human-factor engineering, connectivity, and controlled drug delivery are expanding the capabilities of self-injection systems. These developments are supporting the broader shift toward patient-administered therapies and enabling more injectable treatments to be delivered in home, ambulatory, and other non-hospital settings.
Competitive Landscape
Which are the Leading Players in the Non-GLP-1 Self-Injection Devices Market ?
• SHL Medical AG
• Ypsomed AG
• Becton, Dickinson and Company
• West Pharmaceutical Services, Inc.
• Owen Mumford Ltd (embecta Corp)
• Gerresheimer AG
• Nemera
• Haselmeier GmbH (medmix AG)
• Kindeva Drug Delivery
• Enable Injections, Inc.
• Stevanato Group S.p.A.
• Phillips-Medisize (Molex LLC)
• Jabil Inc.
• LTS Lohmann Therapie-Systeme AG
• Elcam Medical (E3D)
• Terumo Corporation
• Crossject SA
• Portal Instruments, Inc.
• Sonceboz SA
• Subcuject ApS
• Congruence Medical Solutions, LLC
• Oval Medical Technologies Ltd (SMC Ltd)
• Shaily Engineering Plastics Ltd
• SQ Innovation AG
• TxSphere LLC
• Synolus Medical
• PharmaJet, Inc.
• Credence MedSystems, Inc.
• Duoject Medical Systems Inc.
• Nipro Corporation
• Weigao Group
• Eitan Medical Ltd.
• Halozyme Therapeutics, Inc.
• Insulet Corporation
• Eli Lilly and Company
• Novo Nordisk A/S
• Kaleo, Inc.
• AbVie Inc.
• Merck KGaA
• Viatris Inc.
• ALK-Abelló A/S
• Amneal Pharmaceuticals, Inc.
• Teva Pharmaceutical Industries Ltd
• ARS Pharmaceuticals, Inc.
• AptarGroup, Inc.
• Recipharm AB
Market Dynamics
Driver
Growing Adoption of Self-Administration and Home-Based Drug Delivery
More people now prefer to self-administer injectable medications, which is boosting demand for non-GLP-1 self-injection devices in many treatment areas. Patients who need long-term care for conditions like autoimmune disorders, neurological issues, hormonal problems, and other chronic diseases are choosing to manage their medications at home. This helps them avoid frequent hospital visits and reduces their reliance on healthcare professionals. Devices such as autoinjectors, pen injectors, and wearable injectors make drug delivery easier, more accurate, and more comfortable for patients. As more biologics and other injectable treatments are developed that require regular use, pharmaceutical companies are adding advanced self-injection systems to their drug delivery plans. All these trends are leading to more investment in device innovation, manufacturing, and partnerships between pharmaceutical and device companies.
Restrain/Challenge
Complexity of Device Development and Compatibility with Different Drug Formulations
One of the main challenges in the non-GLP-1 self-injection devices market is making sure delivery systems work with different drug types, thicknesses, injection amounts, and ways of giving the medication. Biologics and other complex injectable drugs often need special device designs to keep the drug stable, deliver the right dose, and work well. When drugs are thick or need to be given in large amounts, more advanced injection technology is needed, which adds to engineering and manufacturing difficulties. Also, creating and testing combination products must meet strict regulations, involve a lot of user testing, and follow careful quality checks. These issues can raise development costs, slow down product launches, and make it harder for smaller companies to bring new self-injection devices to market.
Autoinjectors Segment is Expected to Drive the Non-GLP-1 Self-Injection Devices Market
Autoinjectors are expected to make up a large part of the non-GLP-1 self-injection devices market because they are used widely for chronic and specialty treatments. These devices make injections easier by automating steps like inserting the needle and delivering the drug, which makes the process simpler than traditional injections. Autoinjectors come in both disposable and reusable types and can handle different dose sizes, so they work with many kinds of injectable drugs. As more people need biologic treatments for conditions like immune and nerve disorders, drug makers are choosing autoinjectors that are easier for patients to use. Ongoing improvements in how these devices feel, how they work, and their safety features are also helping this segment grow.
Immunology & Inflammation Segment is Expected to Drive the Non-GLP-1 Self-Injection Devices Market
The immunology and inflammation segment is expected to hold a large share of the market because injectable biologics are widely used to treat chronic inflammatory and autoimmune diseases. Conditions like rheumatoid arthritis, psoriasis, and inflammatory bowel disease often need ongoing medication, which increases the need for easy-to-use self-injection devices. Drug companies are adding more prefilled pens and autoinjectors to make treatment easier and help patients stick to their medication plans. As more biologic and biosimilar treatments become available, there is a greater need for injection devices that work with different doses and drug types, which is helping self-injection technology grow in this area.
Why North America Leads the Non-GLP-1 Self-Injection Devices Market?
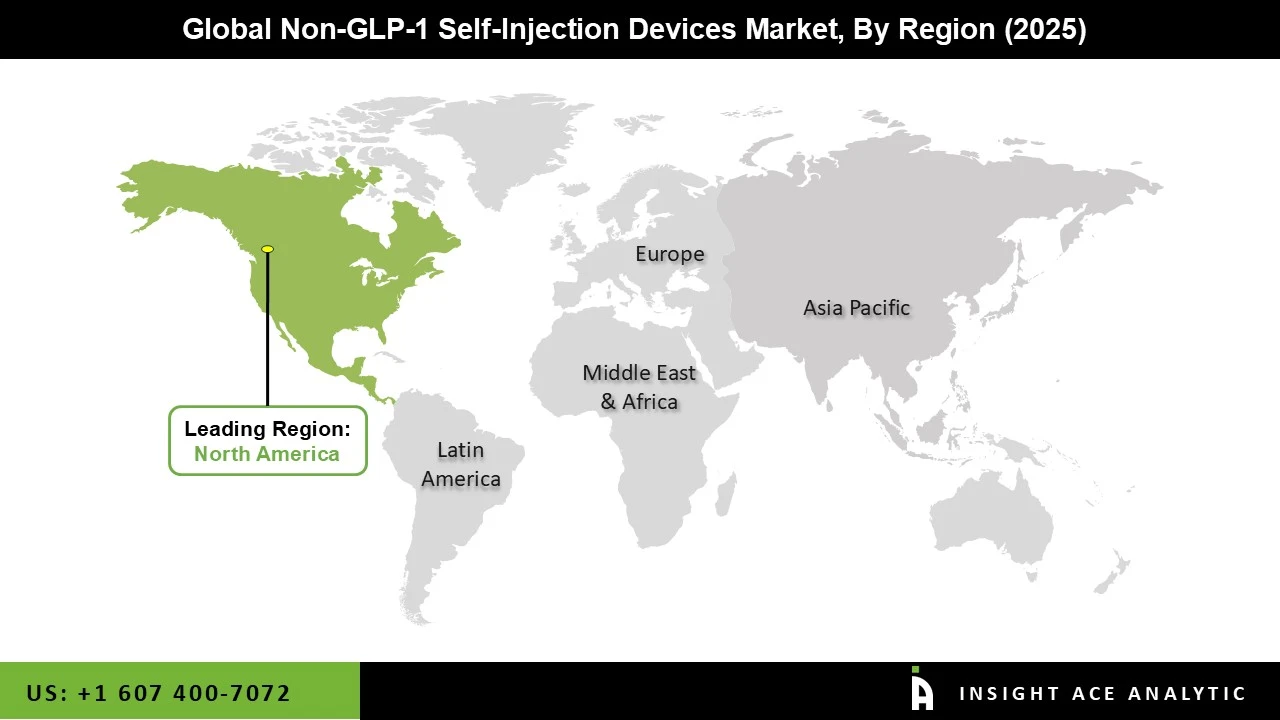
North America is expected to maintain a leading position in the non-GLP-1 self-injection devices market because it has strong pharmaceutical and biotech industries, advanced healthcare systems, and high use of injectable biologic treatments. The region is home to major drug companies and specialised device makers who are investing in new autoinjectors, pen injectors, and wearable injection devices. As more people are diagnosed with chronic and autoimmune diseases, there is a growing need for long-term injectable treatments that can be used at home. The presence of device makers, contract manufacturers, and suppliers also helps drive innovation and large-scale production. Continued investment in biologic drug development, patient-focused delivery methods, and home-based care is helping North America keep its lead in this market.
Key Development
• In May 2026, Enable Injections, Inc. received CE certification for its enFuse On-Body Delivery System for use in combination with Aspaveli (pegcetacoplan), distributed by Sobi. The development represents an important milestone for wearable drug delivery technologies used in the treatment of rare diseases and supports the adoption of patient-administered large-volume subcutaneous therapies.
Non-GLP-1 Self-Injection Devices Market Report Scope:
| Report Attribute | Specifications |
| Market size value in 2025 | USD XX Bn |
| Revenue forecast in 2035 | USD XX Bn |
| Growth Rate CAGR | CAGR of 8.8% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2022 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | Device Type, Therapeutic Area, Drug Category, Supply Model and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; France; Italy; Spain; South Korea; Southeast Asia |
| Competitive Landscape | SHL Medical AG, Ypsomed AG, Becton, Dickinson and Company, West Pharmaceutical Services, Inc., Owen Mumford Ltd (embecta Corp), Gerresheimer AG, Nemera, Haselmeier GmbH (medmix AG), Kindeva Drug Delivery, Enable Injections, Inc., Stevanato Group S.p.A., Phillips-Medisize (Molex LLC), Jabil Inc., LTS Lohmann Therapie-Systeme AG, Elcam Medical (E3D), Terumo Corporation, Crossject SA, Portal Instruments, Inc., Sonceboz SA, Subcuject ApS, Congruence Medical Solutions, LLC, Oval Medical Technologies Ltd (SMC Ltd), Shaily Engineering Plastics Ltd, SQ Innovation AG, TxSphere LLC, Synolus Medical, PharmaJet, Inc., Credence MedSystems, Inc., Duoject Medical Systems Inc., Nipro Corporation, Weigao Group, Eitan Medical Ltd., Halozyme Therapeutics, Inc., Insulet Corporation, Eli Lilly and Company, Novo Nordisk A/S, Kaleo, Inc., AbbVie Inc., Merck KGaA, Viatris Inc., ALK-Abelló A/S, Amneal Pharmaceuticals, Inc., Teva Pharmaceutical Industries Ltd, ARS Pharmaceuticals, Inc. AptarGroup, Inc., Recipharm AB. |
| Customization Scope | Free customization report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customized to your particular study requirements. |
Market Segmentation:
Non-GLP-1 Self-Injection Devices Market by Device Type -
• Autoinjectors
o Disposable Autoinjectors (≤1 mL)
o Disposable Autoinjectors (>1–2.25 mL)
o Disposable Large-Volume Handheld Autoinjectors (>2.25 mL)
o Reusable Autoinjectors
• Pen Injectors
o Disposable Prefilled Pens
o Reusable Cartridge-Based Pens
• Wearable On-Body Injectors
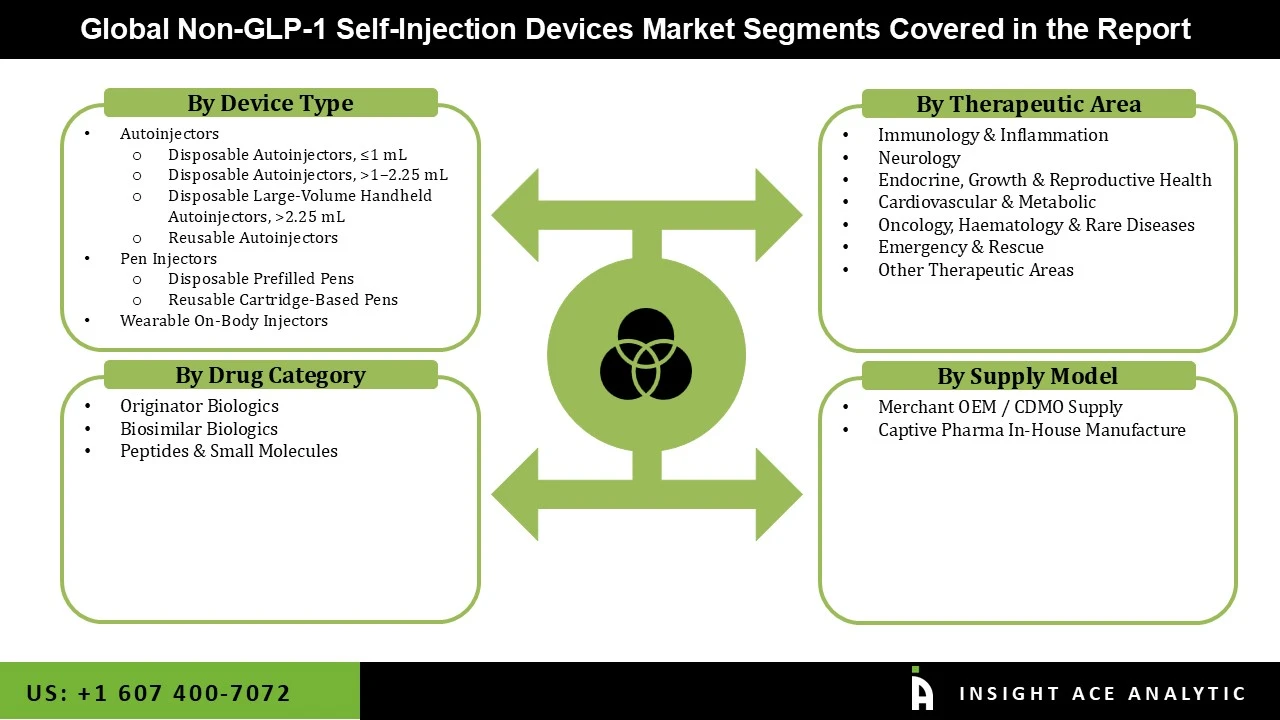
Non-GLP-1 Self-Injection Devices Market by Therapeutic Areas -
• Immunology & Inflammation
• Neurology
• Endocrine, Growth & Reproductive Health
• Cardiovascular & Metabolic
• Oncology, Haematology & Rare Diseases
• Emergency & Rescue
• Other Therapeutic Areas
Non-GLP-1 Self-Injection Devices Market by Drug Category -
• Originator Biologics
• Biosimilar Biologics
• Peptides & Small Molecules
Non-GLP-1 Self-Injection Devices Market by Supply Model -
• Merchant OEM / CDMO Supply
• Captive Pharma In-House Manufacturing
Non-GLP-1 Self-Injection Devices Market by Region-
North America-
• The US
• Canada
• Mexico
Europe-
• Germany
• The UK
• France
• Italy
• Spain
• Rest of Europe
Asia-Pacific-
• China
• Japan
• India
• South Korea
• South East Asia
• Rest of Asia Pacific
Latin America-
• Brazil
• Argentina
• Rest of Latin America
Middle East & Africa-
• GCC Countries
• South Africa
• Rest of Middle East and Africa
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
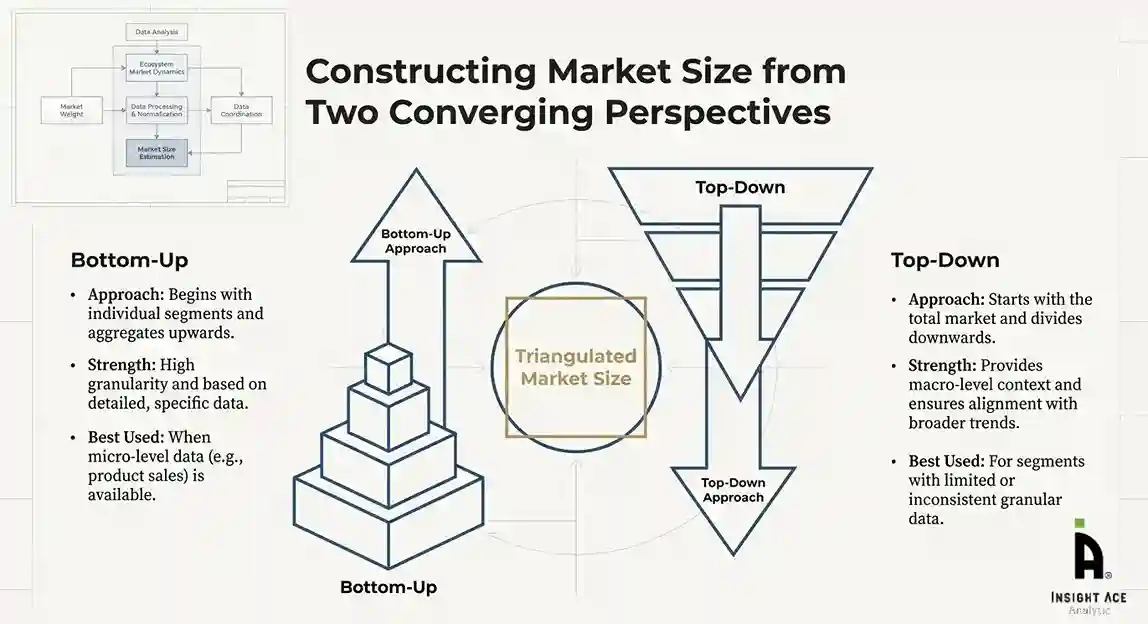
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
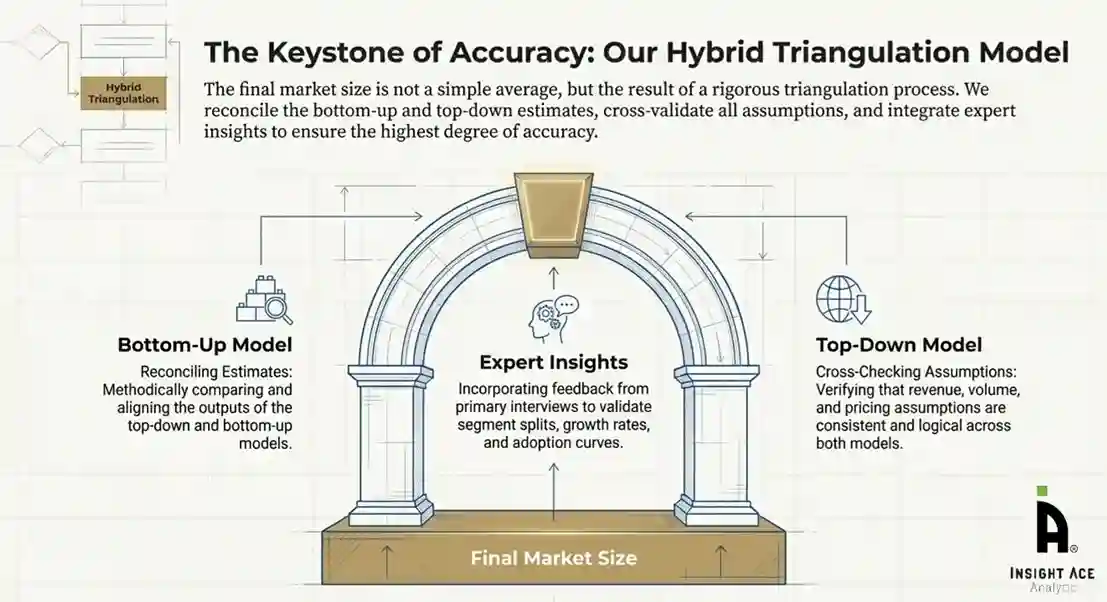
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
Non-GLP-1 Self-Injection Devices Market is predicted to grow at an 8.8% CAGR during the forecast period for 2026 to 2035.
SHL Medical AG, Ypsomed AG, Becton, Dickinson and Company, West Pharmaceutical Services, Inc., Owen Mumford Ltd (embecta Corp), Gerresheimer AG, Nemera, Haselmeier GmbH (medmix AG), Kindeva Drug Delivery, Enable Injections, Inc., Stevanato Group S.p.A., Phillips-Medisize (Molex LLC), Jabil Inc., LTS Lohmann Therapie-Systeme AG, Elcam Medical (E3D), Terumo Corporation, Crossject SA, Portal Instruments, Inc., Sonceboz SA, Subcuject ApS, Congruence Medical Solutions, LLC, Oval Medical Technologies Ltd (SMC Ltd), Shaily Engineering Plastics Ltd, SQ Innovation AG, TxSphere LLC, Synolus Medical, PharmaJet, Inc., Credence MedSystems, Inc., Duoject Medical Systems Inc., Nipro Corporation, Weigao Group, Eitan Medical Ltd., Halozyme Therapeutics, Inc., Insulet Corporation, Eli Lilly and Company, Novo Nordisk A/S, Kaleo, Inc., AbbVie Inc., Merck KGaA, Viatris Inc., ALK-Abelló A/S, Amneal Pharmaceuticals, Inc., Teva Pharmaceutical Industries Ltd, ARS Pharmaceuticals, Inc.
Non-GLP-1 Self-Injection Devices Market is segmented into Device Type, Therapeutic Area, Drug Category, Supply Model and By Region
North America region is leading the Non-GLP-1 Self-Injection Devices Market.