Automated Cell Therapy Manufacturing Platforms Market Size, Trend, Forecast Report 2026 to 2035
What is Automated Cell Therapy Manufacturing Platforms Market Size?
Automated Cell Therapy Manufacturing Platforms Market is estimated tog grow at a 19.5% CAGR during the forecast period for 2026 to 2035.
Automated Cell Therapy Manufacturing Platforms Market Size, Share & Trends Analysis Distribution by Offering (Instruments & Hardware Systems, Consumables, Cassettes & Process Kits, Software & Digital Orchestration, Services), By Platform Architecture (End-to-End Closed / Integrated Platforms, Modular Unit-Operation Instrument Suites, Robotic Orchestration Platforms, Point-of-Care / Decentralised Units, iPSC & Adherent-Cell Automation Systems), By Manufacturing Unit Operation (Cell Isolation & Selection, Activation, Transduction & Gene-Editing, Expansion & Bioreactor Culture, Wash, Concentration & Formulation, Fill–Finish, In-Process Analytics & Quality Control), By Therapy Modality (CAR-T-Cell Therapies, TCR-T & TIL Therapies, Regulatory T-Cell (Treg) Therapies, CAR-NK & NK-Cell Therapies, HSPC & Gene-Modified Stem-Cell Therapies, iPSC-Derived Allogeneic Therapies, Other Modalities (MSC, VST, Exosome & Emerging)), By Therapy Sourcing Model (Autologous Manufacturing, Allogeneic Manufacturing) and Segment Forecasts, 2026 to 2035
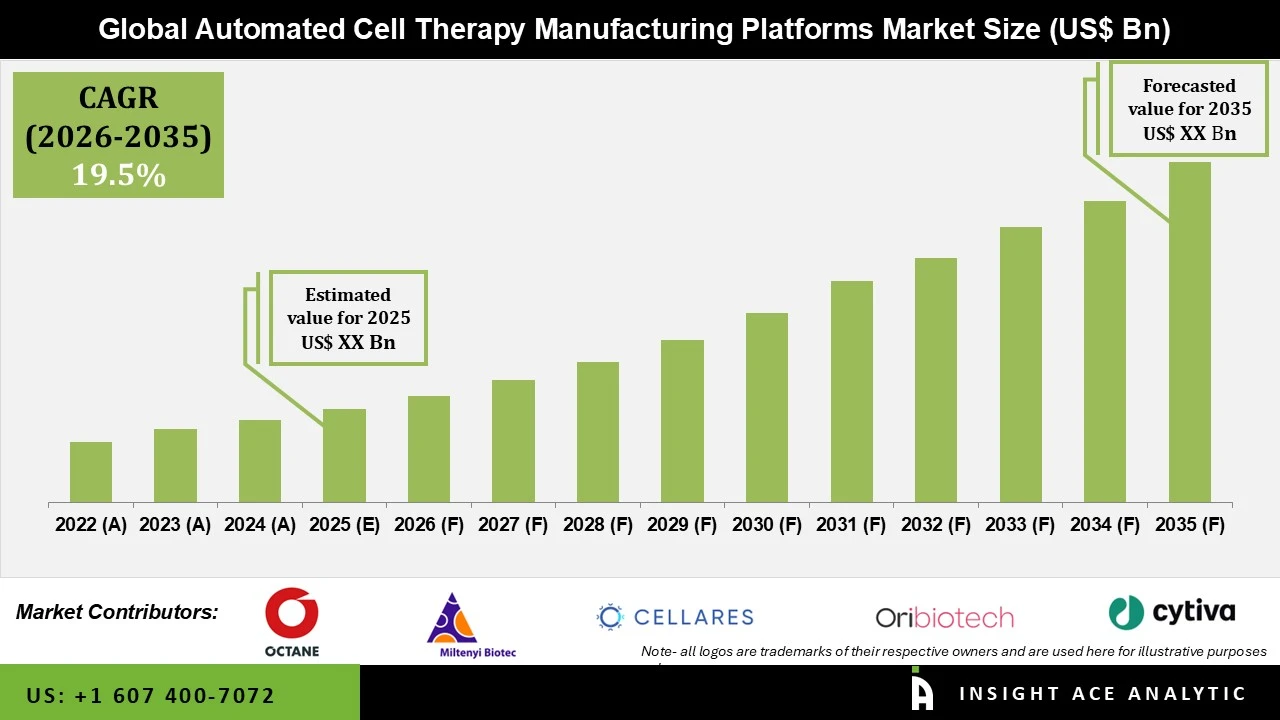
Cell therapy manufacturing is the controlled sequence of processes used to produce therapeutic cells for clinical and commercial application. Key steps typically include cell isolation and selection, activation, genetic modification where required, expansion, washing, formulation and final filling or cryopreservation. These operations must maintain cell viability, identity, purity and consistency while meeting strict quality and regulatory requirements. Processes can be performed on individual instruments or within integrated systems that combine multiple steps into a closed or semi-closed workflow.
The automated cell therapy manufacturing platforms market covers the instruments, integrated systems, robotic solutions, single-use consumables, software and related services that automate these workflows. Automation aims to reduce manual handling, improve process consistency, lower contamination risk and support scalable, compliant production.
These platforms support a range of cell therapy types, including CAR-T, TCR-T, tumour-infiltrating lymphocytes (TIL), regulatory T cells (Treg), natural killer (NK) cells and stem cell therapies. They are used for both autologous manufacturing, which processes a patient’s own cells, and allogeneic manufacturing, which uses donor-derived or off-the-shelf cell products. Main users include biopharmaceutical and biotechnology companies, contract development and manufacturing organisations (CDMOs), and academic or hospital-based manufacturing centres.
The market includes end-to-end closed manufacturing systems, modular platforms focused on specific process steps, robotic automation solutions, and specialised systems for induced pluripotent stem cell (iPSC) and adherent cell processing. Rising clinical and commercial demand for cell therapies continues to increase the need for reliable, scalable and regulatory-ready automated manufacturing technologies.
Competitive Landscape
Which are the Leading Players in the Automated Cell Therapy Manufacturing Platforms Market?
• Octane Medical Group
• Miltenyi Biotec
• Cellares
• Ori Biotech
• Cytiva
• Terumo BCT
• Thermo Fisher Scientific
• Sartorius
• Wilson Wolf / ScaleReady
• Adva Biotechnology
• Multiply Labs
• Fresenius Kabi
• Cellular Origins
• MaxCyte
• Cellino Biotech
• Applied Cells
• Sinfonia Technology
• Celltrio
• Cellistic
• CellFE
Market Dynamics
Driver
Increasing Demand for Cell and Gene Therapies
The clinical development and commercialisation of cell and gene therapies (particularly CAR-T, TCR-T, TIL and stem cell therapies) is driving the need for automated cell therapy manufacturing platforms. The therapies themselves are inherently complex, multi-stage processes involving cell isolation, activation, genetic modification, expansion and formulation. As more cell therapies move through the clinic and into commercialisation, there is a growing requirement for automated and integrated manufacturing platforms to provide a standardised manufacturing process, ensure product quality and enable the transition from small clinical scale manufacturing to larger commercial scale manufacturing.
Restrain/Challenge
High Cost of Automated Manufacturing Platforms
The high cost of developing, implementing and running automated cell therapy manufacturing platforms is a significant barrier to the market. The platforms themselves are expensive to build and require specialist instrumentation, robotics, single use consumables, software integration and GMP infrastructure to support the complex cell processing operations. There are also significant costs associated with platform installation, process validation, regulatory compliance and training of personnel. These costs can be prohibitive and will be a major barrier to adoption for smaller and emerging biotechs, academic institutions and facilities with very limited manufacturing budgets. This in turn will likely slow the rate of uptake of automated cell therapy manufacturing.
Cloud / SaaS segment Segment is Expected to Drive the Automated Cell Therapy Manufacturing Platforms Market
Instruments and hardware systems is forecasted to dominate the global automated cell therapy manufacturing platforms market. This market segment encompasses automated end-to-end manufacturing platforms, modular unit operation instruments, and robotic orchestration systems that are used at all key stages in cell processing such as isolation, activation, genetic modification, expansion, washing, and formulation of cells. These systems make up the fundamental hardware of automated cell therapy manufacturing platforms, which, along with their importance in production processes and relatively expensive equipment, is likely to ensure their dominance in the market.
Point-of-Care / Decentralised Units Segment is Growing at the Highest Rate in the Automated Cell Therapy Manufacturing Platforms Market
The point-of-care / decentralised units segment is expected to be the fastest growing in the automated cell therapy manufacturing platforms market. This is underpinned by the continued move towards decentralised manufacturing, particularly in the area of autologous cell therapies (such as CAR-T) where manufacturing at or near the point of care can facilitate the patient specific manufacturing process and reduce the need for centralised manufacturing.
Why North America Led the Automated Cell Therapy Manufacturing Platforms Market?
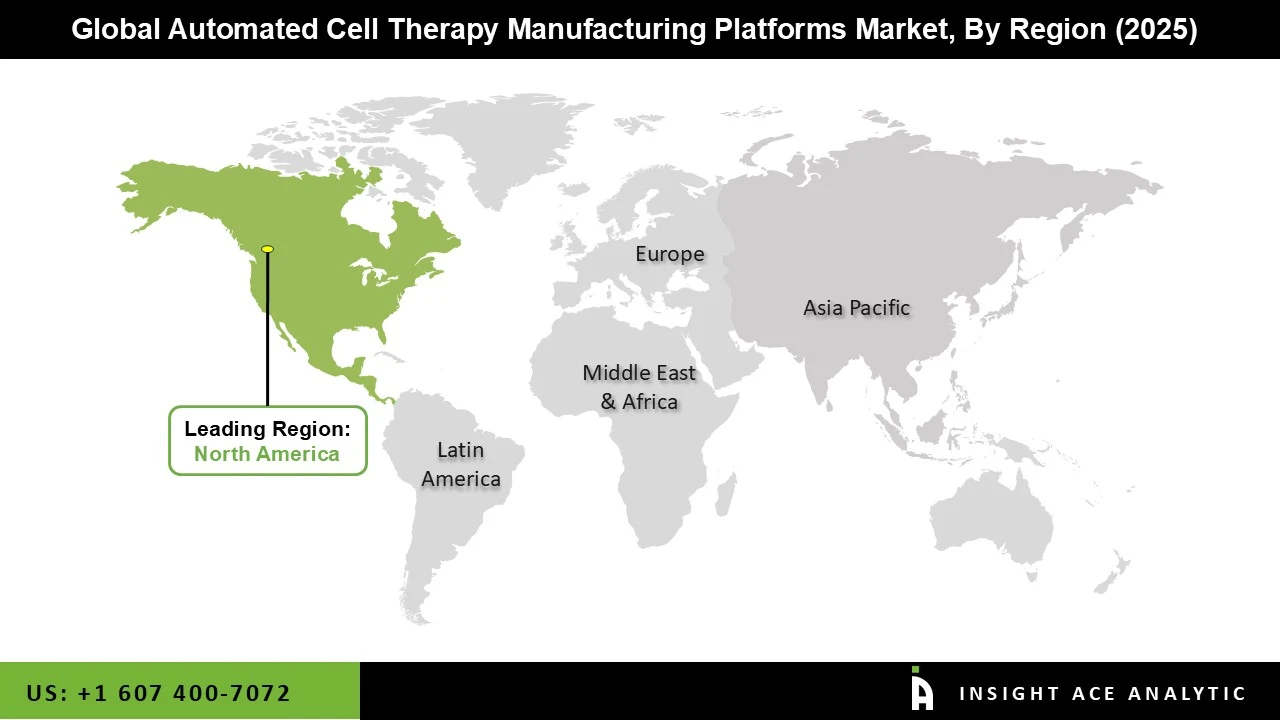
North America is expected to lead the market for automation platforms in the manufacturing of cell therapies due to the presence of a well-developed biotech and pharmaceutical industry in the region along with a strong manufacturing infrastructure for cell therapies and solid clinical research capabilities in the region. The United States is one of the key factors contributing to regional demand with a large number of companies in the region working in the development of cell therapies. There are also several contract development and manufacturing organizations (CDMOs) and key providers of these platforms such as Cellares, Miltenyi Biotec, and Thermo Fisher Scientific.
Key Development
November 2026: Octane Biotech and Currus Biologics completed the automation of CUR-001 manufacturing using Octane’s Cocoon Platform, establishing a closed process to support consistent clinical production. The milestone follows FDA clearance of Currus’ IND application in September 2026, enabling a Phase 1 trial in patients with advanced mesothelin-positive solid tumours, with first-patient dosing expected in early 2027. CUR-001 combines an autologous mesothelin-targeting CAR-T therapy with a BEAT bispecific antibody to address challenges associated with CAR-T treatment of solid tumours.
Automated Cell Therapy Manufacturing Platforms Market Report Scope:
| Report Attribute | Specifications |
| Growth Rate CAGR | CAGR of 19.5% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2022 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | Offering, Platform Architecture, Manufacturing Unit Operation, Therapy Modality, Therapy Sourcing Model and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; France; Italy; Spain; South Korea; Southeast Asia |
| Competitive Landscape | Octane Medical Group, Miltenyi Biotec, Cellares, Ori Biotech, Cytiva, Terumo BCT, Thermo Fisher Scientific, Sartorius, Wilson Wolf / ScaleReady, Adva Biotechnology, Multiply Labs, Fresenius Kabi, Cellular Origins, MaxCyte, Cellino Biotech |
| Customization Scope | Free customization report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customized to your particular study requirements. |
Market Segmentation:
Automated Cell Therapy Manufacturing Platforms Market by Offering -
• Instruments & Hardware Systems
o Integrated / End-to-End Platforms
o Modular Unit-Operation Instruments
o Robotic Orchestration Hardware
• Consumables, Cassettes & Process Kits
o Single-Use Cassettes & Tubing Sets
o Process Kits, Chambers & Flow Paths
o Platform-Dedicated Reagent & Selection Kits
• Software & Digital Orchestration
• Services
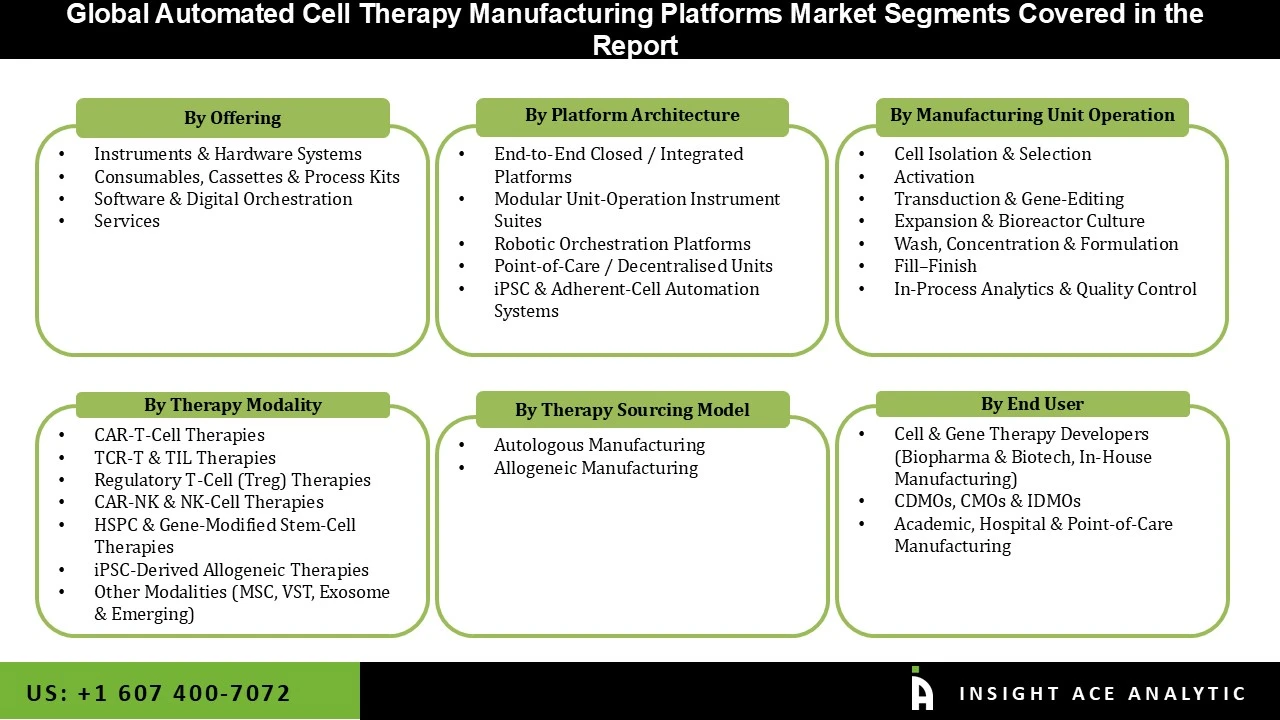
Automated Cell Therapy Manufacturing Platforms Market by Platform Architecture -
• End-to-End Closed / Integrated Platforms
• Modular Unit-Operation Instrument Suites
• Robotic Orchestration Platforms
• Point-of-Care / Decentralised Units
• iPSC & Adherent-Cell Automation Systems
Automated Cell Therapy Manufacturing Platforms Market by Manufacturing Unit Operation -
• Cell Isolation & Selection
• Activation
• Transduction & Gene-Editing
o Viral Transduction
o Non-Viral Gene Delivery & Electroporation
• Expansion & Bioreactor Culture
• Wash, Concentration & Formulation
• Fill–Finish
• In-Process Analytics & Quality Control
Automated Cell Therapy Manufacturing Platforms Market by Therapy Modality -
• CAR-T-Cell Therapies
• TCR-T & TIL Therapies
• Regulatory T-Cell (Treg) Therapies
• CAR-NK & NK-Cell Therapies
• HSPC & Gene-Modified Stem-Cell Therapies
• iPSC-Derived Allogeneic Therapies
• Other Modalities (MSC, VST, Exosome & Emerging)
Automated Cell Therapy Manufacturing Platforms Market by Therapy Sourcing Model -
• Autologous Manufacturing
• Allogeneic Manufacturing
Automated Cell Therapy Manufacturing Platforms Market by End User -
• Cell & Gene Therapy Developers (Biopharma & Biotech, In-House Manufacturing)
• CDMOs, CMOs & IDMOs
• Academic, Hospital & Point-of-Care Manufacturing
Automated Cell Therapy Manufacturing Platforms Market by Region-
North America-
• The US
• Canada
• Mexico
Europe-
• Germany
• The UK
• France
• Italy
• Spain
• Rest of Europe
Asia-Pacific-
• China
• Japan
• India
• South Korea
• South East Asia
• Rest of Asia Pacific
Latin America-
• Brazil
• Argentina
• Rest of Latin America
Middle East & Africa-
• GCC Countries
• South Africa
• Rest of Middle East and Africa
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
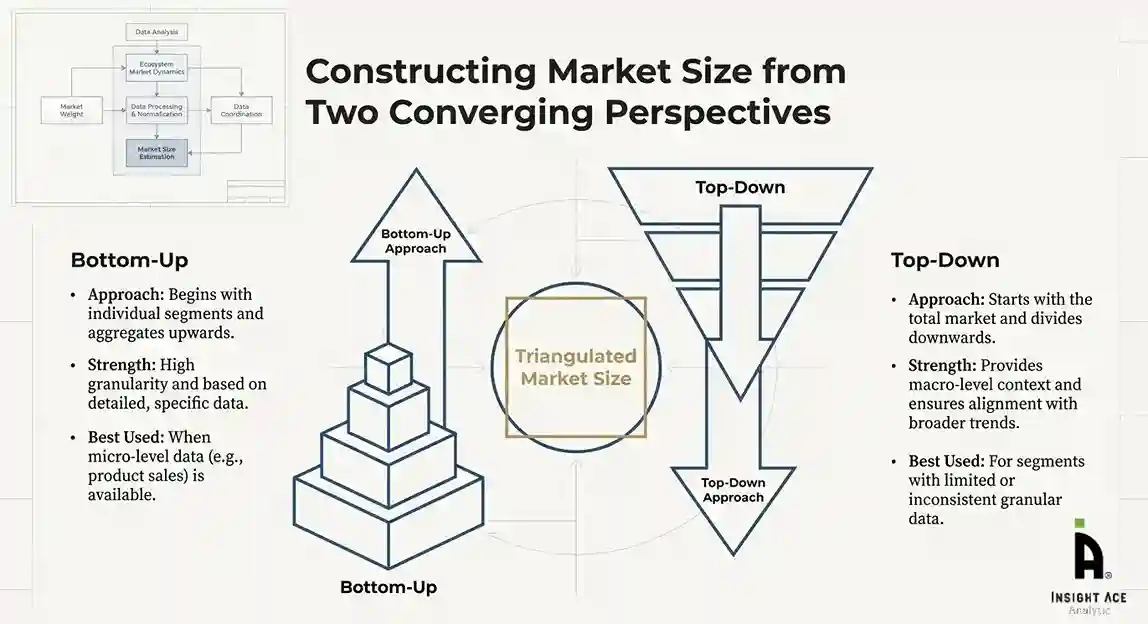
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
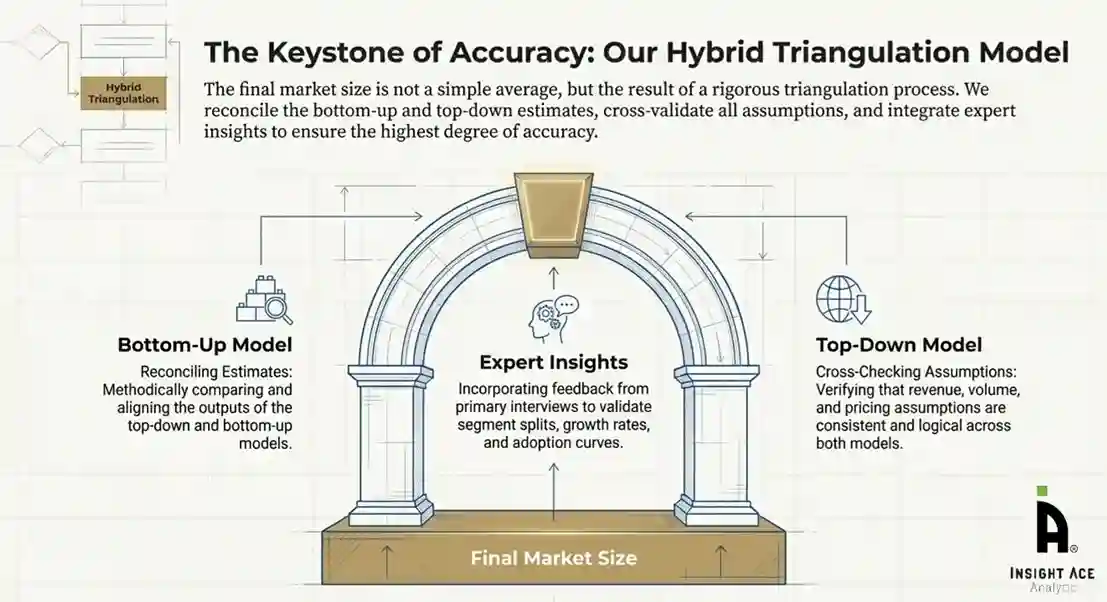
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
Automated Cell Therapy Manufacturing Platforms Market is estimated tog grow at a 19.5% CAGR during the forecast period for 2026 to 2035.
Octane Medical Group, Miltenyi Biotec, Cellares, Ori Biotech, Cytiva, Terumo BCT, Thermo Fisher Scientific, Sartorius, Wilson Wolf / ScaleReady, Adva Biotechnology, Multiply Labs, Fresenius Kabi, Cellular Origins, MaxCyte, Cellino Biotech
Automated Cell Therapy Manufacturing Platforms Market is segmented into Offering, Platform Architecture, Manufacturing Unit Operation, Therapy Modality, Therapy Sourcing Model and By Region.
North America region is leading the Automated Cell Therapy Manufacturing Platforms Market.