3D Rendering Market Size, Trend, Forecast Report 2026 to 2035
What is 3D Rendering Market Size?
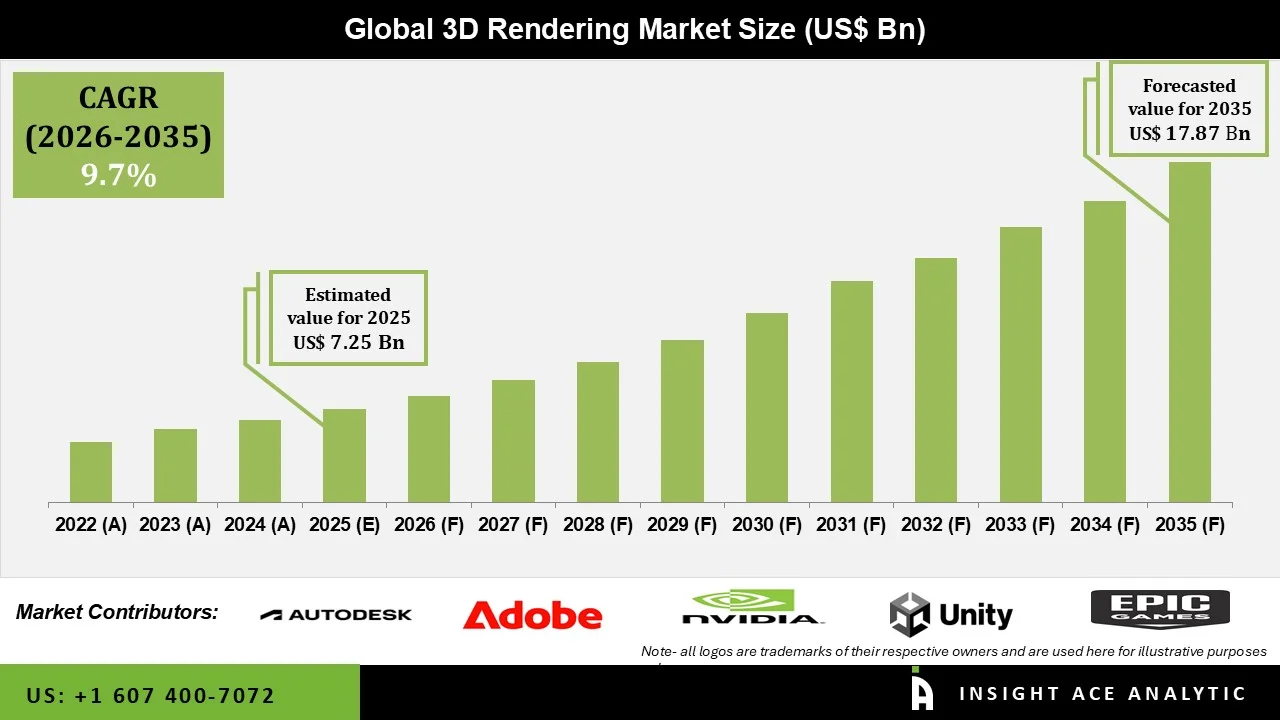
Global 3D Rendering Market Size is valued at USD 7.25 Bn in 2025 and is predicted to reach USD 17.87 Bn by the year 2035 at a 9.7 % CAGR during the forecast period for 2026 to 2035.
3D Rendering Market Size, Share & Trends Analysis Distribution by Component (Software, Services), by Deployment Type (Cloud, On Premises), by Rendering Type (Real Time Rendering, Offline Rendering), by Technology (GPU Based Rendering, CPU Based Rendering, Hybrid Rendering), by Application (Gaming, Media and Entertainment, Architecture Engineering and Construction, Manufacturing, Healthcare, Automotive, Education, Retail and E Commerce, Others) and Segment Forecasts, 2026 to 2035.
3D rendering transforms digital models into realistic images, animations, videos, and interactive experiences by applying lighting, textures, materials, shadows, and visual effects. It is widely used in gaming, media and entertainment, architecture, engineering and construction, manufacturing, automotive, healthcare, education, and retail. The 3D Rendering Market is expanding as businesses across industries increasingly rely on realistic digital visualization for design, development, marketing, simulation, and customer engagement.
Growing demand for photorealistic product visualisation, virtual environments, architectural walkthroughs, digital prototypes, and immersive experiences is encouraging companies to invest in advanced rendering software, services, and computing infrastructure. Real-time rendering is gaining importance in gaming, virtual reality, augmented reality, digital twins, and interactive applications, while offline rendering remains important for high-quality films, animation, advertising, and architectural visualisation. New technology is having a big impact on the 3D rendering market.
More companies are turning to cloud-based rendering, which gives them access to powerful computing without needing to buy expensive hardware. Artificial intelligence is also making rendering better and faster by helping with tasks like removing noise, improving images, optimizing scenes, creating materials, adjusting lighting, and automating content. These advances help cut down rendering time, boost visual quality, and make the process more efficient. Still, high computing needs, costs for software and hardware, data security, and finding skilled workers are ongoing challenges, especially for smaller businesses.
The market is growing as more industries use 3D rendering. In architecture, engineering, and construction, it helps show realistic building designs, walkthroughs, and project ideas before building starts. In manufacturing and automotive, companies use rendering for product images, digital prototypes, design reviews, vehicle customization, and marketing. Gaming and media companies want more lifelike characters, environments, and effects, while retailers and e-commerce businesses use 3D visuals and augmented reality to help customers see products better before buying. The combination of AI, GPU acceleration, cloud computing, and real-time rendering is likely to make rendering faster, more flexible, and accessible to a wider range of businesses. As companies look to reduce physical prototyping, improve design communication, shorten development cycles, and deliver more engaging digital experiences, 3D rendering is expected to become an increasingly important technology for visualisation, simulation, product development, and customer engagement.
Competitive Landscape
Which are the Leading Players in the 3D Rendering Market?
- Autodesk
- Adobe
- NVIDIA
- Unity Technologies
- Epic Games
- Chaos
- Maxon
- Dassault Systèmes
- Siemens Digital
- Trimble
- Blender Foundation
- OTOY
- Luxion
- Pixar Animation Studios
- Foundry
Market Dynamics
Driver
Rising Demand for Realistic Visualization Across Industries
The need for realistic, high-quality digital content is pushing more industries to use 3D rendering solutions. Companies now use 3D visualization to show products, develop designs, create simulations, and improve customer experiences without always needing physical prototypes. In architecture and construction, realistic renderings help clients see buildings and interiors before they are built. Manufacturers and automotive companies use 3D rendering for product design, prototyping, and marketing. The gaming, media, and entertainment industries are also investing in advanced rendering to create detailed environments, characters, and visual effects. As more businesses move to digital design and visualization, the demand for faster and more realistic rendering solutions is likely to keep growing.
Restraint / Challenge
High Computing Requirements and Cost of Advanced Rendering Solutions
Despite its strong growth potential, the 3D Rendering Market faces challenges related to the cost and complexity of advanced rendering technologies. High-quality rendering, particularly for complex scenes, animations, and real-time applications, can require powerful GPUs, high-performance computing infrastructure, and specialised software. These requirements can increase costs for businesses, especially small and medium-sized companies. Cloud rendering can reduce the need for large investments in local hardware, but concerns around cloud costs, data security, connectivity, and managing large files can affect adoption. In addition, skilled professionals are often needed to handle 3D modeling, lighting, texturing, animation, and rendering workflows. Software compatibility and the need to keep up with rapidly changing technologies can also create challenges for market participants.
Gaming and Media & Entertainment Segment is Expected to Drive the 3D Rendering Market
The gaming and media & entertainment segment is expected to remain a major growth area for the 3D rendering market. Game developers, animation studios, film producers, and visual effects companies require increasingly realistic digital environments, characters, lighting, and special effects. The growing popularity of immersive gaming, virtual reality, augmented reality, and interactive entertainment is increasing demand for real-time rendering technologies that can deliver high-quality visuals with minimal delay. At the same time, offline rendering continues to be widely used for films, animation, advertising, and other applications where photorealistic image quality is a priority. Continued investment in digital content, virtual production, and immersive experiences is expected to support demand for advanced rendering solutions in this segment.
Architecture, Engineering and Construction Segment is Expected to Drive the 3D Rendering Market
The Architecture, Engineering, and Construction (AEC) segment is also a major growth area as more companies use 3D visualization in design and planning. Architects, engineers, developers, and real estate firms use realistic renderings, walkthroughs, and interactive models to share project ideas and help clients understand designs before building starts. 3D rendering also helps with interior design, marketing, design reviews, and presentations to investors and other stakeholders. As more companies use Building Information Modeling, digital twins, virtual walkthroughs, and smart construction tools, the need for advanced visualization is growing. As construction companies and developers move to digital workflows, demand for 3D rendering is expected to rise.
Why North America Leads the 3D Rendering Market?
North America is expected to maintain a leading position in the 3D rendering market, supported by advanced digital infrastructure, strong adoption of cloud computing and high-performance GPUs, and the presence of major technology and software companies. The U.S. has established industries in gaming, media, entertainment, architecture, automotive, manufacturing, and advertising, all of which rely more on realistic 3D visualization. More companies are using real-time rendering, AI-assisted rendering, virtual reality, augmented reality, and digital twins, which is helping the market grow. Investments in artificial intelligence, graphics processing, and cloud-based rendering are helping businesses speed up rendering and cut production time. Skilled designers, developers, animation studios, and tech providers are driving innovation.
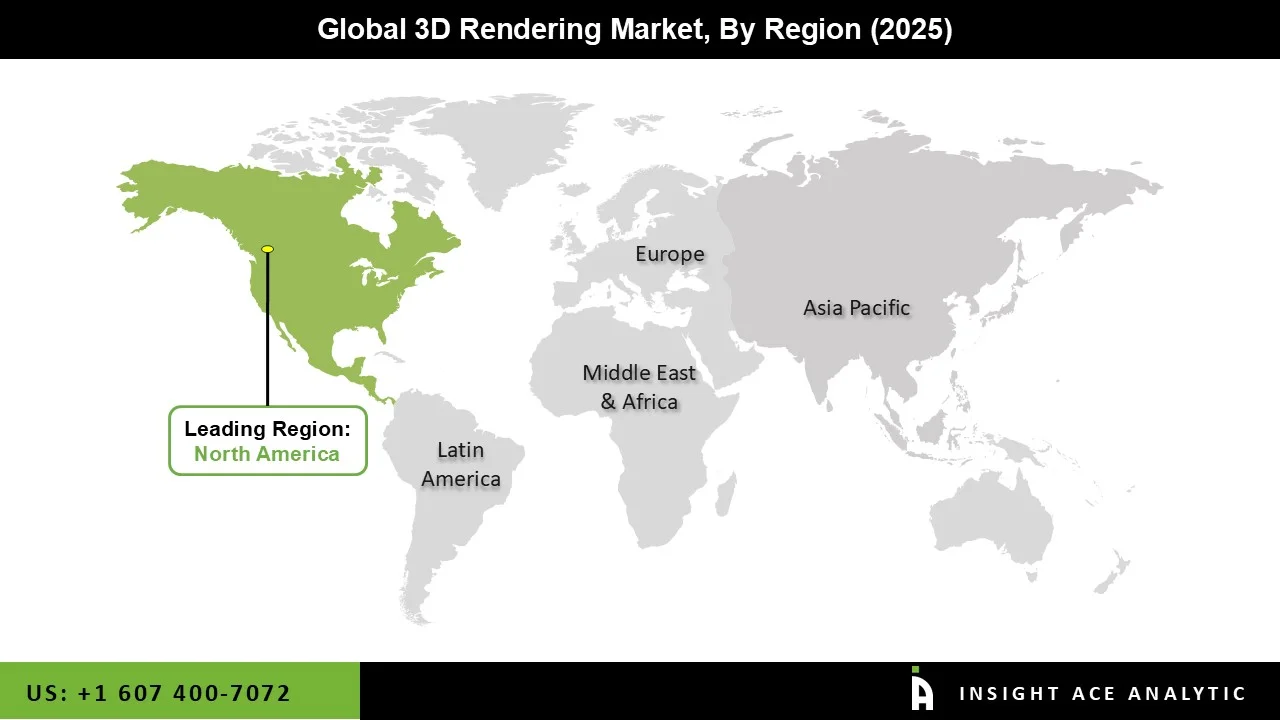
Asia Pacific is expected to witness significant growth during the forecast period, driven by expanding gaming and entertainment industries, rising construction activity, and increasing adoption of digital design technologies. Countries such as China, Japan, India, South Korea, and Australia are investing in 3D visualization, animation, automotive design, and immersive technologies. Growing access to cloud computing and high-performance graphics technologies is further supporting adoption. Increasing digitalization across industries is expected to make Asia Pacific an increasingly important market for 3D rendering solutions.
Key Developments-
• In March 2025, Autodesk continued strengthening its 3D design and visualization ecosystem, supporting professionals across architecture, engineering, construction, manufacturing, and media. Its continued development of 3D design, visualization, and rendering capabilities reinforces its position in the 3D Rendering Market.
• In April 2025, Adobe continued enhancing its creative software ecosystem with tools and workflows supporting 3D content creation, visualization, and digital experiences. Its broad presence across creative professionals and digital content production supports its role in the 3D Rendering Market.
3D Rendering Market Report Scope:
| Report Attribute | Specifications |
| Market size value in 2025 | USD 7.25 Bn |
| Revenue forecast in 2035 | USD 17.87 Bn |
| Growth Rate CAGR | CAGR of 9.7% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2021 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | Component, Deployment Type, Rendering Type, Technology, Application and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; France; Italy; Spain; South Korea; Southeast Asia |
| Competitive Landscape | Autodesk, Adobe, NVIDIA, Unity Technologies, Epic Games, Chaos, Maxon, Dassault Systèmes, Siemens Digital, Trimble, Blender Foundation, OTOY, Luxion, Pixar Animation Studios, Foundry. |
| Customization Scope | Free customisation report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customized to your particular study requirements. |
Segmentation 3D Rendering Market:
3D Rendering Market by Component-
- Software
- Services
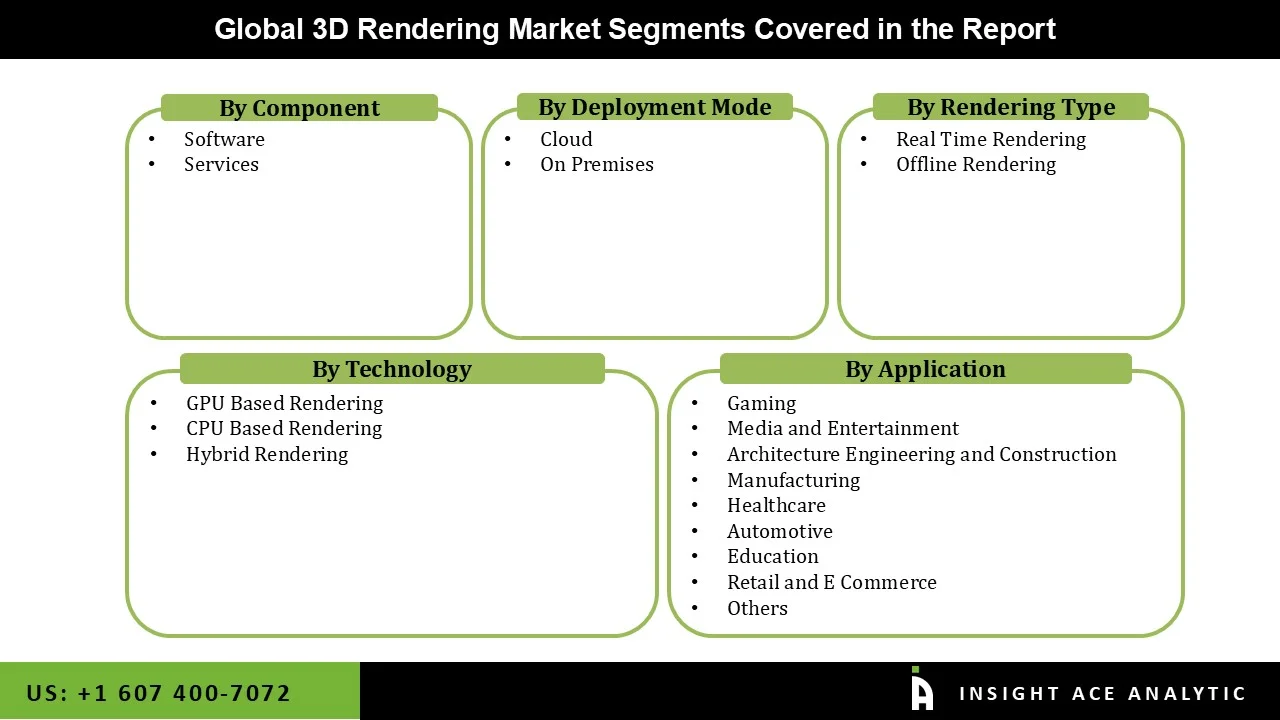
3D Rendering Market by Deployment Type-
- Cloud
- On Premises
3D Rendering Market by Technology-
- GPU Based Rendering
- CPU Based Rendering
- Hybrid Rendering
3D Rendering Market by Rendering Type-
- Real Time Rendering
- Offline Rendering
3D Rendering Market by Application-
- Gaming
- Media and Entertainment
- Architecture Engineering and Construction
- Manufacturing
- Healthcare
- Automotive
- Education
- Retail and E Commerce
- Others
3D Rendering Market by Region-
- North America-
- The US
- Canada
- Europe-
- Germany
- The UK
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific-
- China
- Japan
- India
- South Korea
- South East Asia
- Rest of Asia Pacific
- Latin America-
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Middle East and Africa-
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
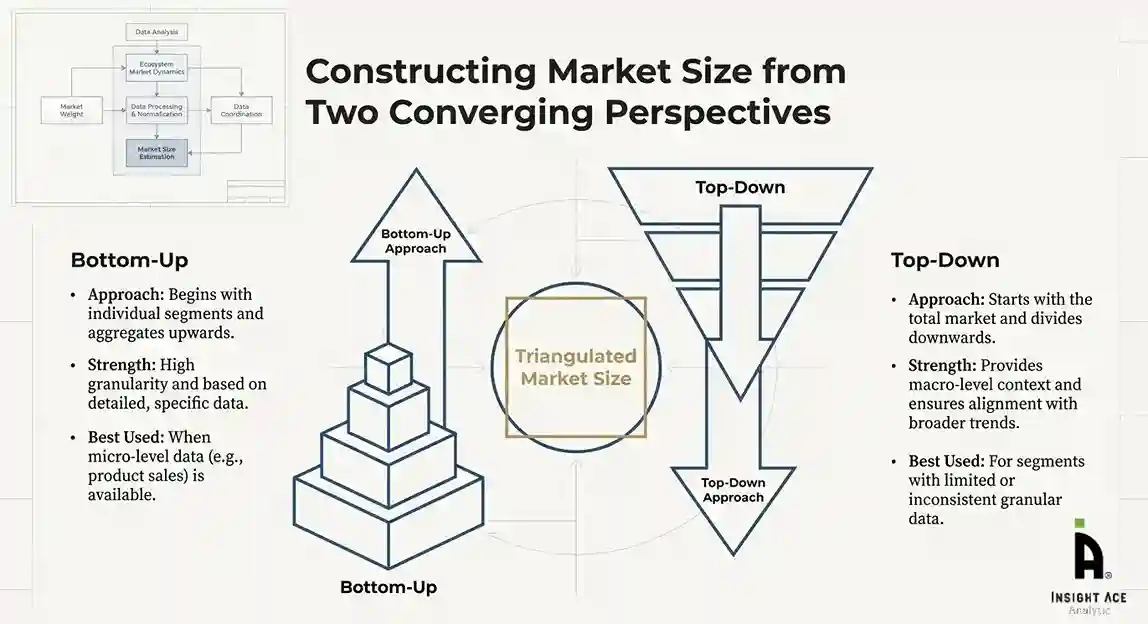
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
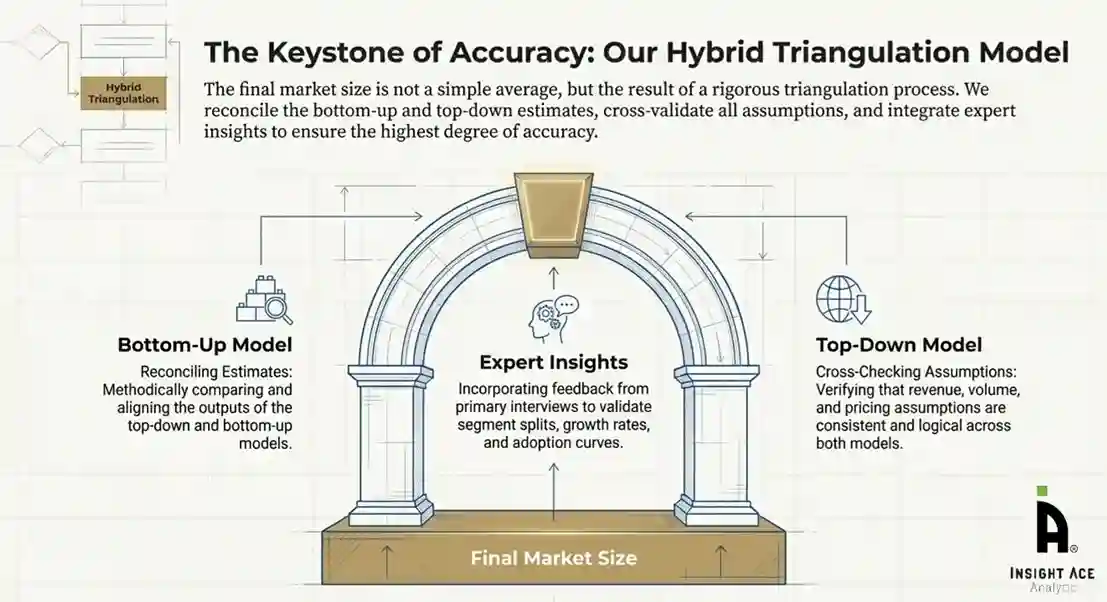
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
3D Rendering Market Size is valued at USD 7.25 Bn in 2025 and is predicted to reach USD 17.87 Bn by the year 2035
The 3D Rendering Market is expected to grow at a 9.7% CAGR during the forecast period for 2026 to 2035
Autodesk, Adobe, NVIDIA, Unity Technologies, Epic Games, Chaos, Maxon, Dassault Systèmes, Siemens Digital, Trimble, Blender Foundation, OTOY, Luxion, Pixar Animation Studios, Foundry.
3D Rendering Market is segmented into Component, Deployment Type, Rendering Type, Technology, Application and Other.
North America region is leading the 3D Rendering Market