LTE Advanced Pro Market Size, Trend, Revenue Report 2026 to 2035
What is LTE Advanced Pro Market Size?
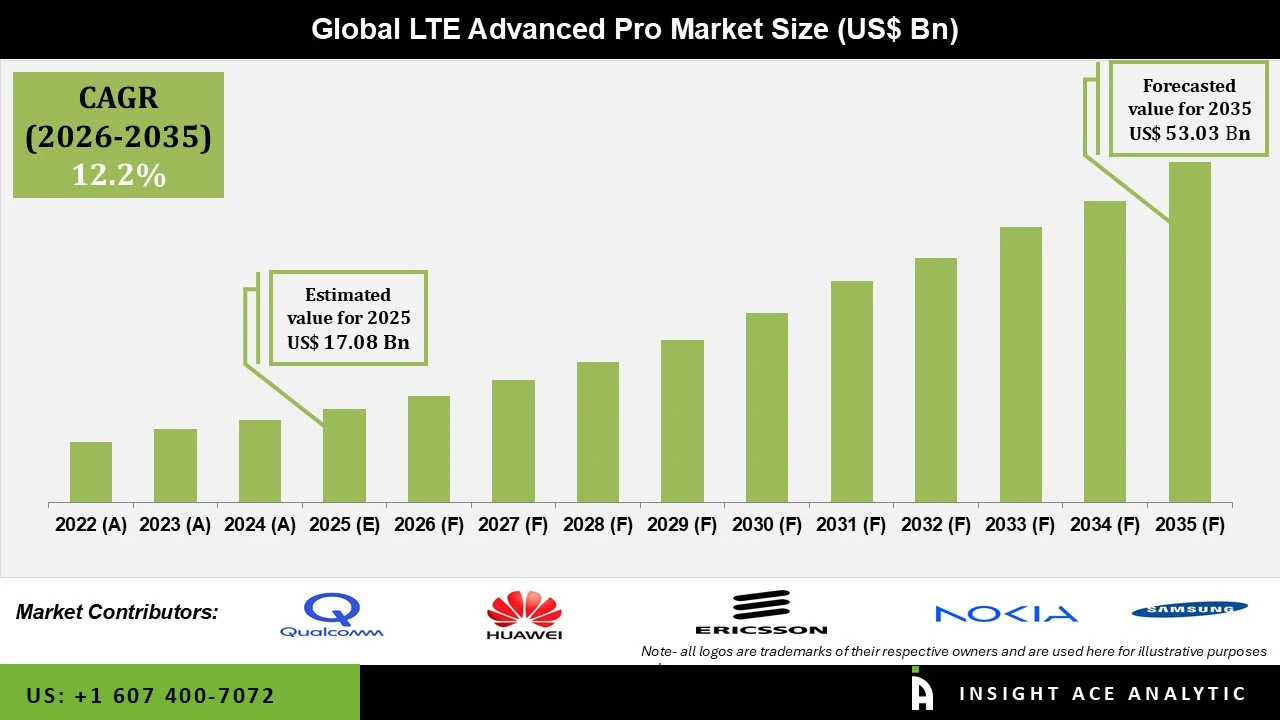
LTE Advanced Pro Market Size is valued at USD 17.08 Bn in 2025 and is predicted to reach USD 53.03 Bn by the year 2035 at an 12.2% CAGR during the forecast period for 2026 to 2035.
LTE Advanced Pro Market Size, Share & Trends Analysis Distribution by LTE Advanced Pro Market (Carrier Aggregation, Massive MIMO, Network Slicing, Ultra-Reliable Low-Latency Communication), by Application (Mobile Broadband, Machine-to-Machine Communication, Fixed Wireless Access, Public Safety), by End-Use (Consumer Electronics, Telecommunications, Automotive, Smart Cities), by Service Type (Deployment Services, Managed Services, Consulting Services) and Segment Forecasts, 2026 to 2035
LTE Advanced Pro is becoming an important part of modern wireless communication as mobile operators, enterprises, and industries seek faster, more reliable, higher-capacity connectivity. LTE Advanced Pro builds on LTE by adding capabilities such as carrier aggregation, massive MIMO, improved spectrum efficiency, network optimisation, and support for low-latency, highly reliable communications. These technologies help operators increase network capacity, improve data speeds, enhance coverage, and support more connected devices and applications. As more people use smartphones, connected devices, industrial IoT, and data-heavy applications, the need for advanced mobile networks is rising. With mobile traffic growing, network operators are investing in technologies that use spectrum more efficiently while keeping connections reliable.
LTE Advanced Pro is a key platform for meeting these needs, especially in places where operators are still expanding and improving LTE networks while also working on 5G. Technological advancements continue to expand the capabilities of LTE Advanced Pro. Carrier aggregation enables operators to combine multiple spectrum bands to provide higher data rates and better network capacity, while massive MIMO improves spectral efficiency and network performance by using multiple antennas for simultaneous data transmission. Network slicing and advanced network management capabilities can support differentiated services for applications with varying performance and reliability requirements. Ultra-reliable, low-latency communication is also becoming increasingly relevant for applications such as industrial connectivity, connected vehicles, public safety, and other mission-critical services.
LTE Advanced Pro is used in many different ways. Mobile broadband is still a main use, as people rely on fast connections for streaming video, using cloud services, gaming, social media, and other data-heavy activities. Machine-to-machine communication and IoT are opening up new possibilities by connecting equipment, sensors, vehicles, and more. Fixed wireless access can bring high-speed internet to places without good wired broadband, and public safety networks can get better reliability, coverage, and communication features. The technology also has applications across several end-use industries. Telecommunications operators are using LTE Advanced Pro to improve network performance, increase capacity, and extend the value of existing LTE infrastructure. In the automotive sector, advanced LTE connectivity can support connected vehicles, telematics, fleet management, and other digital services.
Smart city initiatives are creating additional demand for reliable wireless connectivity to support connected infrastructure, surveillance systems, traffic management, and public services. Consumer electronics, including smartphones, tablets, connected devices, and other wireless products, continue to contribute to demand for higher-performance mobile connectivity. Even with these opportunities, the LTE Advanced Pro market has some challenges. Setting up advanced network technology often needs big investments in infrastructure, spectrum, base stations, antennas, and other equipment. Making sure everything works together can also make things more complicated, especially for operators using gear from different vendors. The move to 5G may also affect where operators choose to invest. Because of this, operators have to balance LTE advanced pro upgrades with bigger network modernization plans and changing customer needs.
Overall, the global LTE advanced pro market is expected to benefit from the continued growth of mobile data traffic, connected devices, IoT applications, fixed wireless access, and demand for reliable high-speed connectivity. The need to improve network capacity, enhance spectrum utilisation, support low-latency applications, and optimise existing LTE infrastructure is encouraging operators and enterprises to adopt advanced LTE technologies. Continued developments in carrier aggregation, massive MIMO, network optimisation, and intelligent network management are expected to strengthen LTE Advanced Pro's role across telecommunications, automotive, smart city, industrial, and consumer applications. As wireless networks continue to evolve toward more connected, data-intensive environments, LTE Advanced Pro is likely to remain an important technology for improving network performance and supporting the transition to next-generation connectivity.
Competitive Landscape
Which are the Leading Players in the LTE Advanced Pro Market?
• Qualcomm
• Huawei
• Ericsson
• Nokia
• Samsung
• ZTE
• Cisco
• Intel
• AT&T
• Verizon
Driver
Growing Demand for High-Speed and Reliable Mobile Connectivity is Driving the LTE Advanced Pro Market
Growing demand for high-speed, reliable, and efficient wireless connectivity is a major driver of the global LTE Advanced Pro Market. The rapid increase in mobile data traffic, connected devices, video streaming, cloud-based applications, and IoT services is encouraging mobile network operators to improve network capacity and performance. LTE Advanced Pro technologies help operators address these requirements by improving data speeds, spectrum efficiency, coverage, and overall network capacity.
Technologies like carrier aggregation let operators combine different frequency bands to offer faster data speeds and use spectrum more efficiently. Massive MIMO boosts network capacity by using many antennas to send and receive data at the same time. These features are especially useful in crowded areas where networks handle a lot of traffic. More use of machine-to-machine communication, connected vehicles, smart city projects, and fixed wireless access is raising the need for advanced LTE features. Both businesses and public organizations need dependable wireless connections for devices, industry, security systems, transport, and other digital services. Operators in developing markets are also upgrading their LTE networks to improve connectivity and get the most out of their current infrastructure. As data use grows and networks need to perform better and cover more areas, ongoing investment in LTE Advanced Pro technologies is likely across telecom and other connected industries.
Restraint/Challenge
High Infrastructure Investment and the Transition Toward 5G May Limit LTE Advanced Pro Market Expansion
The high cost of upgrading and maintaining advanced mobile network infrastructure remains a key challenge for the LTE Advanced Pro Market. Implementing technologies such as massive MIMO and carrier aggregation can require investments in base stations, antennas, spectrum resources, network equipment, software, and supporting infrastructure. These costs can be particularly challenging for smaller operators and markets with limited telecommunications investment. Operators also face technical hurdles when adding LTE Advanced Pro technologies to their current networks. Managing different frequency bands, equipment from various vendors, and older network parts can make deployment more complex. Limited spectrum and regulatory rules can also make it harder to add advanced LTE features. The growth of 5G networks is another key challenge. As operators spend more on 5G, some may focus on new networks instead of upgrading LTE Advanced Pro.
Still, LTE is widely used, and operators may keep improving LTE networks to ensure good coverage and capacity, especially where 5G is not yet common. To address these challenges, technology providers are focusing on cost-efficient network upgrades, software-based improvements, multi-band solutions, and equipment that can support both existing LTE infrastructure and future network technologies. These developments can help operators improve network performance while managing infrastructure investment.
Telecommunications Segment is Expected to Account for a Significant Share of the LTE Advanced Pro Market
Telecommunications is expected to make up a large part of the LTE Advanced Pro market as operators keep working to improve capacity, coverage, and service quality. More mobile data use and more connected devices are pushing operators to use their spectrum and infrastructure more efficiently. LTE Advanced Pro provides operators with technologies such as carrier aggregation and massive MIMO that can improve network capacity and data speeds without requiring an entirely new network architecture. These capabilities are particularly important in urban areas, where high concentrations of mobile users can place significant pressure on network resources.
Telecommunications companies are also using advanced LTE capabilities to support applications such as mobile broadband, IoT connectivity, machine-to-machine communication, fixed wireless access, and enterprise services. LTE Advanced Pro can help operators provide reliable connectivity while extending the useful life of existing LTE infrastructure. Continued growth in connected devices, mobile applications, digital services, and wireless data traffic is expected to support demand in the telecommunications sector. Operators are likely to continue balancing LTE Advanced Pro investments with 5G deployment strategies, particularly in markets where LTE remains an important part of the overall mobile network.
Carrier Aggregation Segment is Expected to Witness Strong Growth in the LTE Advanced Pro Market
Carrier aggregation is expected to remain an important technology within the LTE advanced pro market as operators seek to increase network speeds and improve spectrum utilisation. Carrier aggregation combines multiple spectrum bands, or component carriers, enabling networks to deliver higher throughput and improved capacity than traditional LTE configurations. The growing demand for high-speed mobile broadband is increasing the importance of carrier aggregation. Consumers are using mobile networks for bandwidth-intensive activities such as video streaming, online gaming, cloud applications, video conferencing, and other data-heavy services. At the same time, businesses are increasingly depending on wireless connectivity for connected devices, remote operations, and digital applications. Carrier aggregation also helps operators make better use of scattered spectrum. By combining what they have, they can improve network performance and keep using their current LTE networks. This is useful for operators who want more capacity without replacing everything. With mobile data traffic rising and operators looking for affordable ways to boost network performance, carrier aggregation is expected to keep creating new opportunities in the LTE Advanced Pro Market.
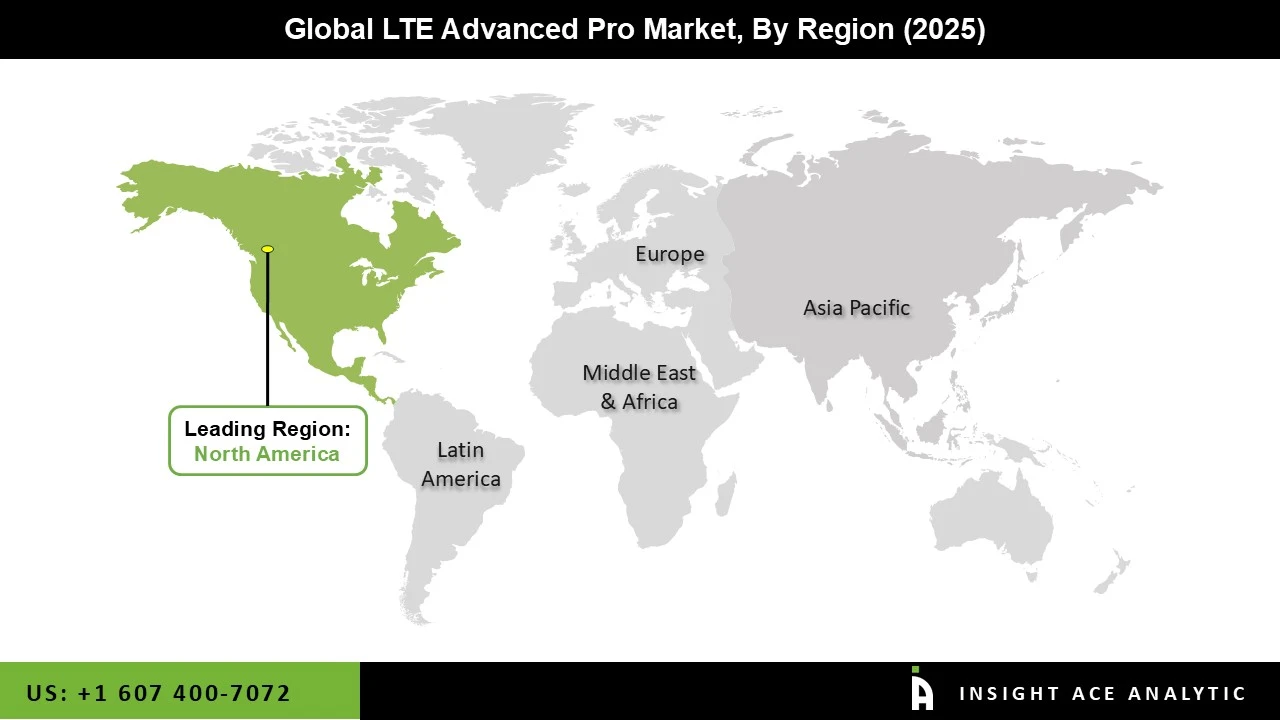
Why North America Led the LTE Advanced Pro Market?
North America represents a significant market for LTE Advanced Pro, supported by advanced telecommunications infrastructure, high mobile data consumption, and continued investment in wireless network technologies. The U.S. accounts for a substantial portion of regional demand, with telecommunications operators continuously upgrading their networks to improve capacity, coverage, and service quality. The region has a well-established ecosystem of telecommunications operators. The region has a strong network of telecom operators, equipment suppliers, chip makers, and tech companies. This setup supports the rollout and development of advanced LTE technologies like carrier aggregation, massive MIMO, and network optimisation. Wireless access and data-intensive mobile services are increasing demand for high-capacity wireless networks.
Key Developments:
• In March 2026, Huawei advanced its wireless network solutions with new capabilities focused on improving network capacity, connectivity efficiency, and intelligent network operations. The developments support operators in optimizing existing cellular infrastructure while addressing growing mobile data traffic and demand for reliable high-speed connectivity.
In May 2026, ZTE introduced enhancements to its wireless network solutions focused on improving network capacity, spectrum efficiency, and high-speed connectivity. The developments are aimed at supporting operators in upgrading existing cellular infrastructure and meeting increasing demand for mobile broadband and connected applications.
LTE Advanced Pro Market Report Scope:
| Report Attribute | Specifications |
| Market size value in 2025 | USD 17.08 Bn |
| Revenue forecast in 2035 | USD 53.03 Bn |
| Growth Rate CAGR | CAGR of 12.2% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2021 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | LTE Advanced Pro Market, Application, End-Use, Service Type and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; France; Italy; Spain; South Korea; Southeast Asia |
| Competitive Landscape | Qualcomm, Huawei, Ericsson, Nokia, Samsung, ZTE, Cisco, Intel, AT&T, Verizon |
| Customization Scope | Free customisation report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customised to your particular study requirements. |
Market Segmentation:
LTE Advanced Pro Market by LTE Advanced Pro Market -
• Carrier Aggregation
• Massive MIMO
• Network Slicing
• Ultra-Reliable Low-Latency Communication
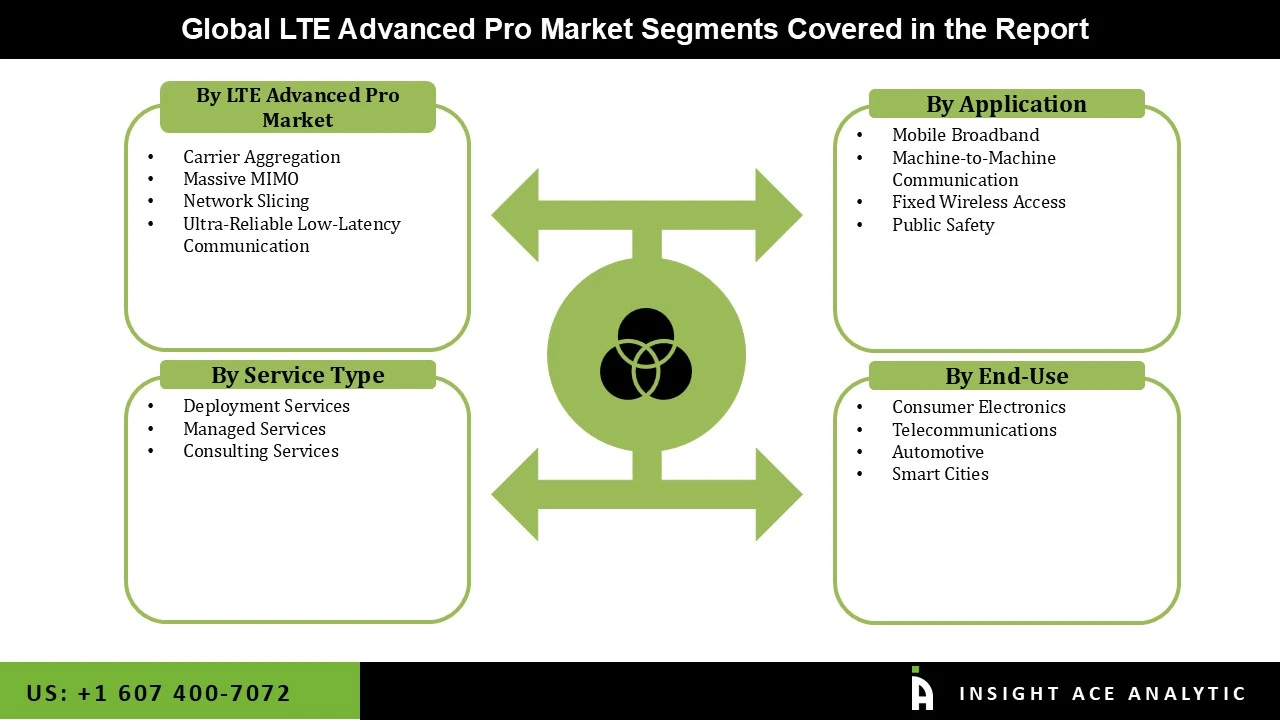
LTE Advanced Pro Market by Application -
• Mobile Broadband
• Machine-to-Machine Communication
• Fixed Wireless Access
• Public Safety
LTE Advanced Pro Market by Service Type -
• Deployment Services
• Managed Services
• Consulting Services
LTE Advanced Pro Market by End User -
• Consumer Electronics
• Telecommunications
• Automotive
• Smart Cities
LTE Advanced Pro Market by Region-
North America-
• The US
• Canada
• Rest of North America
Europe-
• Germany
• United Kingdom
• France
• Italy
• Nordics
• Rest of Europe
Asia-Pacific-
• Japan
• China
• South Korea
• India
• Australia
• Rest of Asia-Pacific
Middle East and Africa-
• GCC & Saudi Arabia
• South Africa
• Rest of Middle East & Africa
Latin America-
• Brazil
• Rest of Latin America
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
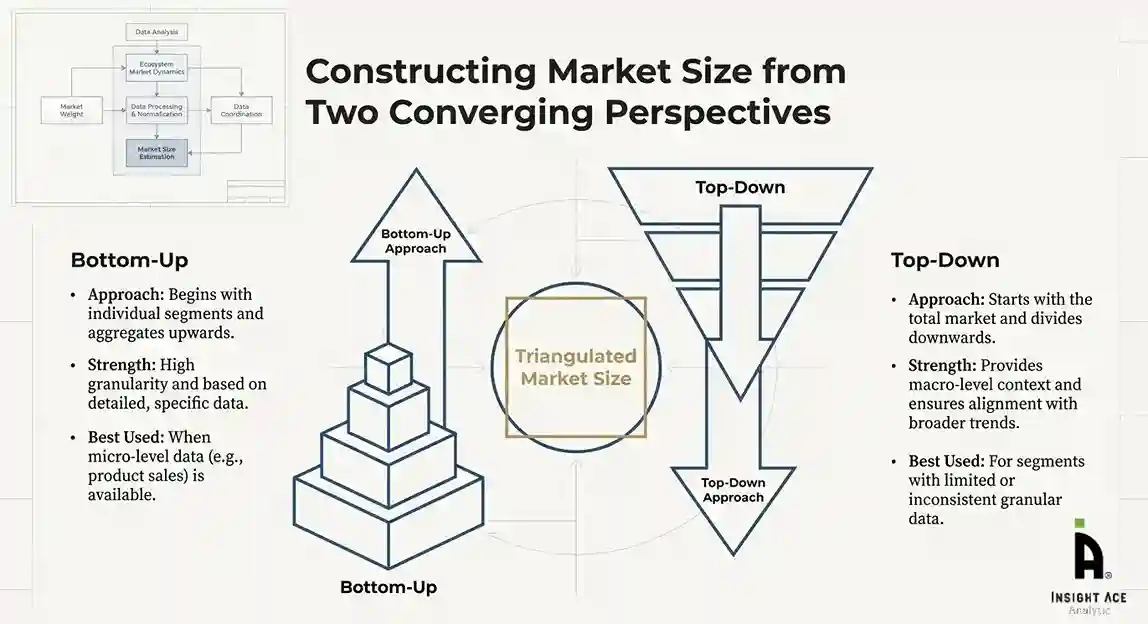
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
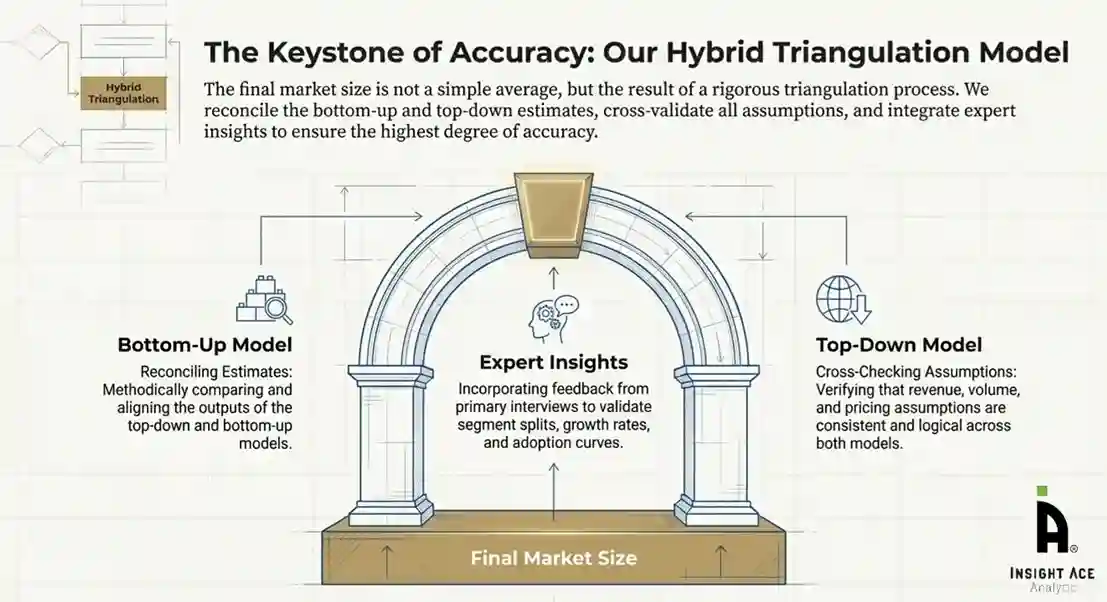
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
LTE Advanced Pro Market Size is valued at USD 17.08 Bn in 2025 and is predicted to reach USD 53.03 Bn by the year 2035
LTE Advanced Pro Market is expected to grow at an 12.2% CAGR during the forecast period for 2026 to 2035.
Qualcomm, Huawei, Ericsson, Nokia, Samsung, ZTE, Cisco, Intel, AT&T, Verizon
LTE Advanced Pro Market is segmented into Application, End-Use, Service Type and By Region.
North America region is leading the LTE Advanced Pro Market.