LNG Terminals Market Size, Share, Scope, Forecast Report 2026 to 2035
What is LNG Terminals Market Size?
LNG Terminals Market is estimated to grow with a 9.4% CAGR during the forecast period for 2026 to 2035.
LNG Terminals Market Size, Share & Trends Analysis Distribution by Terminal Type (Liquefaction & Export Terminals, Onshore Liquefaction / Export Terminals, Floating Liquefaction, Regasification & Import Terminals, Onshore Regasification / Import Terminals, Floating Storage & Regasification), by Infrastructure Configuration (Onshore / Fixed Terminals, Floating Terminals), by Trminal Capacity / Scale (Large-Scale Baseload Terminals, Mid-Scale Terminals, Small-Scale LNG Terminals) and Segment Forecasts, 2026 to 2035
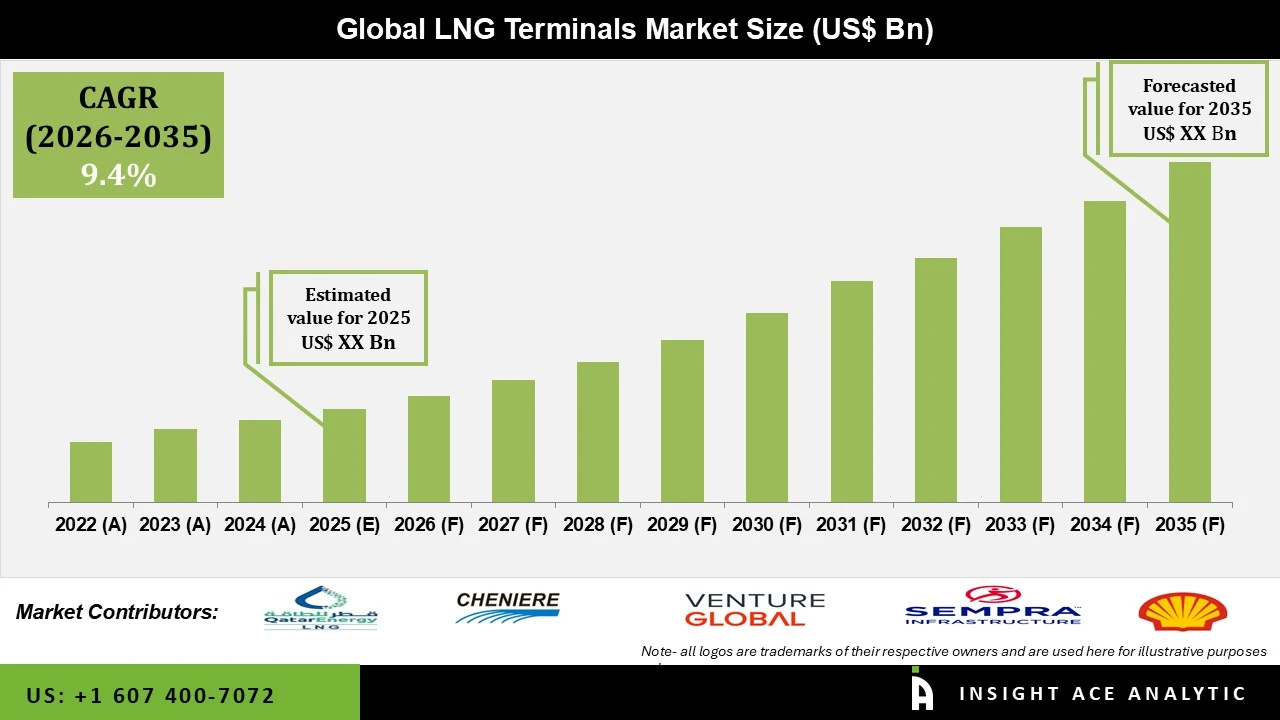
LNG terminals are specialised facilities that enable the international trade of natural gas by converting it between gaseous and liquid states for efficient storage and transportation. Liquefaction terminals cool natural gas to approximately –162°C, reducing its volume for ocean shipment, while regasification terminals convert liquefied natural gas (LNG) back into gas for pipeline distribution and end use.
The LNG terminals market covers planning, engineering, construction, expansion, operation, and maintenance of terminal infrastructure for energy, power generation, industry, and natural gas distribution. Key players are LNG producers, terminal operators, energy companies, infrastructure developers, engineering and construction firms, and technology and equipment suppliers. The market is growing because of higher demand for natural gas, increased international LNG trade, energy security concerns, and investments in import and export infrastructure. It includes different types of infrastructure, like fixed onshore facilities and floating terminals, for projects of all sizes. As countries seek more energy options and build stronger gas networks, LNG terminals continue to connect gas-producing regions with importing markets and help keep global natural gas supply steady.
Competitive Landscape
Which are the Leading Players in the LNG Terminals Market?
• QatarEnergy LNG
• Cheniere Energy
• Venture Global
• Sempra Infrastructure
• Shell plc
• TotalEnergies SE
• ADNOC Gas
• Woodside Energy Group
• PETRONAS
• Freeport LNG
• Nigeria LNG
• Sonatrach
• Petronet LNG
• Enagás
• Korea Gas Corporation
• JERA
• Gate terminal
• Snam
• GAIL (India) Limited
• Pertamina
• Fluxys
• PipeChina
• Excelerate Energy
• Höegh Evi
• Golar LNG
• New Fortress Energy
• BW LNG
• Mitsui O.S.K. Lines
• Karpowership
• Deutsche ReGas
• AG&P LNG / Nebula Energy
• H-Energy
• Bechtel
• Technip Energies
• Chiyoda Corporation
• Saipem
• KBR
• Air Products
• Chart Industries
• Baker Hughes
• Linde Engineering
• Samsung Heavy Industries
Driver
Growing Global LNG Trade and Demand for Natural Gas
Rising demand for natural gas in power generation, industry, and residential and commercial use is driving investment in LNG terminal infrastructure. Countries are expanding liquefaction and export facilities to serve international markets, while importing nations are developing regasification terminals to diversify energy sources and improve supply security. Expanding cross-border LNG trade grows, both onshore and floating terminals are seeing new opportunities. Floating storage and regasification units (FSRUs) also give countries a flexible way to add import capacity without the long construction times and high upfront costs of permanent onshore facilities. These trends are driving LNG terminal growth and expansion in both established and emerging markets.
Restraint/Challenge
High Capital Investment and Long Project Development Timelines
The LNG terminals market faces challenges because developing specialised infrastructure requires substantial investment, including liquefaction trains, storage tanks, marine loading facilities, regasification systems, and pipelines. Large projects often require extensive planning, environmental reviews, regulatory approvals, and coordination among many stakeholders before construction begins. Changes in construction costs, financing, equipment availability, and project schedules can also impact project economics. LNG terminal operators must meet strict safety and environmental rules during both construction and operation. These issues can delay projects, raise costs, and make it harder for smaller developers and emerging markets to fund new terminal capacity.
Floating Terminals Segment is Gaining Momentum in the LNG Terminals Market
The floating terminals segment is gaining attention as countries and energy companies seek flexible and cost-effective ways to import and export LNG. Floating storage and regasification units (FSRUs) can add import capacity without needing as much permanent onshore infrastructure as traditional terminals, making them appealing for countries that want to quickly set up or expand gas supply. Floating liquefaction technology also helps develop offshore gas resources where building onshore facilities is hard or expensive. Interest in diversifying energy supply, faster project timelines, and flexible infrastructure is driving investment in floating terminals. Still, their use depends on factors such as vessel availability, operating costs, marine conditions, and pipeline access.
Large-Scale Baseload Terminals Segment is Expected to Drive the LNG Terminals Market
The large-scale baseload terminals segment is expected to account for a significant share of the LNG terminals market because they can handle large amounts of natural gas to meet long-term supply needs. These terminals support large-scale LNG production, international exports, and steady gas imports for power and industry. Their large storage, processing, loading, and regasification facilities make them well-suited for major energy companies and countries with high gas demand. Investments in new LNG projects, expansions of existing facilities, and long-term supply deals are helping build more large-scale terminals. Their role in maintaining reliable gas flows between major exporters and importers continues to drive infrastructure investment.
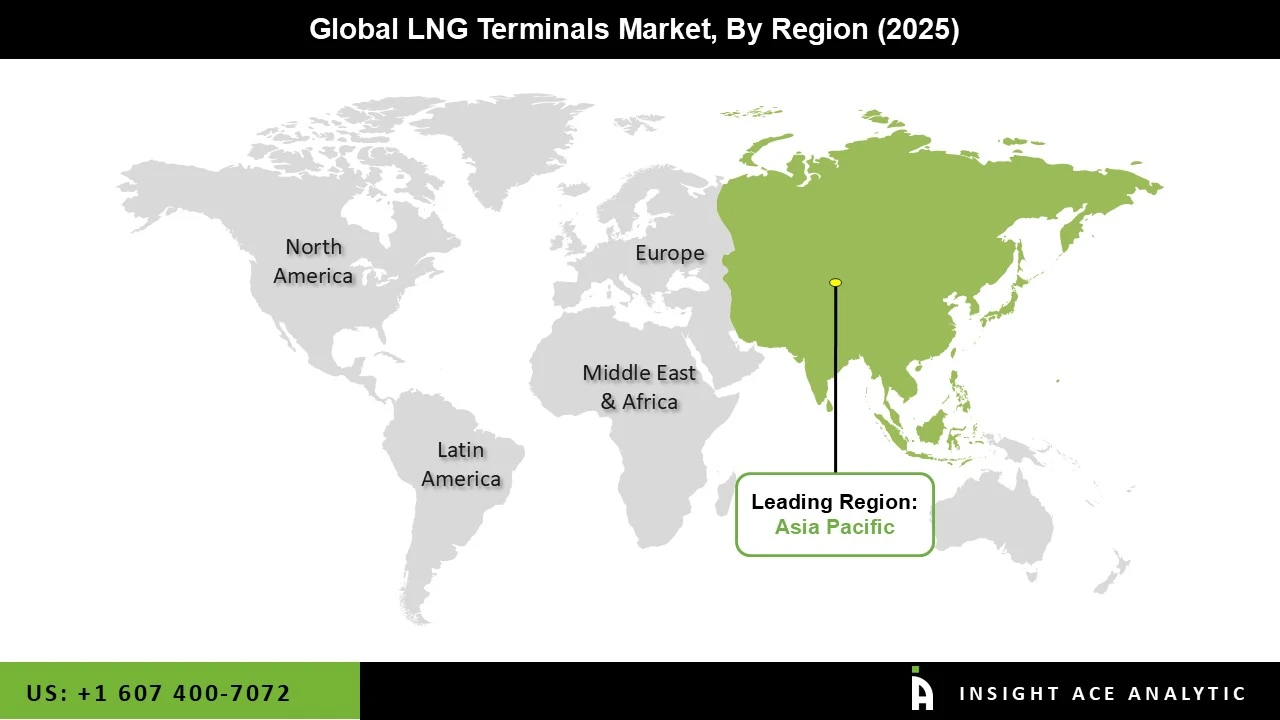
Why Asia Pacific is an Important Market for LNG Terminals Market
Asia Pacific is an important market for LNG terminals, supported by substantial natural gas use, established import infrastructure, and continuing investment in energy security. Countries like China, Japan, South Korea, and India depend on LNG imports for power, manufacturing, and other industries. Investments in regasification, terminal expansions, floating storage and regasification units, and pipelines are helping these countries strengthen their gas supply. Meanwhile, major regional LNG exporters, such as Australia and Malaysia, remain important suppliers to global markets. Growing energy demand, efforts to diversify fuel sources, and the need for reliable gas transport and storage are creating new opportunities for LNG terminal operators, project developers, and technology providers in the region.
Key Development
• In June 2026, Sempra Infrastructure announced that its ECA LNG Phase 1 project in Ensenada, Mexico, had achieved first LNG production during commissioning. The 3.25-million-tonne-per-annum facility is designed to export North American natural gas to international markets, particularly across the Pacific Basin.
• In September 2026, Cheniere Energy announced substantial completion of the Corpus Christi Liquefaction Stage 3 project in Texas. The project added seven liquefaction trains and increased production capacity across the company’s two U.S. Gulf Coast facilities to approximately 56 million tonnes per annum, strengthening its LNG export capabilities.
LNG Terminals Market Report Scope:
| Report Attribute | Specifications |
| Growth Rate CAGR | CAGR of 9.4% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2022 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | By Terminal Type, Infrastructure Configuration, Terminal Capacity / Scale and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; France; Italy; Spain; South Korea; Southeast Asia |
| Competitive Landscape | QatarEnergy LNG, Cheniere Energy, Venture Global, Sempra Infrastructure, Shell plc, TotalEnergies SE, ADNOC Gas, Woodside Energy Group, PETRONAS, Freeport LNG, Nigeria LNG, Sonatrach, Petronet LNG, Enagás, Korea Gas Corporation, JERA, Gate terminal, Snam, GAIL (India) Limited, Pertamina, Fluxys, PipeChina, Excelerate Energy, Höegh Evi, Golar LNG, New Fortress Energy, BW LNG, Mitsui O.S.K. Lines, Karpowership, Deutsche ReGas, AG&P LNG / Nebula Energy, H-Energy, Bechtel, Technip Energies, Chiyoda Corporation, Saipem, KBR, Air Products, Chart Industries, Baker Hughes, Linde Engineering, Samsung Heavy Industries. |
| Customization Scope | Free customization report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customized to your particular study requirements. |
Market Segmentation:
LNG Terminals Market by Product Type -
• Liquefaction & Export Terminals
o Onshore Liquefaction / Export Terminals
o Floating Liquefaction
• Regasification & Import Terminals
o Onshore Regasification / Import Terminals
o Floating Storage & Regasification
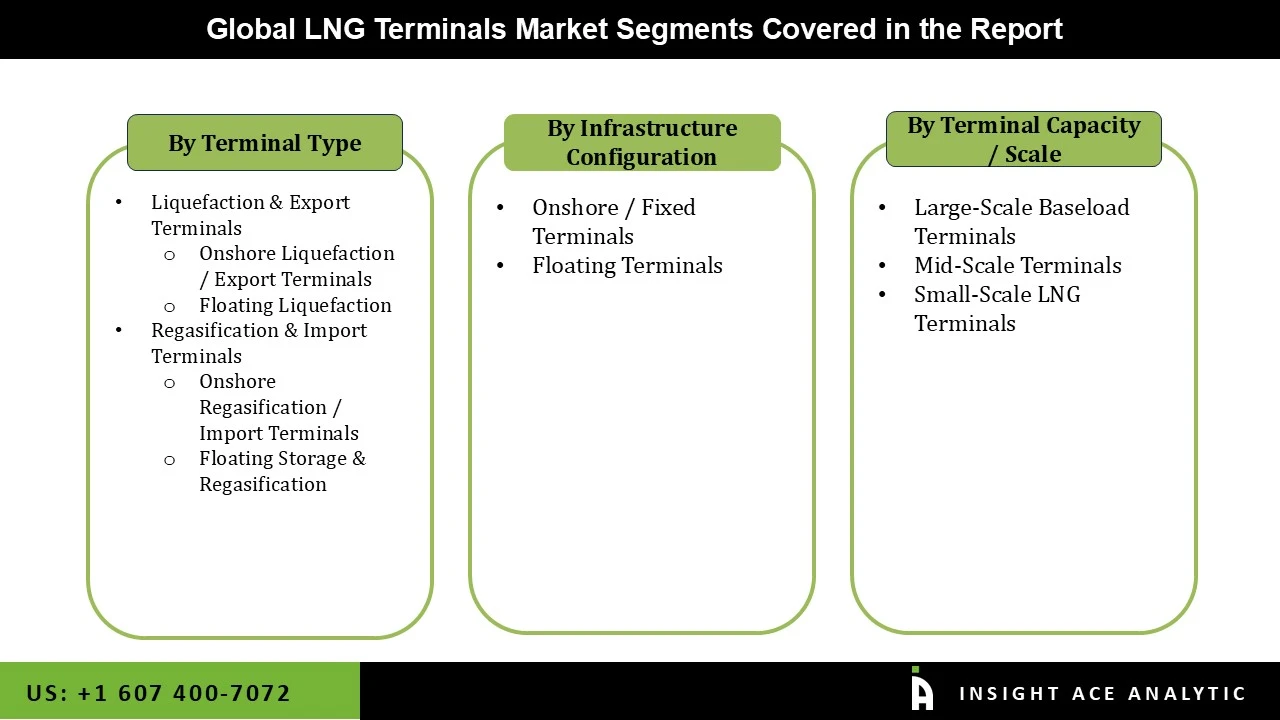
LNG Terminals Market by Infrastructure Configuration-
• Onshore / Fixed Terminals
• Floating Terminals
LNG Terminals Market by Terminal Capacity / Scale -
• Large-Scale Baseload Terminals
• Mid-Scale Terminals
• Small-Scale LNG Terminals
LNG Terminals Market by Region-
North America-
• The US
• Canada
• Mexico
Europe-
• Germany
• The UK
• France
• Italy
• Spain
• Rest of Europe
Asia-Pacific-
• China
• Japan
• India
• South Korea
• South East Asia
• Rest of Asia Pacific
Latin America-
• Brazil
• Argentina
• Rest of Latin America
Middle East & Africa-
• GCC Countries
• South Africa
• Rest of Middle East and Africa
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
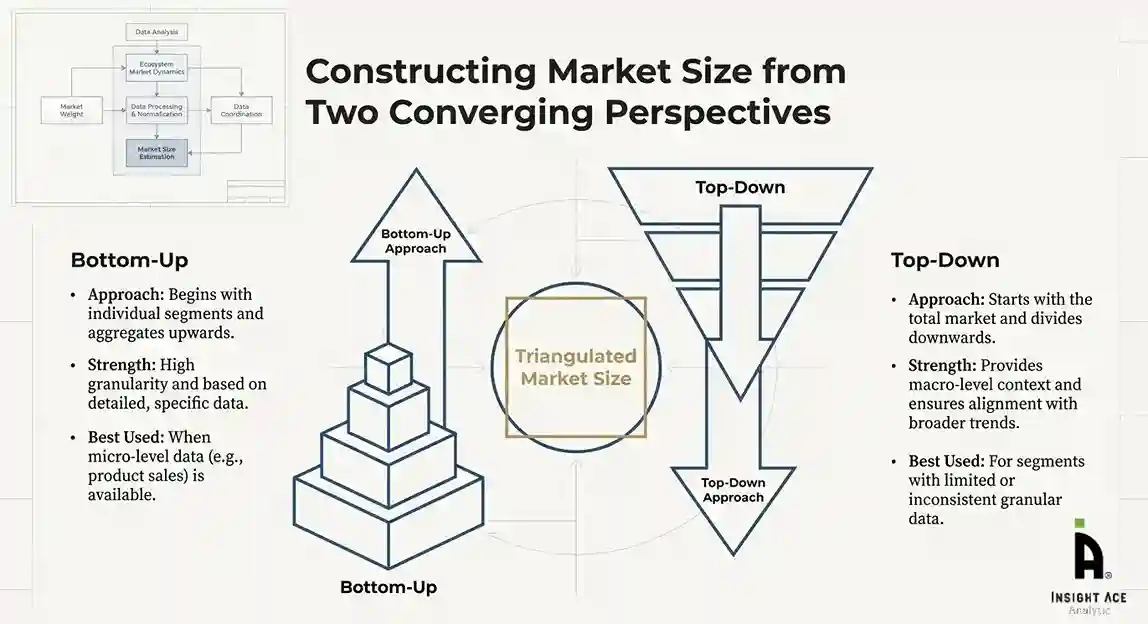
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
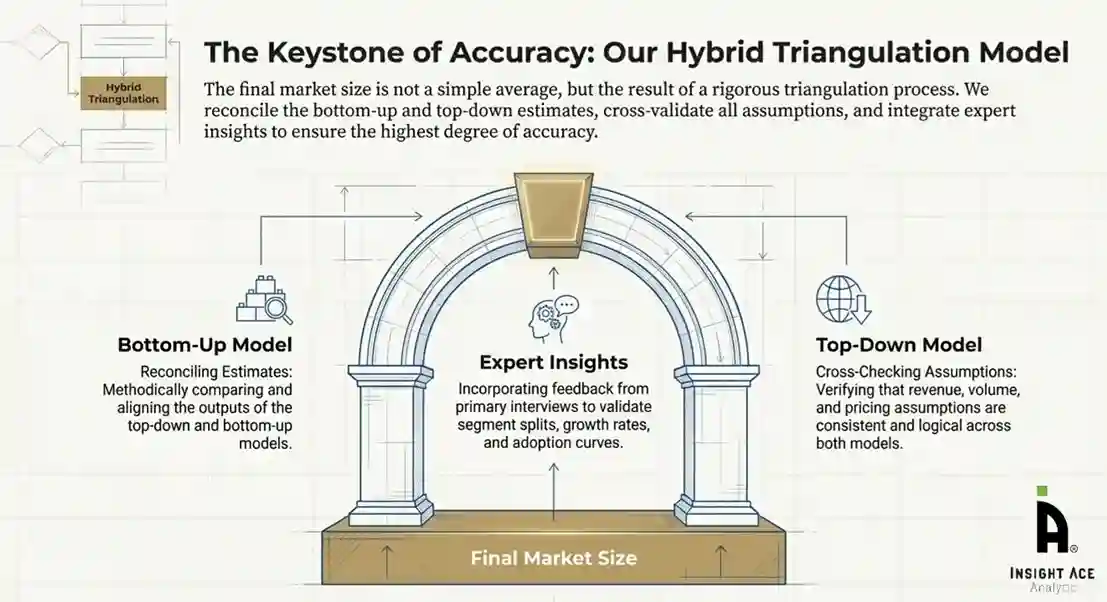
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
LNG Terminals Market is estimated to grow with a 9.4% CAGR during the forecast period for 2026 to 2035.
QatarEnergy LNG, Cheniere Energy, Venture Global, Sempra Infrastructure, Shell plc, TotalEnergies SE, ADNOC Gas, Woodside Energy Group, PETRONAS, Freeport LNG, Nigeria LNG, Sonatrach, Petronet LNG, Enagás, Korea Gas Corporation, JERA, Gate terminal, Snam, GAIL (India) Limited, Pertamina, Fluxys, PipeChina, Excelerate Energy, Höegh Evi, Golar LNG, New Fortress Energy, BW LNG, Mitsui O.S.K. Lines, Karpowership, Deutsche ReGas, AG&P LNG / Nebula Energy, H-Energy, Bechtel, Technip Energies, Chiyoda Corporation, Saipem, KBR, Air Products, Chart Industries, Baker Hughes, Linde Engineering, Samsung Heavy Industries.
LNG Terminals Market is segmented into By Terminal Type, Infrastructure Configuration, Terminal Capacity / Scale and By Region.
Asia Pacific region is leading the LNG Terminals Market.