Polysilicon Market Size, Share, Trend, Revenue Report 2026 to 2035
What is Polysilicon Market?
Global Polysilicon Market Size is valued at USD 17.08 Bn in 2025 and is predicted to reach USD 53.03 Bn by the year 2035 at an 12.2% CAGR during the forecast period for 2026 to 2035.
Polysilicon Market Size, Share & Trends Analysis Distribution by Production Process (Siemens (TCS-CVD), Fluidized Bed Reactor (Silane-FBR), Upgraded Metallurgical-Grade (UMG)), by End-User Industry (Solar Photovoltaics, Electronics and Semiconductors) and Segment Forecasts, 2026 to 2035.
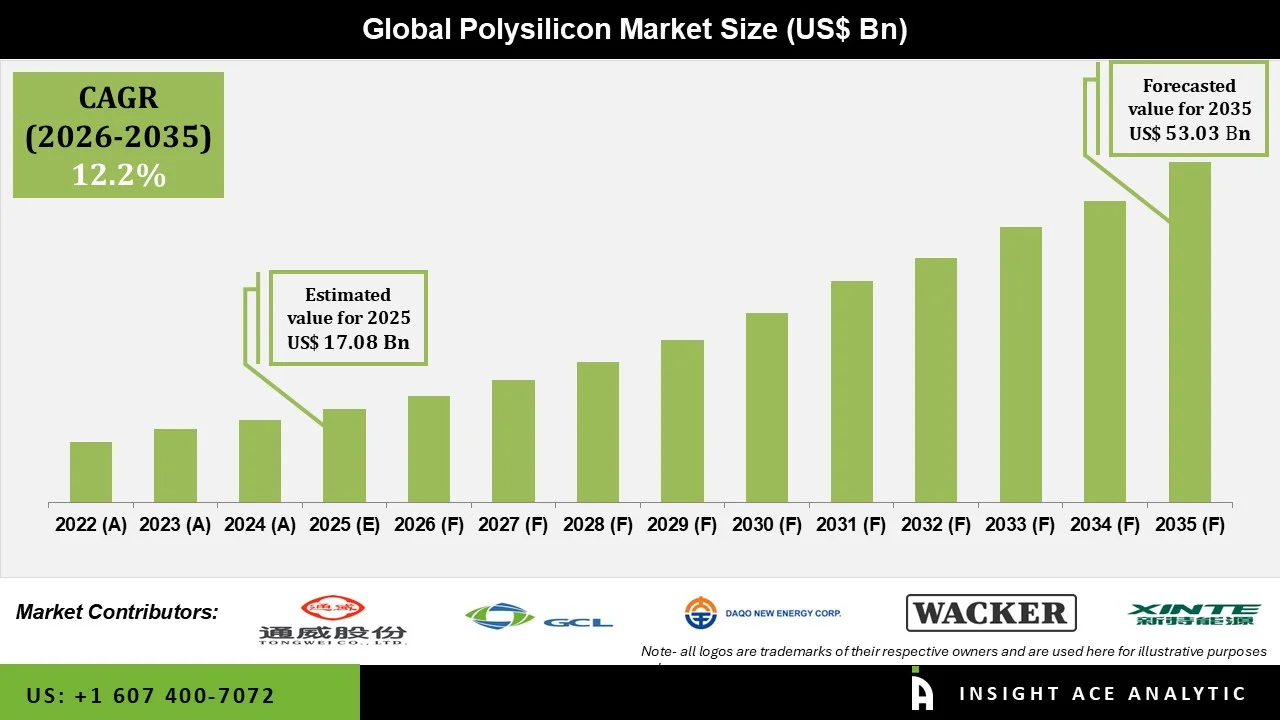
Polysilicon is becoming an increasingly important material in the global renewable energy and semiconductor industries, driven largely by the continued expansion of solar photovoltaic (PV) installations and rising demand for advanced electronic devices. Polysilicon is a highly purified form of silicon that serves as a key raw material for manufacturing solar cells, wafers, and semiconductor components. As countries increase investments in renewable energy, expand solar power capacity, and strengthen domestic semiconductor manufacturing, demand for high-purity polysilicon is continuing to grow. The material plays an important role in supporting the global transition toward cleaner energy while also meeting the requirements of the rapidly expanding electronics industry.
The solar photovoltaic industry is a key reason for the rising demand for polysilicon. More utility-scale solar farms, rooftop systems, and distributed solar projects are being installed, which keeps demand for solar-grade polysilicon steady. Government incentives, renewable energy goals, lower solar technology costs, and the push to use less fossil fuel are all driving new investments in solar power. At the same time, better solar cell technology means high-quality, pure polysilicon is more
important than ever. Manufacturers are increasing production and improving their processes to keep up with the needs of the solar PV supply chain.
Technological developments are further influencing the polysilicon market. Manufacturers are adopting advanced production technologies such as the Siemens process and fluidised bed reactor (FBR) technology to improve production efficiency, purity, and cost competitiveness. The Siemens process remains widely used to produce high-purity polysilicon, while FBR technology offers potential advantages in continuous production and energy efficiency. Upgraded metallurgical-grade (UMG) silicon also represents an alternative production approach for specific applications. Ongoing improvements in purification, energy consumption, production yields, and manufacturing processes are helping producers meet changing requirements from solar and semiconductor customers.
Developments across the global solar and semiconductor supply chains also influence the polysilicon market. Manufacturers are increasing production capacity, entering long-term supply agreements, improving manufacturing efficiency, and investing in new facilities to strengthen their market position. Major producers are also focusing on reducing production costs and improving energy efficiency because polysilicon manufacturing can be energy-intensive. Access to reliable and competitively priced electricity is therefore an important consideration for producers when selecting production locations and expanding capacity. Even with these opportunities, the polysilicon industry faces some challenges. Price swings, supply and demand imbalances, high energy needs, raw material shortages, and changes in production capacity can all impact the market. The industry is also affected by shifts in trade policies, tariffs, government rules, and supply chain disruptions.
Environmental issues are becoming more important for polysilicon makers. Because producing polysilicon uses a lot of electricity, companies are looking for ways to cut energy use and lower carbon emissions. Using renewable energy, making production more efficient, and investing in cleaner technologies can help reduce the environmental impact. These steps matter more now as solar manufacturers and customers pay closer attention to the carbon footprint and sustainability of their supply chains.
Competitive Landscape
Which are the Leading Players in the Polysilicon Market ?
- Tongwei Co. Ltd.
- GCL Technology Holdings
- Daqo New Energy Corp.
- Wacker Chemie AG
- Xinte Energy Co. Ltd.
- East Hope Group
- OCI Company Ltd.
- Hemlock Semiconductor
- REC Silicon ASA
- Asia Silicon (Qinghai) Co. Ltd.
Driver
Growing Solar PV Installations and Rising Semiconductor Demand are Driving the Polysilicon Market
The global polysilicon market is growing mainly because more people are using solar photovoltaic (PV) technology and the semiconductor industry is expanding. Polysilicon is essential for making solar cells and semiconductor wafers, so its demand rises with advances in renewable energy and electronics. Many governments are investing more in solar power and setting renewable energy goals to rely less on traditional energy sources. As more solar farms, rooftop systems, and distributed solar projects are built, the need for solar-grade polysilicon continues to increase. Investments in semiconductor manufacturing are also boosting demand for high-purity polysilicon. As artificial intelligence, data centers, electric vehicles, consumer electronics, and advanced computing grow, the need for semiconductor components increases. Manufacturers are building new facilities and expanding current ones to keep up. As both the solar and semiconductor industries grow, the demand for high-quality polysilicon is expected to keep rising, helping the market expand overall.
Restraint/Challenge
High Energy Consumption, Price Volatility, and Supply Chain Risks Can Limit Market Expansion
The polysilicon industry faces challenges that can slow market growth, especially high energy use and price swings. Making polysilicon, especially with traditional methods, uses a lot of electricity. When electricity prices change, production costs and profits are affected. To manage these issues and lower environmental impact, manufacturers are working to use energy more efficiently and switch to renewable energy sources. Polysilicon prices can change based on demand for solar modules, how much is produced, inventory, and overall supply and demand. If manufacturing grows too quickly, there can be too much supply, which lowers prices. On the other hand, supply problems can push prices up. Since much of the production is in a few countries, there are supply-chain risks for solar and semiconductor companies. Trade rules, tariffs, and political changes can also affect global supply chains. To manage these risks, manufacturers are improving efficiency, diversifying supply chains, signing long-term contracts, and investing in production facilities in different locations.
Solar Photovoltaics Segment is Expected to Witness Strong Growth in the Polysilicon Market
The solar photovoltaics segment is expected to account for a significant share of the global polysilicon market due to the continued expansion of solar power generation worldwide. Polysilicon is an essential raw material for producing crystalline silicon solar cells and wafers, so demand for the material is closely tied to solar PV installations. The growing deployment of utility-scale solar projects, rooftop systems, and distributed solar generation is driving strong demand for solar-grade polysilicon. Governments and energy companies are investing in renewable energy projects to increase clean electricity generation and reduce carbon emissions. Falling solar technology costs and improvements in solar cell efficiency are also encouraging wider adoption of photovoltaic systems. In addition, manufacturers across the solar value chain are expanding production capacity to meet growing global demand. These developments are expected to support continued demand for polysilicon from solar manufacturers and maintain the solar PV industry’s important role in the overall market.
Electronics and Semiconductors Segment is Expected to Witness Strong Growth in the Polysilicon Market
The electronics and semiconductor segment is expected to grow quickly as more advanced electronic devices and semiconductor parts are needed. High-purity polysilicon is essential for making semiconductor wafers, which are used in integrated circuits and many electronic products. Fast growth in artificial intelligence, cloud computing, data centers, electric vehicles, smartphones, and advanced computing is driving up global demand for semiconductors. Governments and big tech companies are investing in local semiconductor manufacturing to make supply chains stronger and rely less on foreign production. New factories and wafer plants will likely increase demand for high-purity polysilicon. As semiconductor technology improves and more electronic uses appear, the need for high-quality silicon materials should keep growing, giving polysilicon producers more opportunities.
Why Asia Pacific Led the Polysilicon Market?
Asia Pacific represents a leading region in the global polysilicon market, supported by its large solar manufacturing base, expanding renewable energy capacity, established semiconductor supply chain, and significant polysilicon production capabilities. China plays a particularly important role in the regional market due to its extensive presence across the solar photovoltaic value chain, including polysilicon, wafers, solar cells, and modules.
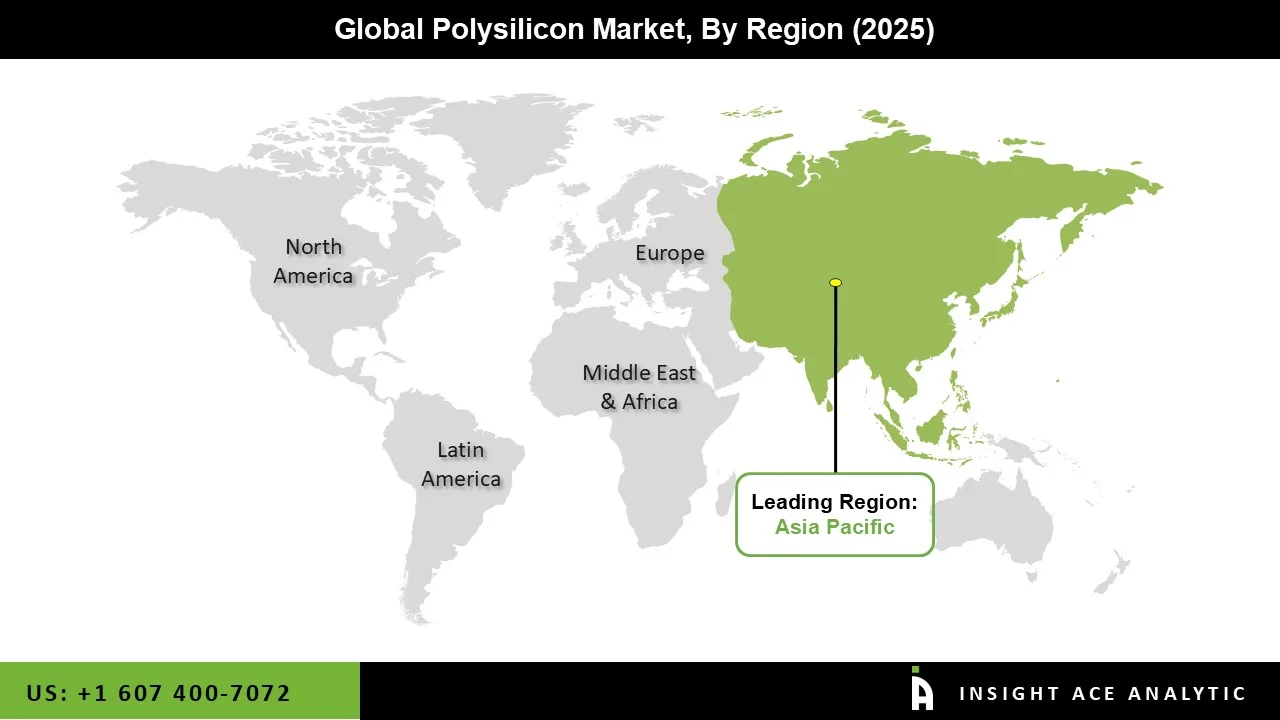
The region also includes major manufacturing and technology markets such as India, Japan, and South Korea. The rapid development of solar power projects across Asia Pacific is generating substantial demand for solar-grade polysilicon. China continues to expand renewable energy capacity, while India is increasing investments in domestic solar manufacturing and clean energy infrastructure. Japan and South Korea also have established electronics and semiconductor industries that contribute to regional demand for high-purity silicon materials. Asia Pacific's strong manufacturing base, robust production infrastructure, rising renewable energy investment, and many major polysilicon producers help maintain the region's leading market position.
Key Developments
• In May 2026, GCL Technology Holdings announced a comprehensive strategic transformation from a granular-silicon-focused business toward a global multi-product new energy materials platform. The company plans to build on its FBR granular silicon capabilities while expanding into silicon-, lithium-, and carbon-based materials, supporting diversification and longer-term growth.
• In March 2026, Tongwei also continued advancing next-generation photovoltaic technologies, including perovskite-silicon tandem cells. The company reported progress toward commercial-scale tandem cell and module development, indicating continued investment beyond conventional crystalline-silicon PV technologies.
Polysilicon Market Report Scope:
| Report Attribute | Specifications |
| Market size value in 2025 | USD 17.08 Bn |
| Revenue forecast in 2035 | USD 53.03 Bn |
| Growth Rate CAGR | CAGR of 12.2% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2021 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | Production Process, End Use Industry and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; France; Italy; Spain; South Korea; Southeast Asia |
| Competitive Landscape | Tongwei Co. Ltd., GCL Technology Holdings, Daqo New Energy Corp., Wacker Chemie AG, Xinte Energy Co. Ltd., East Hope Group, OCI Company Ltd., Hemlock Semiconductor, REC Silicon ASA, Asia Silicon (Qinghai) Co. Ltd. |
| Customization Scope | Free customisation report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customised to your particular study requirements. |
Segmentations Polysilicon Market:
Polysilicon Market by Production Process -
- Siemens (TCS-CVD)
- Fluidized Bed Reactor (Silane-FBR)
- Upgraded Metallurgical-Grade (UMG)
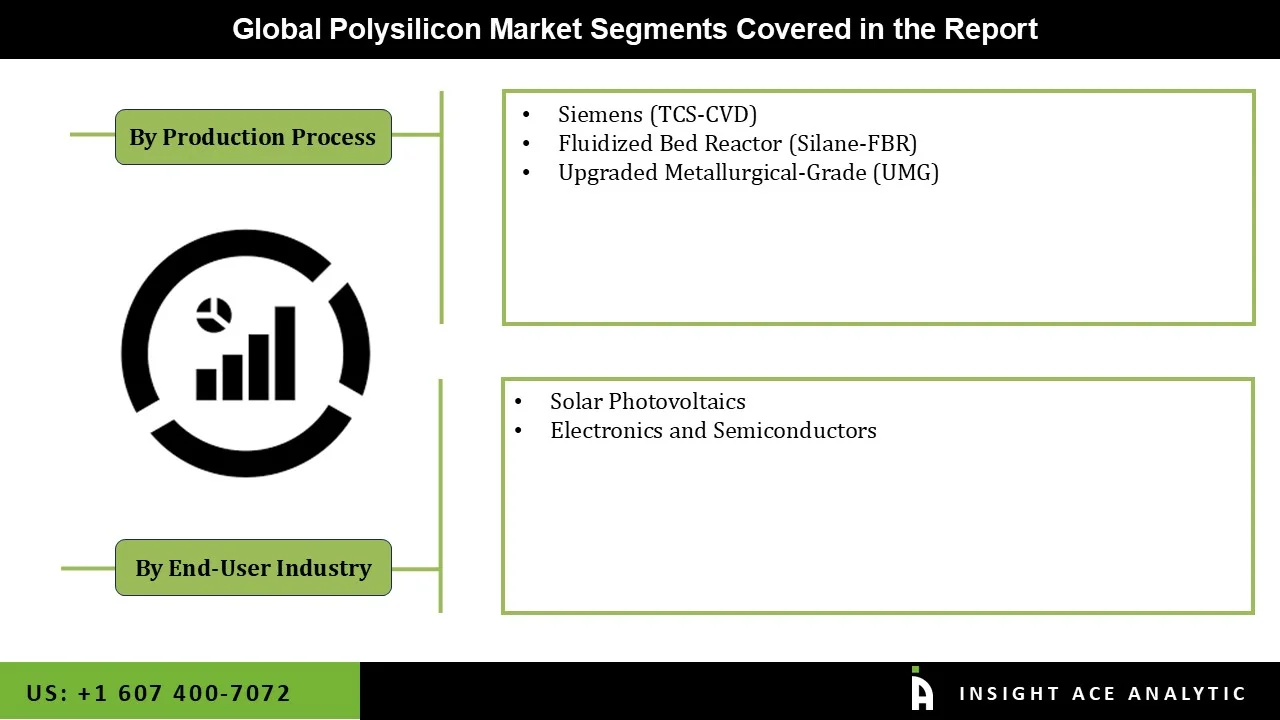
Polysilicon Market by End-User Industry -
- Solar Photovoltaics
- Electronics and Semiconductors
Polysilicon Market by Region-
- North America-
- The US
- Canada
- Europe-
- Germany
- The UK
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific-
- China
- Japan
- India
- South Korea
- South East Asia
- Rest of Asia Pacific
- Latin America-
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Middle East and Africa-
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
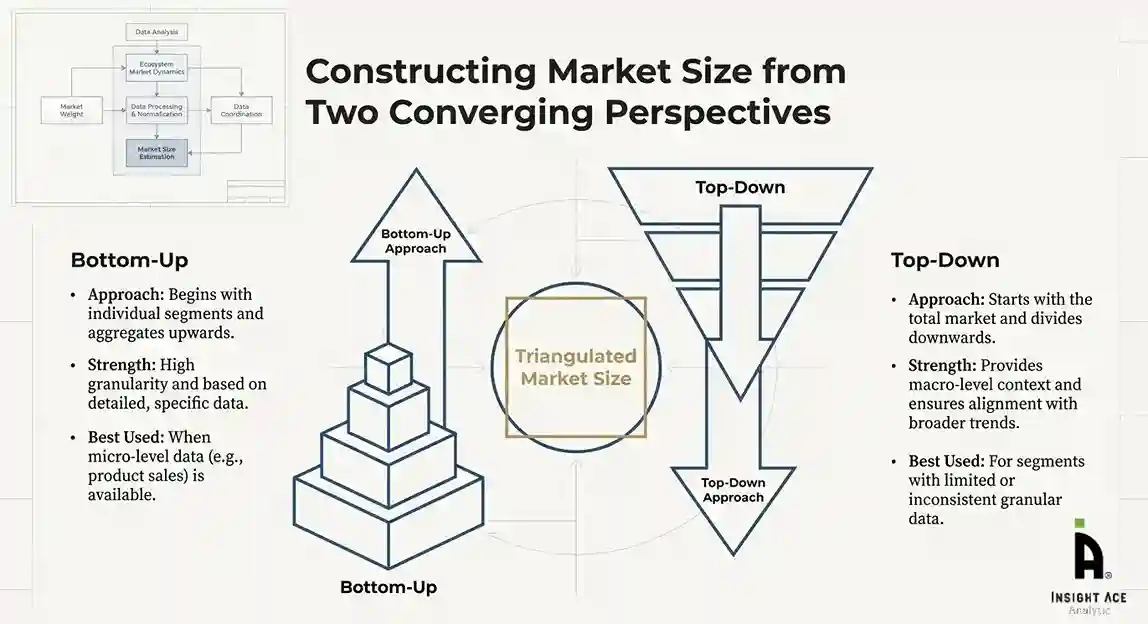
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
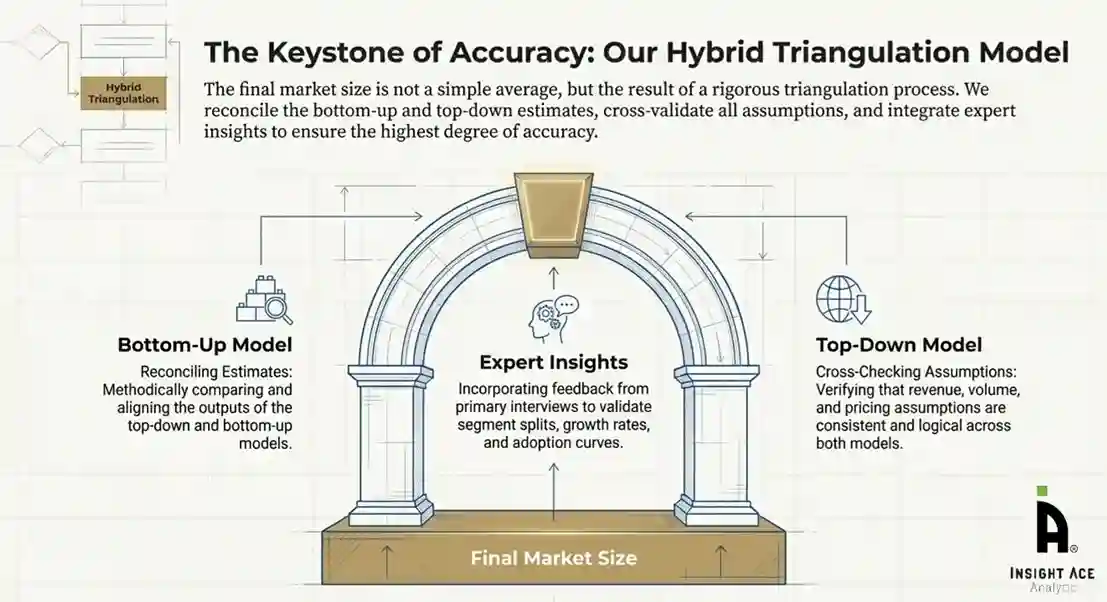
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
Polysilicon Market Size is valued at USD 17.08 Bn in 2025 and is predicted to reach USD 53.03 Bn by the year 2035
The Polysilicon Market is expected to grow at a 12.2% CAGR during the forecast period for 2026 to 2035
Tongwei Co. Ltd., GCL Technology Holdings, Daqo New Energy Corp., Wacker Chemie AG, Xinte Energy Co. Ltd., East Hope Group, OCI Company Ltd., Hemlock Semiconductor, REC Silicon ASA, Asia Silicon (Qinghai) Co. Ltd. and Others.
Polysilicon Market is segmented into Production Process, End Use Industry and Other.
Asia Pacific region is leading the Polysilicon Market.