High Bandwidth Flash (HBF) Market Size, Share, Trend Report 2026 to 2035
What is High Bandwidth Flash (HBF) Market Size?
High Bandwidth Flash (HBF) Market likely to witness the growth at a 48.0% CAGR during the forecast period for 2026 to 2035.
High Bandwidth Flash (HBF) Market Size, Share & Trends Analysis Distribution by HBF Value Layer / Device Component (HBF Memory Stack, HBF Logic Base Die, HBF Controller & Host-Interface Silicon, HBF-Specific Advanced Packaging, Interposer & Assembly), by Generation / Performance Grade (Gen 1 (≤512 GB · ~1.6 TB/s), Gen 2 (≤1 TB · >2 TB/s), Gen 3 (≤1.5 TB · 3.2 TB/s)), by Integration / Deployment Mode (HBF + HBM Co-Package, HBF-Dominant Accelerator Memory, Edge & On-Device HBF), by Accelerator / Host Type (Merchant Data-Center AI GPUs, TPUs & Custom AI ASICs, Other AI Accelerators & Inference SoCs), by Deployment Type (Hyperscale & Neocloud, Enterprise & On-Premises, Sovereign & Government, Edge & Embedded) and Segment Forecasts, 2026 to 2035
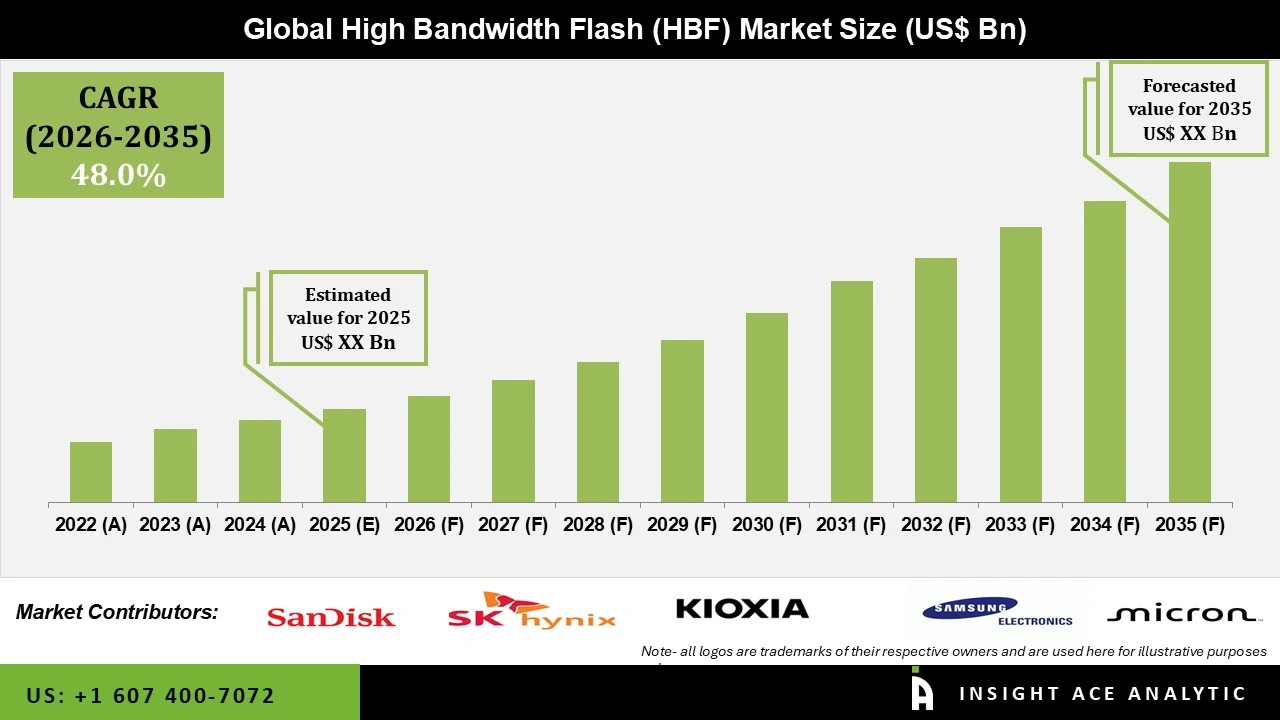
The High Bandwidth Flash (HBF) market is drawing more attention as AI workloads, high-performance computing, and data-heavy applications put extra strain on traditional memory and storage systems. As data centers handle bigger AI models and more complex tasks, there is a stronger demand for memory that offers high bandwidth, large capacity, efficient power use, and quick data access. HBF is becoming a promising option by combining high-capacity NAND flash with fast interfaces, dedicated logic, controllers, and advanced packaging. This market is now interesting to memory makers, semiconductor firms, AI accelerator developers, data center operators, and system providers who want to close the gap between computing power and available memory. HBF can help in situations where large amounts of data need to be accessed quickly, without relying only on more expensive high-bandwidth memory options.
New technology is playing a key role in shaping the High Bandwidth Flash (HBF) market. Better NAND flash, improved controller designs, faster host interfaces, and advanced packaging are helping companies build memory solutions with more capacity and higher bandwidth. The next generations of HBF are expected to offer even more capacity and faster data transfer, which will support demanding AI and accelerator tasks. Integrating HBF with HBM, AI GPUs, custom ASICs, and other accelerator platforms is also a major focus. HBF could act as an extra memory layer in advanced computing systems, boosting total memory and easing the load on existing high-bandwidth memory. At the same time, manufacturers are working to make these solutions more power-efficient, better at handling heat, more reliable, and denser as performance needs keep rising.
Even with its promise, the HBF market faces some challenges. HBF needs tight integration between NAND memory, logic, controllers, packaging, and host interfaces, which makes system design and manufacturing more complicated. It is technically tough to achieve high bandwidth while keeping latency low, saving power, managing heat, and ensuring reliable data transfer. Advanced packaging and interconnects can also raise manufacturing costs and require special production skills. The HBF ecosystem is still growing, and differences in accelerator designs, system setups, interfaces, and performance needs can make standardization harder. Competition from established memory types like HBM, along with better DRAM and high-performance storage, could also affect how quickly HBF is adopted.
Despite these challenges, the long-term outlook for the High Bandwidth Flash (HBF) Market remains positive. The rapid expansion of AI infrastructure, hyperscale data centres, custom AI accelerators, and high-performance computing is expected to create continued demand for memory technologies that can deliver both high capacity and high data-transfer performance. HBF could become particularly valuable in applications where large memory capacity is required alongside high bandwidth and cost-efficient system scaling. Further advances in NAND technology, controller design, advanced packaging, HBF–HBM integration, and accelerator-memory architectures are expected to improve the performance and commercial potential of these solutions. As AI systems continue to evolve and memory requirements increase, HBF is positioned to become an important emerging technology within the broader high-performance memory and AI computing ecosystem.
Competitive Landscape
Which are the Leading Players in the High Bandwidth Flash (HBF) Market?
• SanDisk Corporation
• SK hynix Inc.
• Kioxia Corporation
• Samsung Electronics Co., Ltd.
• Micron Technology, Inc.
• NVIDIA Corporation
• Phison Electronics Corp.
• Marvell Technology, Inc.
• ScaleFlux, Inc.
• Solidigm (SK hynix NAND Product Solutions Corp.)
• Google LLC
• Tenstorrent Inc.
• Open Compute Project Foundation
• DDN
• Dell Technologies
• Hewlett Packard Enterprise
• IBM
• NetApp
• VAST Data
• WEKA
• Supermicro
• QCT
• AIC
• TSMC
• ASE Technology
• Amkor Technology
• Broadcom
• Astera Labs
• AMD
Market Dynamics
Driver
Rising Demand for High-Capacity, High-Bandwidth Memory for AI and Data-Centric Computing
The rapid growth of artificial intelligence, high-performance computing, cloud services, and data-intensive workloads is increasing demand for memory technologies that can provide both high bandwidth and greater capacity. Modern AI accelerators and data-center systems process increasingly large datasets and models, creating pressure on conventional memory architectures and increasing the need for additional high-performance memory solutions. HBF is gaining attention as an emerging architecture that can combine the capacity advantages of NAND flash with high-speed interfaces, dedicated logic, controller technologies, and advanced packaging. The ability to support large amounts of data while maintaining high data-transfer rates is creating opportunities for HBF across AI infrastructure, accelerator systems, and next-generation data-center platforms.
Restraint / Challenge
High Architectural Complexity, Advanced Packaging Requirements, and Competition from Established Memory Technologies
Even with its promise, the High Bandwidth Flash (HBF) market faces both technical and business challenges. Building HBF systems means carefully combining NAND memory stacks, logic base dies, controllers, host interfaces, and advanced packaging. Keeping bandwidth high while managing latency, power use, heat, signal quality, and reliability makes development complicated. The need for advanced packaging and assembly can also raise manufacturing costs and demand specialized skills. HBF also has to compete with established memory technologies like HBM and other high-performance options. Differences in accelerator designs, host interfaces, workloads, and system setups could slow down standardization and wider use.
HBF Memory Stack Segment is Expected to Drive the High Bandwidth Flash (HBF) Market
The HBF Memory Stack segment is likely to become a key part of the market as more people look for higher-capacity memory to support AI and data-heavy tasks. Better NAND flash density and stacking methods let manufacturers fit more memory into smaller spaces. HBF memory stacks can offer much more capacity than traditional high-bandwidth memory, which is useful for applications that need quick access to large datasets and AI models. Ongoing improvements in NAND performance, stack design, power efficiency, and reliability should help drive adoption in advanced accelerator and data center systems.
Gen 2 Segment is Expected to Drive the High Bandwidth Flash (HBF) Market
The Gen 2 (≤1 TB, >2 TB/s) segment is set to grow as HBF technology moves toward higher capacity and faster speeds. Gen 2 solutions are designed to meet the rising needs of AI accelerators and data centers that want more memory without depending only on traditional high-bandwidth memory. Better controller technology, faster interfaces, improved NAND performance, and advanced packaging are expected to help the shift to higher-performing HBF. As AI models and workloads get bigger and more complex, Gen 2 designs could offer a good mix of capacity, speed, power efficiency, and cost.
HBF-Dominant Accelerator Memory Segment is Expected to Drive the High Bandwidth Flash (HBF) Market
The HBF-Dominant Accelerator Memory segment is expected to become an important application area as AI accelerator architectures evolve. Modern GPUs, custom AI ASICs, and other accelerators require increasingly large memory pools to support model training, inference, and high-throughput data processing. HBF could provide a high-capacity memory layer that complements or, in selected architectures, reduces dependence on conventional memory solutions. The development of HBF-specific interfaces, controllers, and packaging technologies is expected to improve integration with accelerator platforms. Increasing demand for scalable AI infrastructure from hyperscalers, neocloud providers, and enterprise data centers is likely to create further opportunities for HBF-dominant memory architectures.
Why North America Leads the High Bandwidth Flash (HBF) Market?
North America is expected to maintain a leading position in the High Bandwidth Flash (HBF) Market due to its strong AI, semiconductor, cloud computing, and data-center ecosystem. The region is home to major AI accelerator developers, hyperscalers, cloud infrastructure providers, semiconductor companies, and technology companies investing heavily in next-generation computing architectures. The rapid expansion of AI data centers and high-performance computing infrastructure is increasing demand for high-capacity and high-bandwidth memory solutions. Strong R&D capabilities, significant investment in AI infrastructure, and collaboration between semiconductor and computing companies are further supporting the development and potential adoption of HBF technologies.
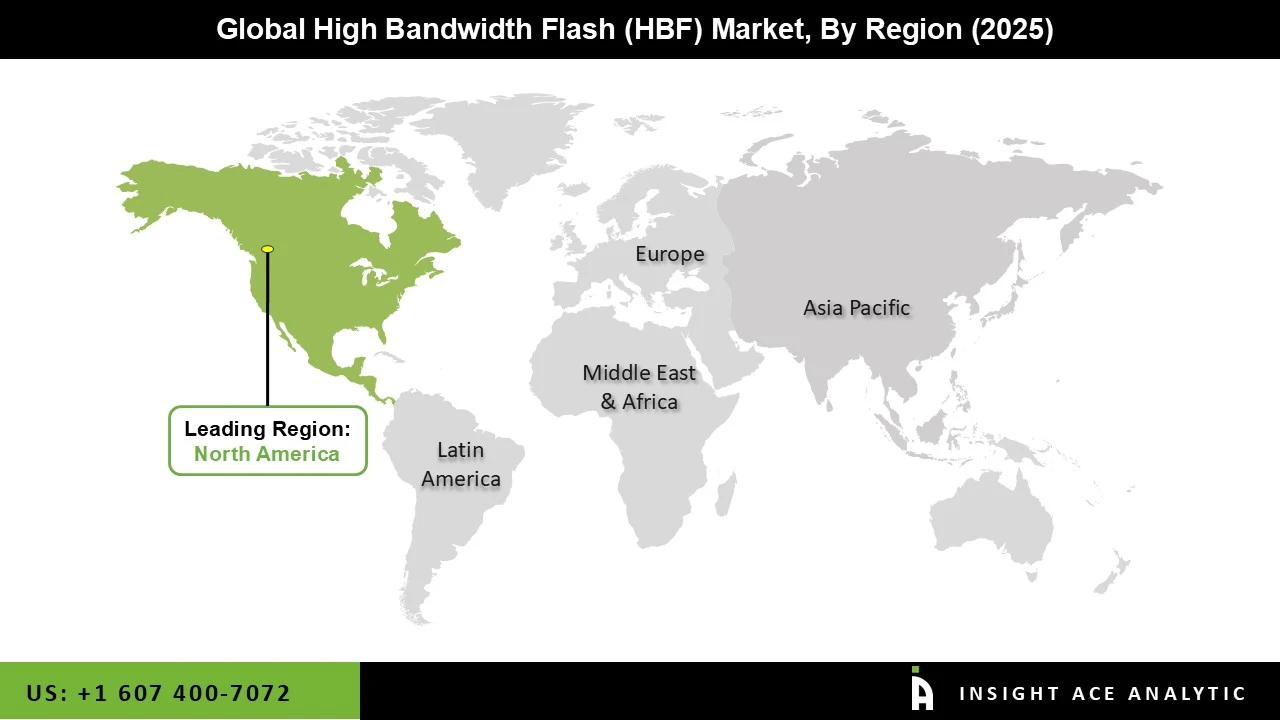
At the same time, Asia Pacific is expected to witness strong growth during the forecast period. The region has a highly developed semiconductor and memory manufacturing ecosystem, with major industry participants involved in NAND flash, advanced packaging, semiconductor fabrication, and electronic component production. Countries such as South Korea, Japan, China, Taiwan, and Singapore are investing in AI infrastructure, semiconductor manufacturing, advanced packaging, and high-performance computing. The presence of major memory manufacturers and semiconductor supply-chain companies gives Asia Pacific an important role in the development and commercialisation of HBF.
Key Developments-
• In January 2025, SanDisk Corporation continued advancing high-capacity NAND flash technologies and storage solutions designed to address the growing data requirements of AI, data centers, and high-performance computing. The company's focus on increasing NAND density, performance, and efficiency supports the development of higher-capacity memory architectures relevant to the emerging HBF market.
• In March 2025, Kioxia Corporation continued investing in next-generation BiCS FLASH and advanced flash-memory technologies aimed at AI, data-center, and enterprise workloads. These developments support the increasing demand for higher-density and higher-performance NAND architectures.
High Bandwidth Flash (HBF) Market Report Scope:
| Report Attribute | Specifications |
| Growth Rate CAGR | CAGR of 48.0% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2021 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | HBF Value Layer / Device Component, Generation / Performance Grade, Integration / Deployment Mode, Accelerator / Host Type, Deployment Type and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; France; Italy; Spain; South Korea; Southeast Asia |
| Competitive Landscape | SanDisk Corporation, SK hynix Inc., Kioxia Corporation, Samsung Electronics Co., Ltd., Micron Technology, Inc., NVIDIA Corporation, Phison Electronics Corp., Marvell Technology, Inc., ScaleFlux, Inc., Solidigm (SK hynix NAND Product Solutions Corp.), Google LLC, Tenstorrent Inc., Open Compute Project Foundation, DDN, Dell Technologies, Hewlett Packard Enterprise, IBM, NetApp, VAST Data, WEKA, Supermicro, QCT, AIC, TSMC, ASE Technology, Amkor Technology, Broadcom, Astera Labs, AMD. |
| Customization Scope | Free customisation report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customized to your particular study requirements. |
Market Segmentation:
High Bandwidth Flash (HBF) Market by HBF Value Layer / Device Component-
• HBF Memory Stack
• HBF Logic Base Die
• HBF Controller & Host-Interface Silicon
• HBF-Specific Advanced Packaging, Interposer & Assembly
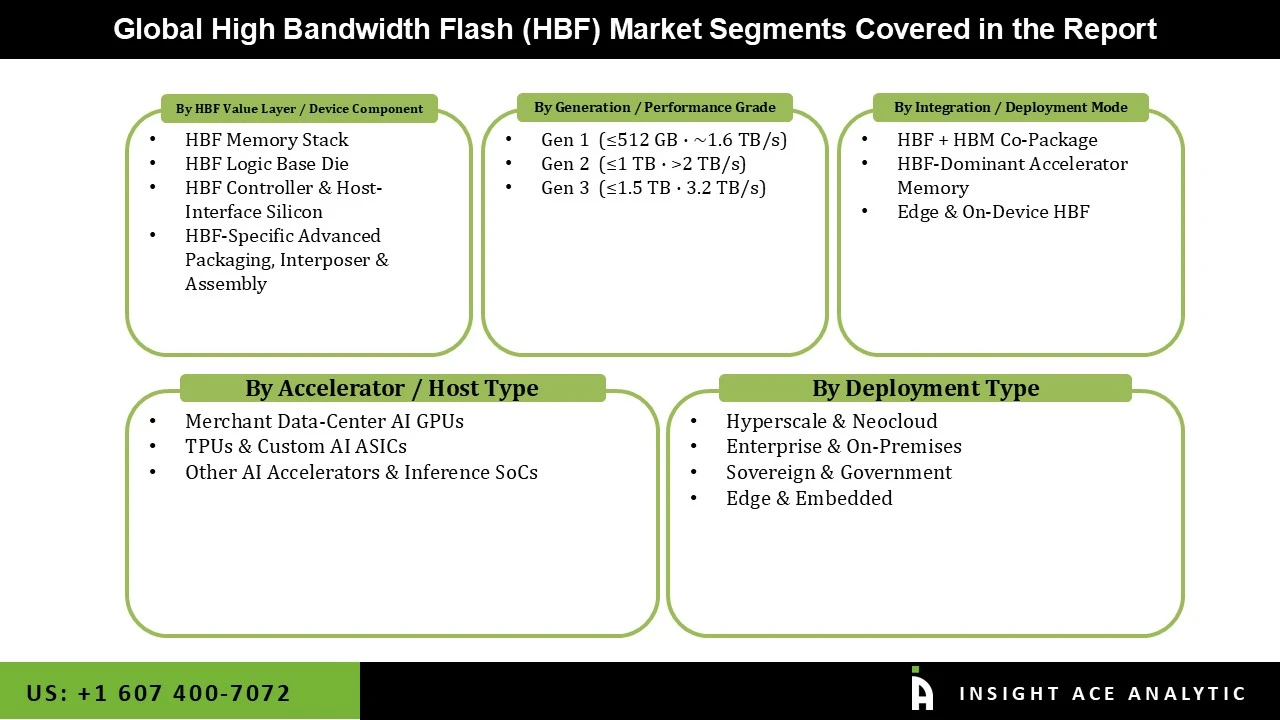
High Bandwidth Flash (HBF) Market By Generation / Performance Grade-
• Gen 1 (≤512 GB · ~1.6 TB/s)
• Gen 2 (≤1 TB · >2 TB/s)
• Gen 3 (≤1.5 TB · 3.2 TB/s)
High Bandwidth Flash (HBF) Market By Integration / Deployment Mode-
• HBF + HBM Co-Package
• HBF-Dominant Accelerator Memory
• Edge & On-Device HBF
High Bandwidth Flash (HBF) Market By Accelerator / Host Type-
• Merchant Data-Center AI GPUs
• TPUs & Custom AI ASICs
• Other AI Accelerators & Inference SoCs
High Bandwidth Flash (HBF) Market By Deployment Type-
• Hyperscale & Neocloud
• Enterprise & On-Premises
• Sovereign & Government
• Edge & Embedded
High Bandwidth Flash (HBF) Market by Region-
North America-
• The US
• Canada
Europe-
• Germany
• UK
• France
• Nordics
• Netherlands
• Switzerland
• Spain
• Italy
• Benelux
• Rest of Europe
Asia-Pacific-
• China
• Japan
• South Korea
• Australia
• India
• Rest of APAC
Latin America-
• Brazil
• Mexico
• Chile
• Rest of LatAm
Middle East & Africa-
• GCC
• South Africa
• Rest of MEA
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
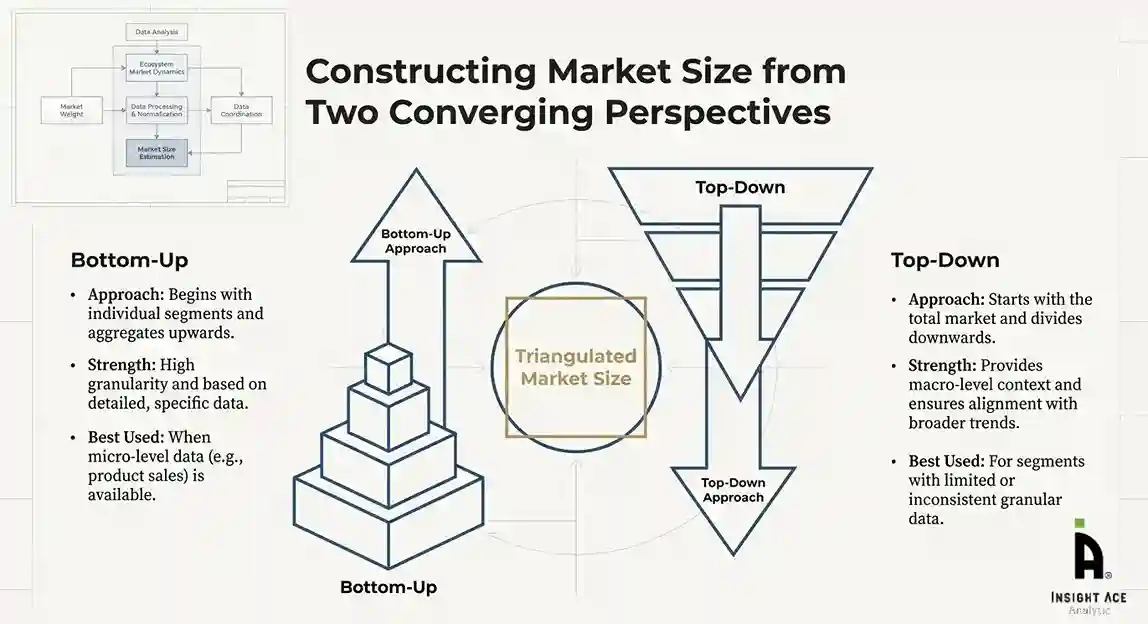
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
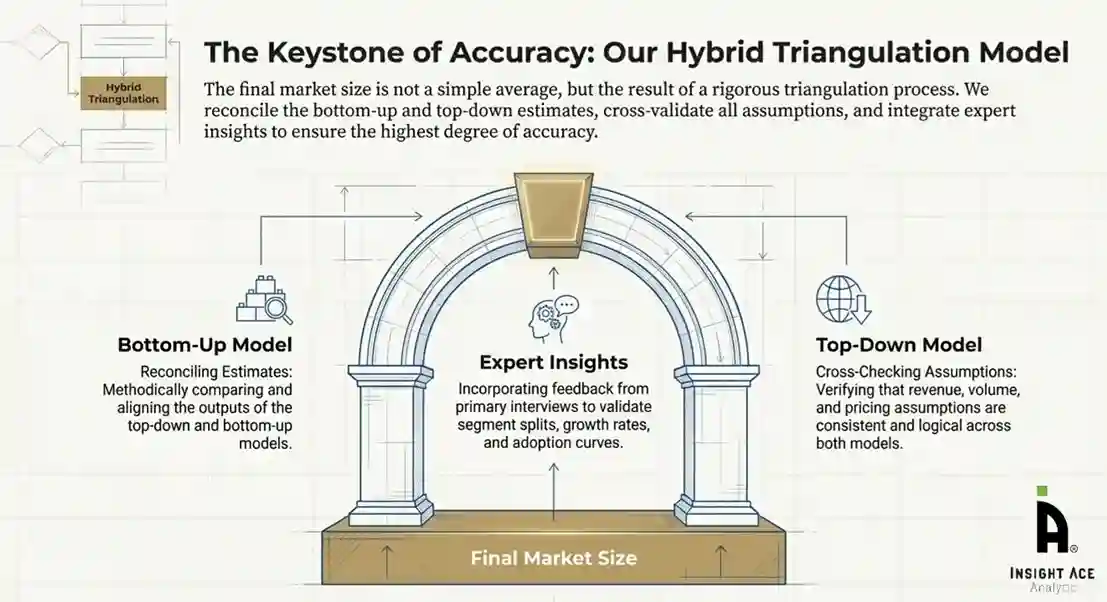
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
High Bandwidth Flash (HBF) Market likely to witness the growth at a 48.0% CAGR during the forecast period for 2026 to 2035.
SanDisk Corporation, SK hynix Inc., Kioxia Corporation, Samsung Electronics Co., Ltd., Micron Technology, Inc., NVIDIA Corporation, Phison Electronics Corp., Marvell Technology, Inc., ScaleFlux, Inc., Solidigm (SK hynix NAND Product Solutions Corp.), Google LLC, Tenstorrent Inc., Open Compute Project Foundation, DDN, Dell Technologies, Hewlett Packard Enterprise, IBM, NetApp, VAST Data, WEKA, Supermicro, QCT, AIC, TSMC, ASE Technology, Amkor Technology, Broadcom, Astera Labs, AMD.
High Bandwidth Flash (HBF) Market is segmented into HBF Value Layer / Device Component, Generation / Performance Grade, Integration / Deployment Mode, Accelerator / Host Type, Deployment Type and By Region
North America region is leading the High Bandwidth Flash (HBF) Market.