Creatine Ingredients Market Size, Share, Trend, Forecast Report 2026 to 2035
What is Creatine Ingredients Market Size?
Creatine Ingredients Market is predicted to grow at 8.7% CAGR during the forecast period for 2026 to 2035.
Creatine Ingredients Market Size, Share & Trends Analysis by Product Type (Creatine Monohydrate, Standard Powder, Micronized Powder, Specialty-Processed, Creatine Hydrochloride, Other Creatine Forms), by Application (Dietary Supplements, Sports Nutrition Supplements, Health & Wellness Supplements, Functional Foods & Beverages, Pharmaceutical, Medical Nutrition & Other Applications), by Distribution Channel (Direct Sales, Distributors & Traders) and Segment Forecasts, 2026 to 2035
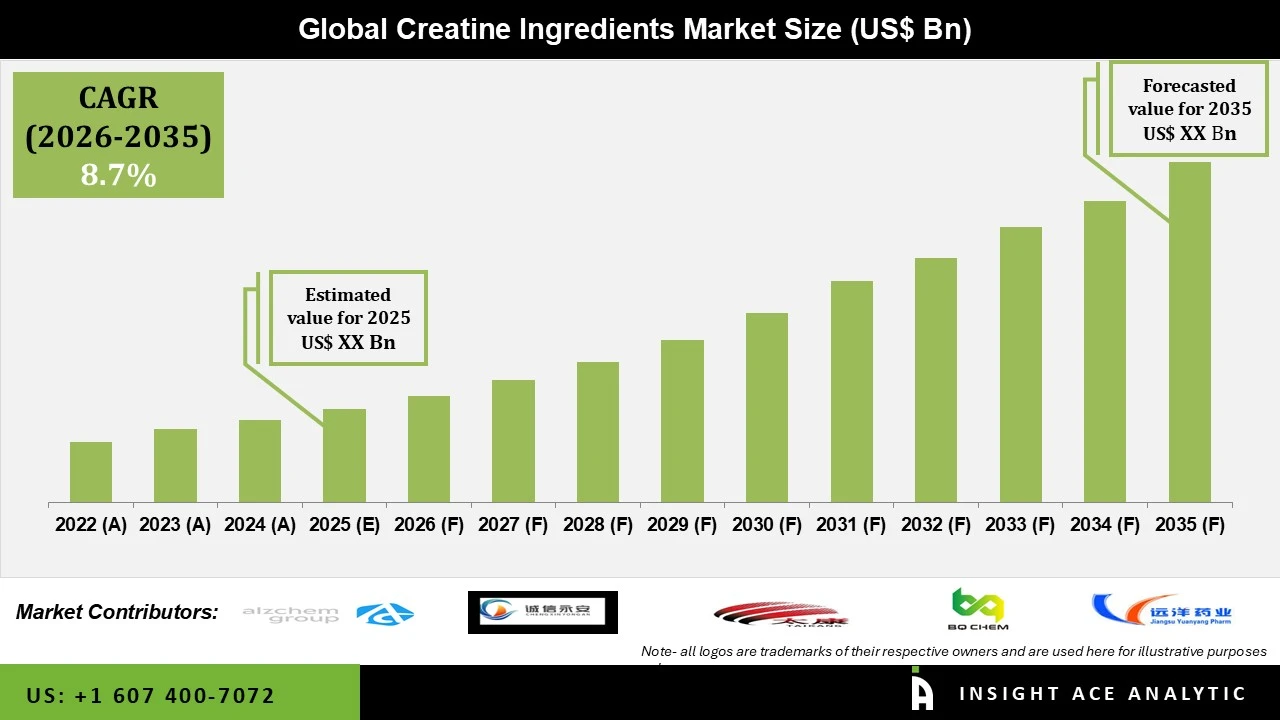
Creatine is widely used to support muscle performance, strength, and exercise capacity, making it a popular ingredient among athletes, fitness enthusiasts, and people following active lifestyles. The creatine ingredients market is becoming an important part of the broader sports nutrition, dietary supplements, and health and wellness industries. Growing awareness of sports nutrition and increasing interest in maintaining physical fitness are supporting demand for creatine-based products. Beyond traditional sports applications, interest in everyday wellness and healthy ageing is also expanding the market to a wider range of consumers.
Creatine comes in several forms, but creatine monohydrate is the most common because it is well studied and widely used in sports nutrition. Standard powder is popular, while micronised powder is chosen by people who want it to mix more easily. Specially processed creatine products give manufacturers more ways to create new formulas. Creatine hydrochloride (HCl) and other forms help companies offer different products to meet specific customer needs. These options let brands serve a variety of uses, from sports nutrition to general wellness.
Application trends are also shaping the creatine ingredients market. Dietary supplements remain a key demand driver, particularly sports nutrition supplements used by athletes, gym-goers, and recreational fitness consumers. Health and wellness supplements offer opportunities to reach people who want to maintain an active lifestyle and support their nutritional needs. Functional foods and beverages represent another area of potential development as manufacturers explore ways to incorporate creatine into products beyond conventional supplement formats. Pharmaceutical, medical nutrition, and other applications may also drive demand, depending on formulation, intended use, and relevant regulatory requirements. As consumer interest in creatine grows, ingredient suppliers and finished-product manufacturers are focusing on quality, formulation suitability, and reliable supply.
Product quality and manufacturing skills are key to staying competitive. Manufacturers need to keep creatine pure and consistent from batch to batch, and meet customer needs for different product types. Better manufacturing, processing, testing, and quality control help suppliers deliver reliable products and meet the needs of supplement brands. Standardisation and good documentation matter for buyers who need dependable raw materials for large-scale production. As the market grows, companies that offer steady quality, reliable delivery, and good prices are more likely to build lasting customer relationships.
Innovation and product variety are shaping market competition. Manufacturers and supplement brands are working to make creatine easier to use, mix, and incorporate into different products. Creatine monohydrate remains the main type, but micronised and specially processed forms offer more options for new formulas. Companies are also meeting the demand for clear ingredient information, reliable quality, and products that fit specific customer needs. As a result, manufacturing skill, consistent products, and strong technical support are key when choosing suppliers. Although the creatine ingredients market is growing, it faces challenges. Competition between suppliers can lower prices and profits, and changes in raw material, production, and shipping costs can also affect earnings.
Manufacturers must maintain high-quality standards and follow food, supplement, and other regulations across markets. Also, awareness of creatine and its uses can vary by region and customer group. As a result, suppliers and brands need to provide clear product information and communicate effectively to stand out in a crowded market.
Competitive Landscape
Which are the Leading Players in the Creatine Ingredients Market ?
• AlzChem Group AG
• Inner Mongolia Chengxin Yongan Chemical Co., Ltd.
• Ningxia Taikang Pharmaceutical Co., Ltd.
• Shanghai Baosui Chemical Co., Ltd.
• Jiangsu Yuanyang Pharmaceutical Co., Ltd.
• Glanbia plc
• Vireo Systems, Inc.
• Qura Creatine
Driver
Growing Demand for Sports Nutrition and Dietary Supplements is Driving the Creatine Ingredients Market
Growing interest in fitness, strength training, sports performance, and active lifestyles is supporting demand in the Creatine Ingredients Market. Consumers increasingly incorporate dietary supplements into their routines to complement exercise and meet nutritional goals. Creatine has become an important ingredient in sports nutrition products, particularly those designed for individuals engaged in resistance training, gym workouts, and other physically demanding activities. As awareness of creatine supplementation expands beyond professional athletes to recreational fitness enthusiasts, demand for reliable, high-quality creatine ingredients continues to create opportunities for manufacturers. Creatine monohydrate is still the main product in sports nutrition supplements, backed by a lot of research. Standard powder is common in supplements, while micronised powder is chosen for better mixing. Speciality-processed creatine and creatine hydrochloride give brands more ways to stand out. The rise of health and wellness supplements and the trend of adding functional ingredients to foods and drinks also help drive demand. Manufacturers use direct sales to connect with supplement producers and big buyers, while distributors and traders help reach more markets. As more people get involved in fitness and sports nutrition, creatine ingredients are likely to see even more demand.
Restraint/Challenge
Price Competition, Quality Requirements, and Dependence on Sports Nutrition Demand Can Challenge Creatine Ingredients Market Expansion
The creatine ingredients market has to deal with pricing pressure, keeping manufacturing consistent, and competition between suppliers. Buyers look at things like purity, quality, price, supply reliability, and whether the ingredient fits their needs. These demands push manufacturers to offer good prices while still meeting high quality standards. Costs for production, raw materials, energy, and transport can also affect profits and how reliable the supply chain is. Competition between established brands and lower-cost suppliers also shapes the market.
Creatine monohydrate is widely accepted, but suppliers of other forms like creatine hydrochloride or speciality-processed creatine need to show what makes their products different. Manufacturers have to keep up with quality control, testing, and documentation to meet customer and regulatory expectations. Demand depends on how much consumers spend on supplements, which can change with the economy and buying habits. Companies can tackle these challenges by making manufacturing more efficient, keeping product quality steady, building strong customer relationships, and using reliable sales and distribution networks.
Creatine Monohydrate Segment is Expected to Account for a Significant Share of the Creatine Ingredients Market
Creatine monohydrate is expected to remain a leading product category in the Creatine Ingredients Market due to its established use in dietary supplements and sports nutrition formulations. Its broad recognition among athletes, gym-goers, and fitness-conscious consumers supports demand from supplement manufacturers seeking a widely accepted creatine ingredient. The availability of different formats also allows manufacturers to serve a range of formulation and consumer preferences.
Standard powder is important because it works well in many powdered supplements. Micronised powder has smaller particles, which helps it mix better. Speciality-processed creatine gives manufacturers more options if they want unique features or need to meet specific requirements. Other forms like creatine hydrochloride add variety and help brands reach different customers. Suppliers who offer pure, reliable, and well-priced ingredients will stay important partners for supplement makers. As more people use sports nutrition and dietary supplements, creatine monohydrate is expected to keep its strong market position.
Direct Sales Channel is Expected to Remain Important in the Creatine Ingredients Market
Direct sales are important in the creatine ingredients market because they let manufacturers build strong relationships with supplement makers, big buyers, and other business customers. This approach helps with long-term supply deals, custom orders, technical support, and better teamwork between manufacturers and their customers. For buyers who need steady supply and clear product specs, working directly with suppliers can make buying and quality checks easier. Distributors and traders also play an important role by connecting ingredient manufacturers with customers across different markets. They can help buyers access creatine ingredients from multiple suppliers and provide support with regional availability, logistics, and order management.
This channel can be particularly useful for customers that do not purchase in large volumes or require access to established local supply networks. The choice between direct sales and distributors and traders often depends on purchasing volumes, location, delivery requirements, and the level of supplier support needed. As demand for creatine ingredients expands across dietary supplements, sports nutrition, and other applications, both channels are expected to remain important to market access and supply-chain efficiency.
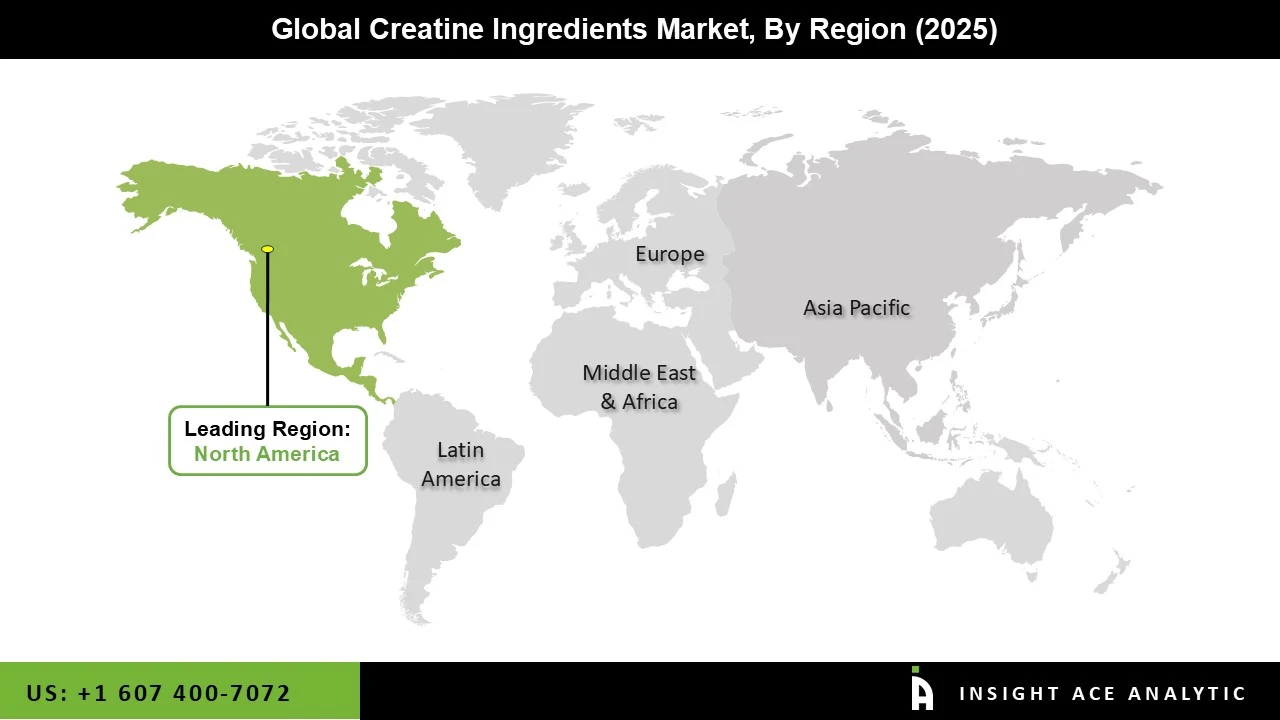
Why North America Remains an Important Region in the Creatine Ingredients Market
North America is an important region in the Creatine Ingredients Market, supported by an established sports nutrition industry, widespread participation in fitness activities, and strong consumer awareness of dietary supplements. The United States drives regional demand, with a broad base of supplement manufacturers, sports nutrition brands, ingredient suppliers, and consumers interested in fitness and active lifestyles. Creatine’s established position in sports nutrition supports demand from companies manufacturing products for athletes, gym-goers, and recreational fitness consumers.
Creatine Ingredients Market Report Scope:
| Report Attribute | Specifications |
| Growth Rate CAGR | CAGR of 8.7% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2021 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | Product Type, Application, Distribution Channel, and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico;France; Italy; Spain; South Korea; Southeast Asia; |
| Competitive Landscape | AlzChem Group AG, Inner Mongolia Chengxin Yongan Chemical Co., Ltd., Ningxia Taikang Pharmaceutical Co., Ltd., Shanghai Baosui Chemical Co., Ltd., Jiangsu Yuanyang Pharmaceutical Co., Ltd., Glanbia plc, Vireo Systems, Inc., Qura Creatine |
| Customization Scope | Free customisation report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customised to your particular study requirements. |
Market Segmentation:
Creatine Ingredients Market by Product Format-
• Creatine Monohydrate
o Standard Powder
o Micronized Powder
o Specialty-Processed
• Creatine Hydrochloride
• Other Creatine Forms
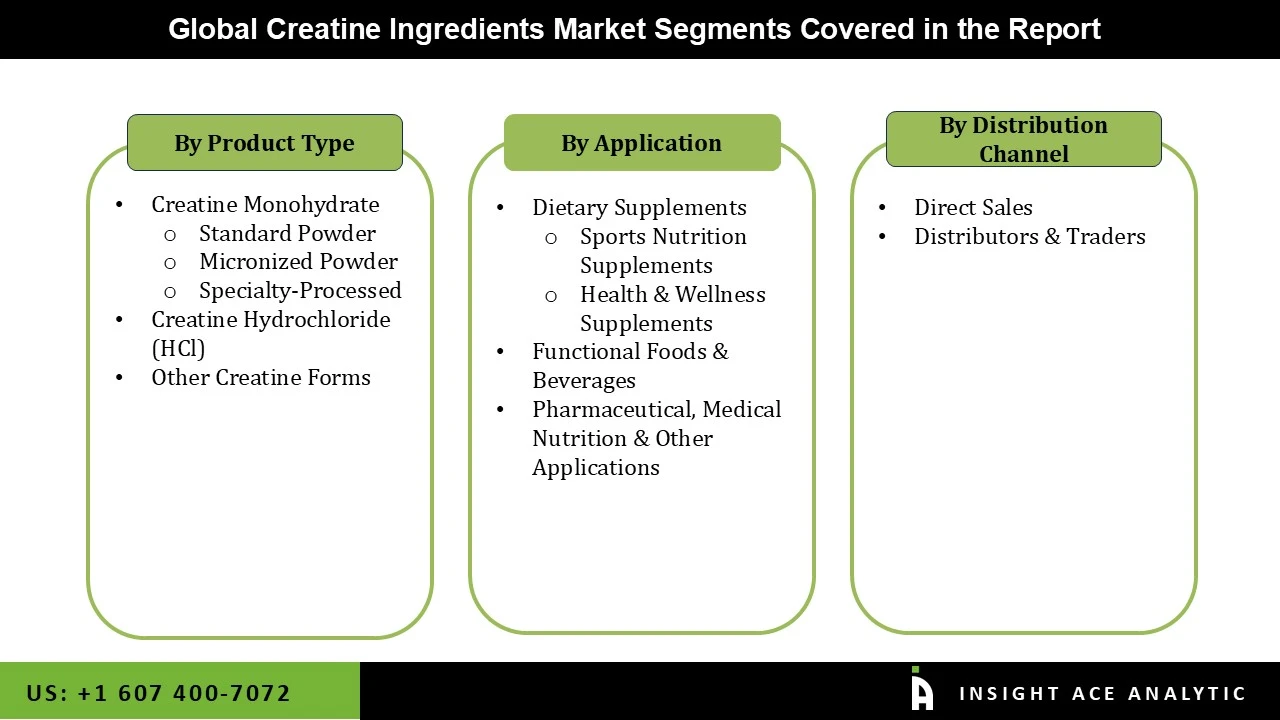
Creatine Ingredients Market by Application -
• Dietary Supplements
o Sports Nutrition Supplements
o Health & Wellness Supplements
• Functional Foods & Beverages
• Pharmaceutical, Medical Nutrition & Other Applications
Creatine Ingredients Market by Distribution Channel -
• Direct Sales
• Distributors & Traders
Creatine Ingredients Market by Region-
North America-
• United States
• Canada
Europe-
• Germany
• United Kingdom
• France
• Russia
• Italy
• Spain
• Rest of Europe
Asia Pacific-
• China
• India
• Japan
• South Korea
• Malaysia
• Thailand
• Indonesia
• Rest of APAC
South America-
• Brazil
• Mexico
• Argentina
• Rest of South America
Middle East & Africa (MEA)-
• GCC Countries
• South Africa
• Rest of MEA
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
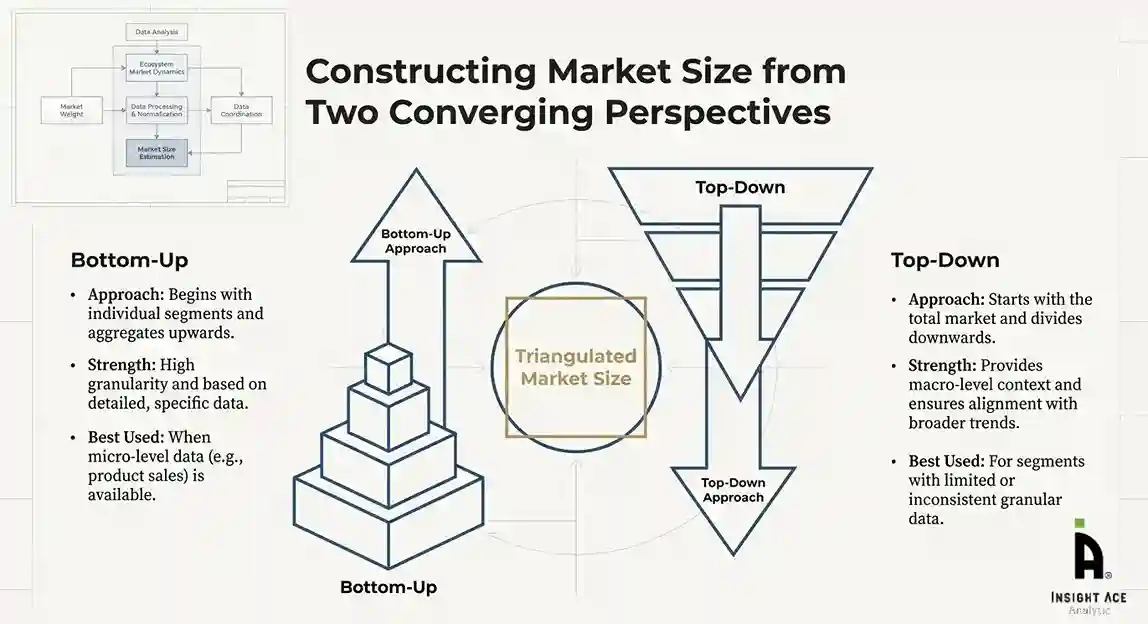
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
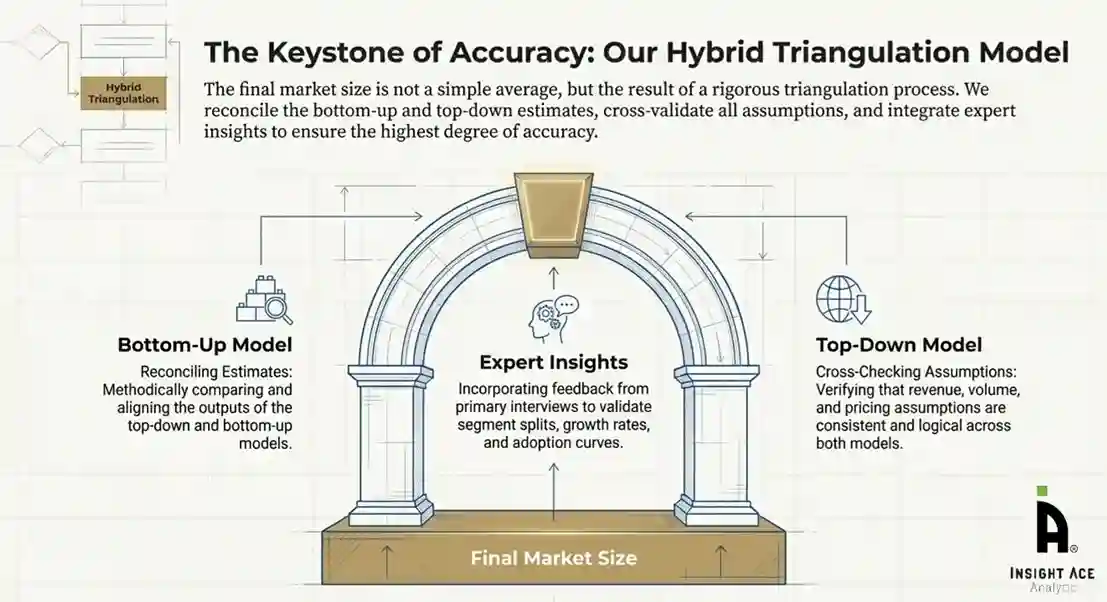
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
Creatine Ingredients Market is predicted to grow at 8.7% CAGR during the forecast period for 2026 to 2035.
AlzChem Group AG, Inner Mongolia Chengxin Yongan Chemical Co., Ltd., Ningxia Taikang Pharmaceutical Co., Ltd., Shanghai Baosui Chemical Co., Ltd., Jiangsu Yuanyang Pharmaceutical Co., Ltd., Glanbia plc, Vireo Systems, Inc., Qura Creatine
Creatine Ingredients Market is expected to grow Product Type, Application, Distribution Channel, and By Region.
North America region is leading the Creatine Ingredients Market.