Antibody-drug Conjugates (ADCs) CMO and CDMO Market Size, Revenue, Trend Report 2026 to 2035
What is Antibody-drug Conjugates (ADCs) CMO and CDMO Market Size?
Global Antibody-Drug Conjugates (ADCs) CMO & CDMO Market Size is valued at USD 9.23 Bn in 2025 and is predicted to reach USD 30.63 Bn by the year 2035 at a 12.7% CAGR during the forecast period for 2026–2035.
Antibody-Drug Conjugates (ADCs) CMO & CDMO Market Size, Share & Trends Analysis Distribution by Service / Value-Chain Stage, By Development Phase, By Conjugation Technology, By Antibody Construct Format, By Payload Class, By Customer / Sponsor Type, By Region, and Segment Forecasts, 2026–2035
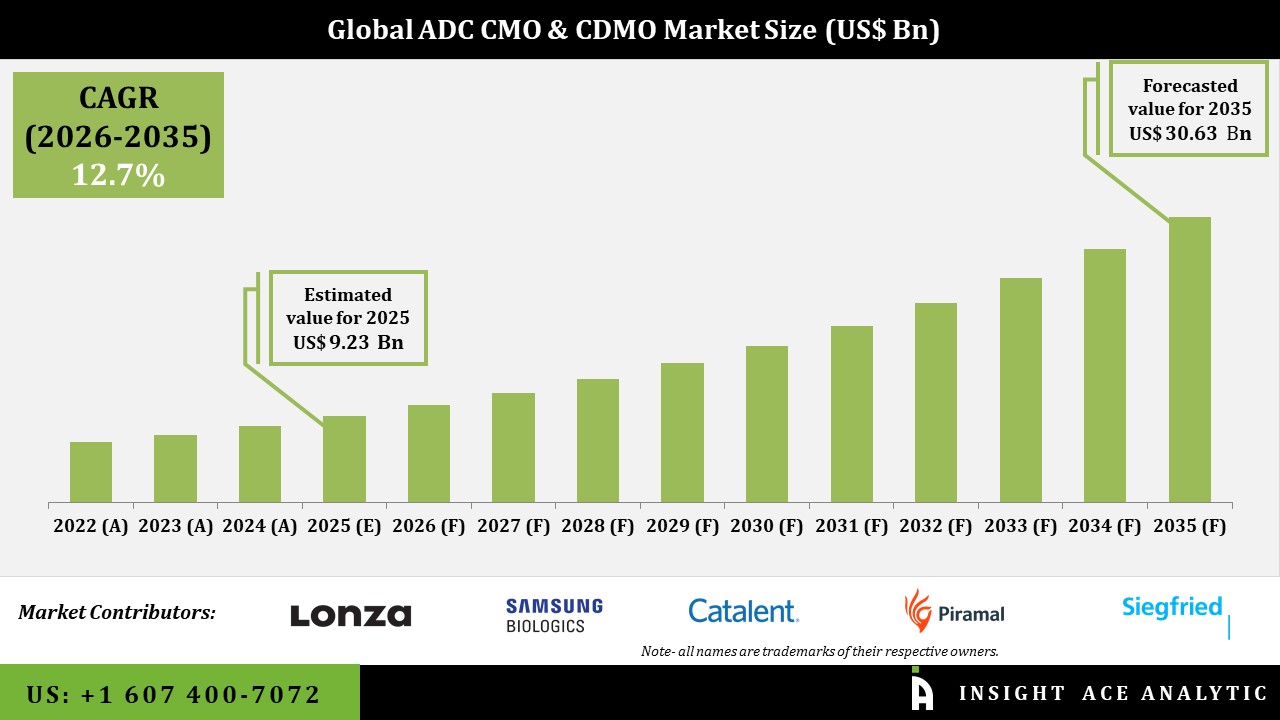
Antibody-drug conjugates are highly targeted biopharmaceutical therapies that combine monoclonal antibodies with potent cytotoxic drugs through specialized linker technologies. These therapies are designed to deliver cancer-killing agents directly to tumor cells while reducing damage to healthy tissues. Because of their complex structure and manufacturing requirements, ADC development requires advanced capabilities in antibody production, payload synthesis, linker chemistry, conjugation, analytical testing, fill-finish, and regulatory-compliant manufacturing.
Market growth is supported by the expanding ADC oncology pipeline, increasing approvals of ADC therapies, rising investment in targeted cancer treatments, and growing demand for end-to-end outsourcing solutions. CDMOs with expertise in biologics manufacturing, high-potency payload production, linker development, conjugation, process development, and commercial-scale manufacturing are expected to play an increasingly important role in supporting ADC innovation. As ADCs continue to gain importance in precision oncology, demand for specialized CMO and CDMO services is expected to increase steadily during the forecast period.
Competitive Landscape
Which are the Leading Players in Antibody-drug Conjugates (ADCs) CMO and CDMO Market?
-
Group A – Integrated ADC CRDMOs
● WuXi XDC Cayman Inc.
● Lonza Group AG
● Piramal Pharma Solutions
● Samsung Biologics Co., Ltd.
● LOTTE BIOLOGICS Co., Ltd.
● Abzena
● MabPlex International Co., Ltd.
Group B – Commercial-Proven Conjugation & High-Potency Drug Product Specialists
● BSP Pharmaceuticals S.p.A.
● Axplora (Novasep CDMO)
● Merck KGaA – MilliporeSigma
● CARBOGEN AMCIS AG
● Sterling Pharma Solutions Limited
● Cerbios-Pharma SA (HAS Healthcare Advanced Synthesis)
● Simtra BioPharma Solutions
Group C – Component, Containment & Conjugation-Technology Specialists
● Catalent, Inc.
● Ajinomoto Bio-Pharma Services
● CordenPharma International
● Veranova
● SK pharmteco
● Olon S.p.A. (incl. GTP Bioways)
● Formosa Laboratories, Inc.
● Symbiosis Pharmaceutical Services Limited
Group D – Emerging, Regional & Alliance-Based Participants
● Shilpa Biologicals Pvt. Ltd.
● Syngene International Limited
● Aurigene Pharmaceutical Services Limited
● Celonic Group
● AGC Biologics
● Porton Pharma Solutions Ltd.
● ChemExpress
● NJ Bio, Inc.
● Xcellon Biologics (watchlist – pre-GMP, tracked not sized)
Market Dynamics
Driver
Growing Demand for Accelerated Drug Discovery and Sustainable Materials
AI-driven computational chemistry software is being adopted by researchers to speed up the process of screening molecules of drugs and creating sustainable materials for energy storage and catalysis. Through the use of predictive models, a company can perform thousands of chemical experiments within hours rather than years, saving on R&D costs.
Restrain/Challenge
High Complexity and Data Standardization Issues
Another one of the key obstacles is the absence of standardized datasets for various fields in chemistry. There should be a variety of data to train AI algorithms, but problems with their structure prevent scaling. Also, the integration of quantum computing with classical AI systems is rather complicated.
ADC Drug Substance (GMP Bioconjugation) Segment is Expected to Drive the ADC CMO & CDMO Market
GMP bioconjugation of the ADC drug substance is the leading service stage, as it is the technically defining, high-value step that sponsors most often outsource to specialists with containment and conjugation expertise. Demand for GMP conjugation, purification and bulk drug-substance supply scales directly with the clinical and commercial ADC pipeline, reinforced by adjacent high-potency sterile fill–finish capacity.
Topoisomerase-I Inhibitor Payload Segment is the Fastest-Growing in the ADC CMO & CDMO Market
Topoisomerase-I inhibitor (DXd-class) payloads are the fastest-growing payload segment, driven by the clinical and commercial success of this chemotype and a broad pipeline of next-generation conjugates. This demand pulls specialist linker-payload (HPAPI) synthesis and site-specific conjugation capacity, while microtubule-inhibitor payloads remain a large installed base.
Why North America Led the Antibody-drug Conjugates (ADCs) CMO and CDMO Market?
North America held an advantage in the market during 2025 due to significant investments made towards AI-based research and development, the presence of major tech players, and the collaboration between the academic sector and industries.

The funding provided by the U.S. government for AI in pharmaceutical and material research, along with venture capital funding for new ventures, has expedited the use of the technology.
Antibody-drug Conjugates (ADCs) CMO and CDMO Market Report Scope:
| Report Attribute | Specifications |
| Market size value in 2025 | USD 9.23 Bn |
| Revenue forecast in 2035 | USD 30.63 Bn |
| Growth Rate CAGR | CAGR of 12.7% from 2026 to 2035 |
| Quantitative Units | Representation of revenue in US$ Bn and CAGR from 2026 to 2035 |
| Historic Year | 2022 to 2025 |
| Forecast Year | 2026-2035 |
| Report Coverage | The forecast of revenue, the position of the company, the competitive market structure, growth prospects, and trends |
| Segments Covered | By Service Type (The Workflow), By Process Component (The Molecule), By Linker Technology, By Phase of Development, By Target Indication (Disease Area), and By Region |
| Regional Scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Country Scope | U.S.; Canada; U.K.; Germany; China; India; Japan; Brazil; Mexico; The UK; France; Italy; Spain; China; Japan; India; South Korea; Southeast Asia; South Korea; Southeast Asia |
| Competitive Landscape | Schrödinger, Exscientia, DeepMatter, IBM, Microsoft, Google DeepMind, Citrine Informatics, Kebotix, BASF, Dassault Systèmes, Accenture, Aionics, Materials Zone. |
| Customization Scope | Free customization report with the procurement of the report, Modifications to the regional and segment scope. Geographic competitive landscape. |
| Pricing and Available Payment Methods | Explore pricing alternatives that are customized to your particular study requirements. |
Segmentations of Antibody-drug Conjugates (ADCs) CMO and CDMO Market:
By Service / Value-Chain Stage (Core – sizes the market)
● Discovery, Process & Analytical Development Services
○ ADC Candidate Design, Developability & Conjugation Screening
○ Conjugation Process Development, Scale-Up & Technology Transfer
○ Analytical Method Development, Characterisation & Stability
○ Formulation Development & Regulatory-CMC Support
● Antibody & Targeting-Protein Intermediate Manufacturing
○ Cell-Line Development & Upstream / Downstream Process Development
○ GMP Antibody, Fragment & Engineered-Scaffold Intermediate Supply
● Linker & Payload (HPAPI) Manufacturing
○ Cytotoxic Payload Route Design & HPAPI Synthesis
○ Linker Synthesis & Linker-Payload Intermediate Manufacturing
● ADC Drug Substance – GMP Bioconjugation
○ GMP Conjugation, Quench & Purification
○ Bulk Formulation, Bulk Drug Substance Filling & Release
○ Process Characterisation, PPQ & Continued Process Verification
● ADC Drug Product – High-Potency Sterile Fill–Finish
○ Aseptic Vial Filling & Lyophilisation under Containment
○ Visual Inspection, Labelling, Secondary Packaging & Commercial DP Supply
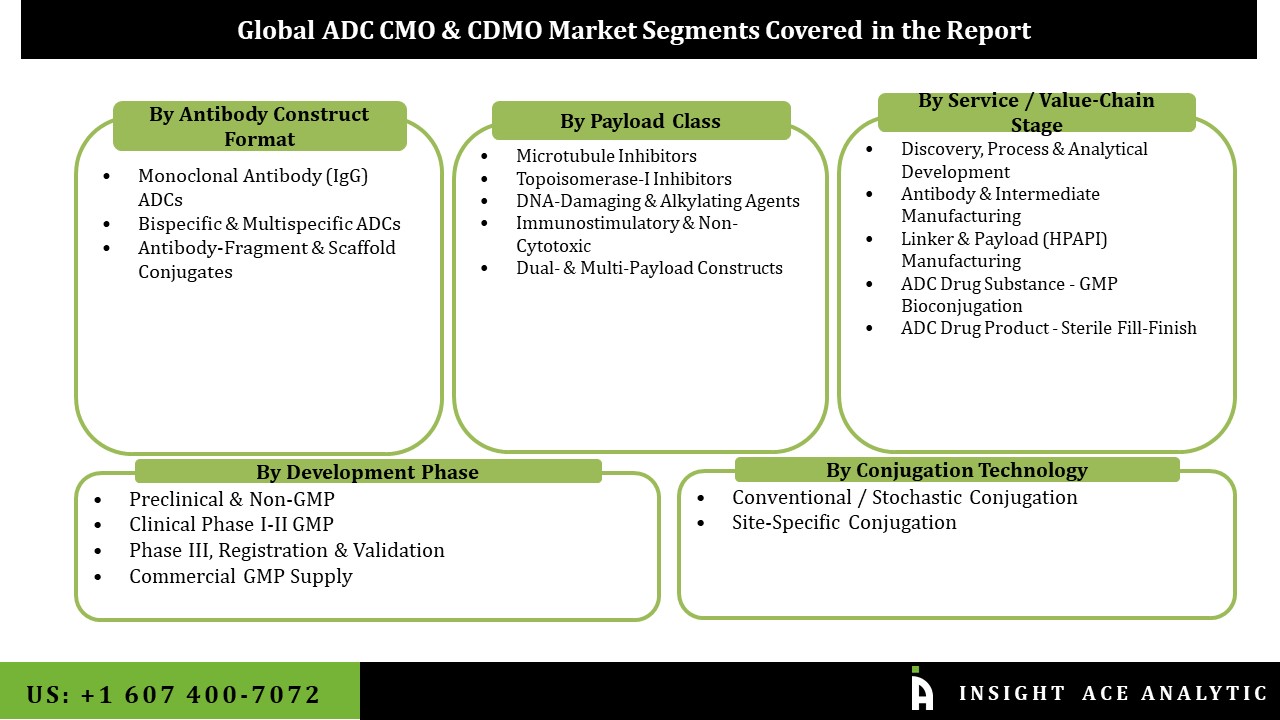
By Development Phase
● Preclinical & Non-GMP
● Clinical Phase I–II GMP Supply
● Phase III, Registration & Process Validation (incl. PPQ)
● Commercial GMP Supply
By Conjugation Technology
● Conventional / Stochastic Conjugation
○ Interchain-Cysteine Conjugation
○ Lysine-Based Random Conjugation
● Site-Specific Conjugation
○ Engineered-Cysteine & Thiol-Rebridging
○ Enzymatic & Chemoenzymatic
○ Glycan-Remodelling & Unnatural Amino Acid
By Antibody Construct Format
● Monoclonal Antibody (IgG) ADCs
● Bispecific & Multispecific ADCs
● Antibody-Fragment & Engineered-Scaffold Conjugates
By Payload Class
● Microtubule Inhibitors
● Topoisomerase-I Inhibitors
● DNA-Damaging & DNA-Alkylating Agents
● Immunostimulatory & Non-Cytotoxic Payloads
● Dual- & Multi-Payload Constructs
By Customer / Sponsor Type
● Large Pharmaceutical & Biopharmaceutical Companies
● Emerging & Mid-Size Biotechnology Companies
● ADC Platform & Technology Companies
● Academic, Government & Non-Profit Research Institutions
Antibody-drug Conjugates (ADCs) CMO and CDMO Market By Region-
- North America-
- The US
- Canada
- Europe-
- Germany
- The UK
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific-
- China
- Japan
- India
- South Korea
- South East Asia
- Rest of Asia Pacific
- Latin America-
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Middle East and Africa-
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Research Design and Approach
This study employed a multi-step, mixed-method research approach that integrates:
- Secondary research
- Primary research
- Data triangulation
- Hybrid top-down and bottom-up modelling
- Forecasting and scenario analysis
This approach ensures a balanced and validated understanding of both macro- and micro-level market factors influencing the market.
Secondary Research
Secondary research for this study involved the collection, review, and analysis of publicly available and paid data sources to build the initial fact base, understand historical market behaviour, identify data gaps, and refine the hypotheses for primary research.
Sources Consulted
Secondary data for the market study was gathered from multiple credible sources, including:
- Government databases, regulatory bodies, and public institutions
- International organizations (WHO, OECD, IMF, World Bank, etc.)
- Commercial and paid databases
- Industry associations, trade publications, and technical journals
- Company annual reports, investor presentations, press releases, and SEC filings
- Academic research papers, patents, and scientific literature
- Previous market research publications and syndicated reports
These sources were used to compile historical data, market volumes/prices, industry trends, technological developments, and competitive insights.
Primary Research
Primary research was conducted to validate secondary data, understand real-time market dynamics, capture price points and adoption trends, and verify the assumptions used in the market modelling.
Stakeholders Interviewed
Primary interviews for this study involved:
- Manufacturers and suppliers in the market value chain
- Distributors, channel partners, and integrators
- End-users / customers (e.g., hospitals, labs, enterprises, consumers, etc., depending on the market)
- Industry experts, technology specialists, consultants, and regulatory professionals
- Senior executives (CEOs, CTOs, VPs, Directors) and product managers
Interview Process
Interviews were conducted via:
- Structured and semi-structured questionnaires
- Telephonic and video interactions
- Email correspondences
- Expert consultation sessions
Primary insights were incorporated into demand modelling, pricing analysis, technology evaluation, and market share estimation.
Data Processing, Normalization, and Validation
All collected data were processed and normalized to ensure consistency and comparability across regions and time frames.
The data validation process included:
- Standardization of units (currency conversions, volume units, inflation adjustments)
- Cross-verification of data points across multiple secondary sources
- Normalization of inconsistent datasets
- Identification and resolution of data gaps
- Outlier detection and removal through algorithmic and manual checks
- Plausibility and coherence checks across segments and geographies
This ensured that the dataset used for modelling was clean, robust, and reliable.
Market Size Estimation and Data Triangulation
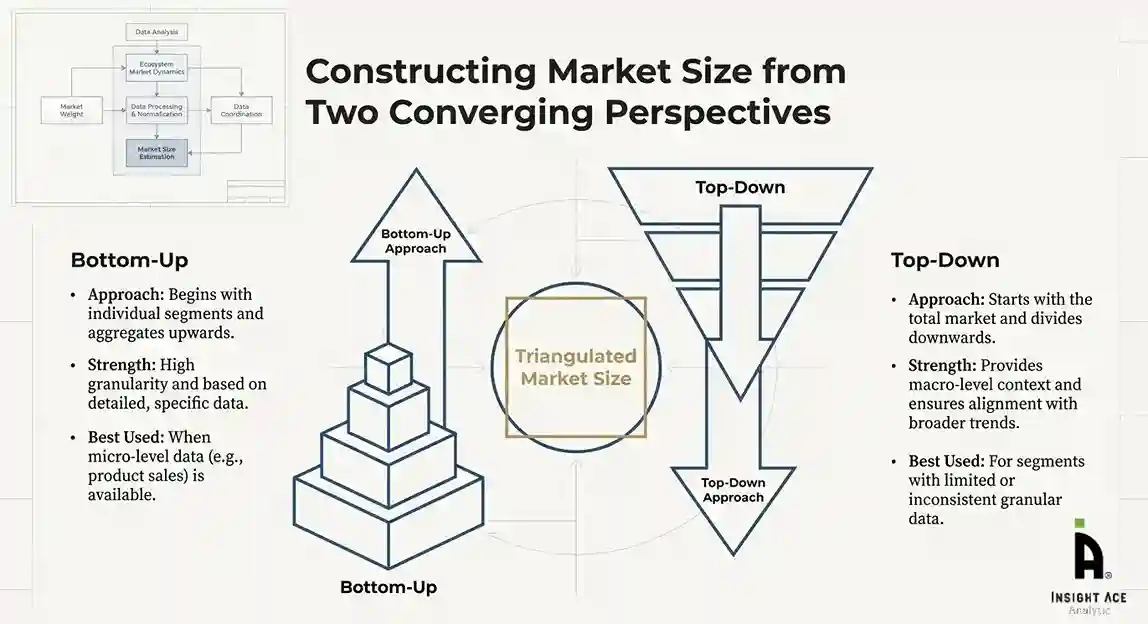
Bottom-Up Approach
The bottom-up approach involved aggregating segment-level data, such as:
- Company revenues
- Product-level sales
- Installed base/usage volumes
- Adoption and penetration rates
- Pricing analysis
This method was primarily used when detailed micro-level market data were available.
Top-Down Approach
The top-down approach used macro-level indicators:
- Parent market benchmarks
- Global/regional industry trends
- Economic indicators (GDP, demographics, spending patterns)
- Penetration and usage ratios
This approach was used for segments where granular data were limited or inconsistent.
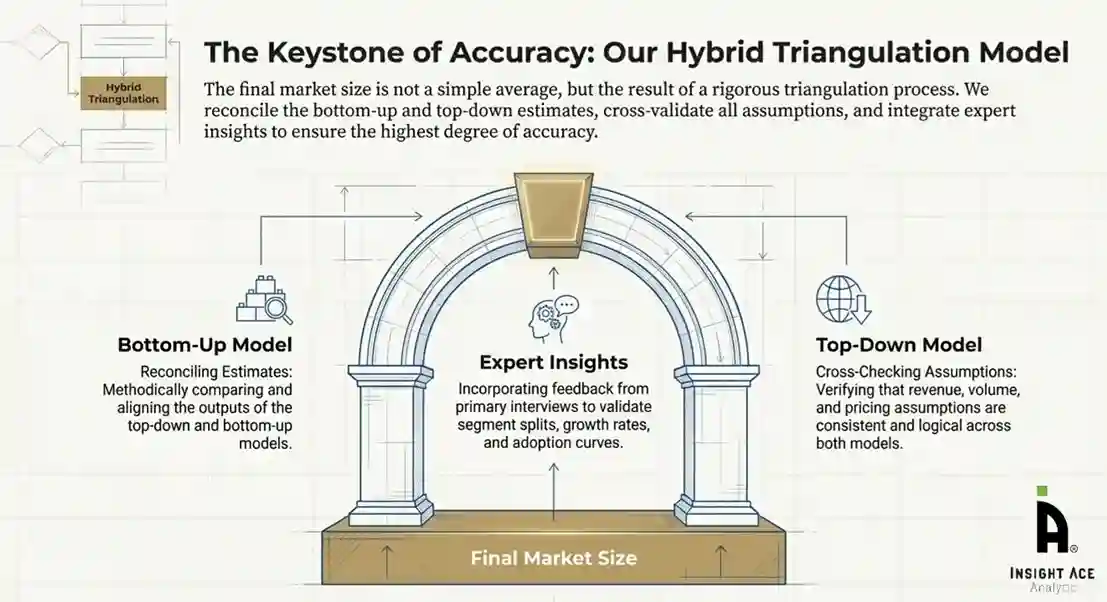
Hybrid Triangulation Approach
To ensure accuracy, a triangulated hybrid model was used. This included:
- Reconciling top-down and bottom-up estimates
- Cross-checking revenues, volumes, and pricing assumptions
- Incorporating expert insights to validate segment splits and adoption rates
This multi-angle validation yielded the final market size.
Forecasting Framework and Scenario Modelling
Market forecasts were developed using a combination of time-series modelling, adoption curve analysis, and driver-based forecasting tools.
Forecasting Methods
- Time-series modelling
- S-curve and diffusion models (for emerging technologies)
- Driver-based forecasting (GDP, disposable income, adoption rates, regulatory changes)
- Price elasticity models
- Market maturity and lifecycle-based projections
Scenario Analysis
Given inherent uncertainties, three scenarios were constructed:
- Base-Case Scenario: Expected trajectory under current conditions
- Optimistic Scenario: High adoption, favourable regulation, strong economic tailwinds
- Conservative Scenario: Slow adoption, regulatory delays, economic constraints
Sensitivity testing was conducted on key variables, including pricing, demand elasticity, and regional adoption.
Request Customization
Add countries, segments, company profiles, or extend forecast — free 10% customization with purchase.
Customize This Report →Enquire Before Buying
Speak with our analyst team about scope, methodology, pricing, or deliverable formats.
Enquire Now →Frequently Asked Questions
Antibody-drug Conjugates (ADCs) CMO and CDMO Market Size is valued at USD 9.23 Bn in 2025 and is predicted to reach USD 30.63 Bn by the year 2035
The Antibody-drug Conjugates (ADCs) CMO and CDMO Market is expected to grow at a 13.0% CAGR during the forecast period for 2026 to 2035
Schrödinger, Exscientia, DeepMatter, IBM, Microsoft, Google DeepMind, Citrine Informatics, Kebotix, BASF, Dassault Systèmes, Accenture, Aionics, Materials Zone. and Others.
Antibody-drug Conjugates (ADCs) CMO and CDMO Market is segmented into Service Type (The Workflow), Process Component (The Molecule), Linker Technology, Phase of Development, Target Indication (Disease Area), and Other.
North America region is leading the Antibody-drug Conjugates (ADCs) CMO and CDMO Market.